ClickCease

What is Working Capital?

What is Working Capital?

Learn About Working Capital and How it Works
1
Sep 2023
20
Oct 2026

A big part of business is focusing on profit margins and productivity, but keeping a business operating healthily gets a bit more complicated than that. One of the concepts you can’t afford to neglect is working capital. Working capital is a necessary data point for any business, and while sometimes it’s taking a bit more time to understand, it is absolutely crucial for maintaining a healthy balance sheet and operating effectively. We’re going to go over what working capital is, why it’s important, and some of its uses in the business world. Let’s get started.

What is Working Capital?

Working capital is essentially what you have left after taking out all the money you need to pay the bills. Think of it like you would in your personal life with a normal job. You get paid, you add up all your household bills and debts, set that money aside to take care of those necessary expenses, and you can work with whatever you have left. If needed, you also have assets you can leverage such as your savings, valuables, and other things that can help beyond the cash you have on hand. In more professional terms, this is everything you have, assets and cash on hand, minus the liabilities you have such as credit card debt, the bills necessary to keep the business running, payable taxes, and more. How you determine your overall working capital is by adding up your assets and financial resources and subtracting the total amount required to pay your expenses. We’ll keep it easy with solid numbers, but your actual calculation will likely be slightly more complicated. Let’s say you add up your assets and have $100,000 in value. After you add up your liabilities, you calculate that you have $50,000 to pay in total. $100,000 minus $50,000 is $50,000. That's your working capital.

Why is Working Capital Important?

Working capital is important in two main ways. At a first glance, it seems as if having as much of it available as possible, but that’s not quite accurate. Let’s go over both ways it can go and why balance is important.

What is Negative Working Capital, and Why it is Important?

This is the primary concern most business owners are going to have, and it’s certainly one that is most immediately noticeable. Negative working capital is when you use the formula we provided earlier, and you don’t have enough to cover your liabilities. That means you don’t have enough to pay your bills, essentially. If you don’t have the capital available to pay off your liabilities, you certainly can’t commit to any sort of growth, and the immediate future of your business doesn’t look promising, either. There are solutions to this that we will talk about later, but this is the worst-case scenario in a lot of situations.

What is Positive Capital, and Why it is Important?

Positive working capital is the opposite of negative working capital. It’s when you do have some resources left over to work with. For example, if you were the average homeowner working a normal job, you’d have some money left over after paying bills. Not all of it is “take home money”. Some of it has to go into savings in case you plan something big, like a major family trip abroad. The same concept goes for positive capital in business. That doesn’t mean that having it in extreme excess is optimal, though. In fact, it can mean that you’re making poor business decisions. If you regularly have way more working capital than expected, it typically means that you’re not taking advantage of growth opportunities, low debt situations, and other crucial parts of the business world. In the long term, this can mean that your business growth stagnant and that excess will start to decline eventually. It can also mean that you’re not providing reasonable upkeep for your business, which has major consequences, or it can mean that you’ve failed to account for various liabilities and your results are false; which is a major accounting error. In the vast majority of situations, you want to have your growth goals in mind, and you want enough to facilitate those goals. It’s also “working” capital. So, make sure it’s working for you.

How to Increase Working Capital for Higher Growth Potential?

Whether your business has a negative working capital amount, or you simply have larger growth goals you want to accomplish, increasing your working capital is usually going to be attractive. As long as you’re actually using it. Doing that can be difficult, but there are some key data points to target and strategies to use. Primarily, you’ll have two core options: You can increase the number of assets you have to offset your liabilities, or you can get rid of some liabilities such as debts that are close to being paid off.

Increasing Working Capital Assets:

Increasing your working capital assets is going to focus on improving your margins. The larger your margin is, the more working capital you’ll have left over assuming you don’t increase your liabilities. This is essentially the same as telling you to "earn more money”, which isn’t very constructive if money is the problem in the first place. If you’re already generating positive working capital, focusing some of those resources on short-term growth that helps with your margins is a strategy you can use. However, that’s a problem if you’re in the negative since you don't have anything to work with. For example, let’s say you have positive working capital, but you don’t have enough to focus on your goals. You might not be financially capable right now. Instead, pump some of that into marketing a big sale, increasing your inventory in high-demand areas, and similar things to earn more working capital. That’s where a working capital loan comes in, and we’ll get to that shortly.

Decreasing Liabilities to Gain Working Capital:

The other way to earn more working capital is to get rid of liabilities where possible. If there is debt that can be paid off in the short term, paying that off frees up a little more to go toward working capital amounts. If you can lower your tax liability, that’s another way to keep a bit more of your margin. It can also be possible to delay purchases. While growth is the ultimate goal, if you’re struggling to maintain a healthy balance sheet, delaying purchases until you can generate more working capital to accommodate them is crucial. For example, let’s pretend you’re a restaurant. You’re moving around $50,000, but after you pay your vendors, staff, and landlord, you’re only keeping $10,000, and that’s your net working capital. If you can consolidate some of this cost, for example automate ordering process and reduce waiter’s team, you can lower the liability cost and generate more profits. Again, this is something that a working capital loan can help with if liability removal strategies aren’t working or aren’t feasible.

What is a Working Capital Loan?

Alright, we’ve talked about a variety of issues that can pop up with working capital and damage your ability to grow, but now it’s time to start talking about real solutions. There are a lot of situations where you just don’t have any room to work with. You can’t boost your assets, because you don’t have capital, and you can’t remove any liabilities, because they’re all long-term, non-negotiable, and absolutely required. So, how do you get over that speed bump? Primarily, you can get a working capital loan. A working capital loan is a loan used to overcome cash flow problems; but it’s not just used in negative circumstances. Any business owner can benefit from one at a certain point, and it can be a positive experience. Here are some of the ways it’s used.

Funding Growth Goals

1. Funding Growth Goals

Sometimes, you’ll have growth goals, and you’ll have positive working capital, but you just don’t have enough funds. In that circumstance, you can use a working capital loan to get that extra bit of funding you need in the short term. For example, let’s say it’s the perfect time to open a new location, but you’re $20,000 short on the overall costs. A working capital loan can help. Of course, the payments will become liabilities later. So, it’s best to be in a relatively healthy position when using a loan for this purpose. For another perspective on using funding to support growth, read merchant cash advance funding for business growth.

2. Overcoming Financial Speed Bumps

Every business will experience a speed bump in its financial growth at some point. Take COVID-19 for example. Nearly every business went from doing great to suddenly seeing a drop in assets for one reason or another. A working capital loan can help overcome those bumps. If you go into the negative slightly, you can get a working capital loan that helps you remove smaller liabilities and invest in ways to build up non-depreciating assets to grow your margins. There are strategies involved in using a working capital loan this way, but one can save a business and keep it above water in such situations. It’s a lot like when you accidentally spend too much of your check as an average person, and your car payment is coming up. You don’t want to lose your car. So, you get a personal loan to cover it until you’re in a better situation.

3. Waiting on Invoice Payments

In an ideal world, all customers would pay on time, and you’d know exactly when funds were going to arrive. Unfortunately, that’s not how it works. Sometimes, you’ll technically have plenty of working capital on the horizon, but invoices just aren’t getting paid on time. A working capital loan can work like an advance on those invoices to make sure you’re still able to make moves while you wait.

4. Taking Advantage of Opportunities

Sometimes, you’ll be presented with opportunities you don’t want to pass up. For example, maybe you rely heavily on a supplier’s hardware for one of the products you manufacture. For a limited time, they’re offering half-off on bulk shipments of that hardware. That can allow for tremendous savings in the future and a lot of potential for growth. However, you might not have the ability to fund it without throwing your balance sheet off balance. This is another situation where a working capital loan can be the little edge you need to come out on top. Its fast, gets the job done, and keeps you from missing such fruitful opportunities.

Understanding the Working Capital Cycle

Beyond noticing problems with your working capital and finding solutions, you’re also going to want to look at the working capital cycle. This will help you predict when you’re going to have certain assets available, and that allows you to plan for them efficiently. The working capital cycle is the time it takes for your assets to become cash that can pay off your liabilities. For instance, think about the customer invoices for a subscription service. You know that 1000 customers are set to pay their invoice on the 30th. That means that, while you have those accounts as assets, they aren’t realized yet. You don’t actually have the money. The time between now and those payments clearing is your working capital cycle. After the 30th, you would be able to pay your liabilities in this scenario. As such, you want to streamline your working capital cycle as much as possible to ensure everything is moving quickly and efficiently. The best way to do this is to ensure that your customer payments are covering your liabilities. Since waiting for accounts to clear usually takes the longest, ensuring that they pay the liabilities off allows your other assets to simply keep growing and building up more working capital.

The Risk of Certain Working Capital Assets

You’ve probably put together a decent understanding of what working capital assets are at this point. If not, the basics are your customer invoices, inventory, cash, and pre-paid debts. One of those is somewhat volatile, and you shouldn’t aim to build much of your working capital on it. That’s your inventory. Your inventory can be a risky asset. It can become obsolete, depreciate in value, and dramatically impact your working capital amount without any chance of turning into cash. Take fidget spinners for example. During the craze, everyone stocked up on them. That was almost guaranteed cash flow. However, when the trend stopped, that inventory became largely useless. Anyone with too much inventory consisting of that product saw their cash flow tank. This can happen with anything. So, it’s important to understand that risk, diversify assets, and have a solid plan to use your inventory; not just stockpile it for perceived working capital. Think of all the people who bought into Beanie Babies in the 90s, and then think of what happened a few years later when no one cared. The Beanie Babies represent your inventory, and no one caring represents your entire inventory devaluing like crazy. You don’t want things sitting around unless they are guaranteed to be necessary for the future.

3 Types of Working Capital

The Three Types of Working Capital and How to Differentiate

Finally, there are three types of working capital, and while they all generally work the same way, you will need to differentiate between them.

1. Net Working Capital

This is all the working capital you have at your disposal, and it’s the general number that you’re going to want to keep tabs on.

2. Temporary Working Capital

This is your working capital amount in temporary situations. Think of things such as the speed bumps we talked about earlier, or maybe even expected boosts such as holiday sales. Since the causes for the fluctuations are temporary, you have to work that into your understanding of your working capital during that time period.

3. Permanent Working Capital

The name of this one is misleading. It’s not the amount you’re guaranteed to have all the time. It’s the amount you absolutely need to make it. If you make less, your business’s health starts dropping, and you either fix it or lose it. This is the bottom line of what you need to barely get by, and you want to calculate it regularly since your liabilities and assets will change regularly.

Get a Working Capital Loan with 2M7 Financial Solutions

If you’ve gone through this brief guide and realized you could really use a working capital loan to help your business for any reason, contact us to start the process. We specialize in advanced loans that can help your business seize opportunities, fix temporary problems, and continue operating in a healthy state.

Related articles

April 13, 2023
August 11, 2026

The Small Business Owner's Guide to Business Loans in Canada

There is a wide array of services available to businesses in Canada seeking to bolster their cash liquidity. This article will explore some of the most popular options, as well as their best use cases. These financial solutions typically include a combination of bank loans, government business grants, factoring, cash advances, payday loans, and microloans.

Businesses can utilize these financial options to optimize growth, gain liquidity, bridge emergency situations, or capitalize on opportunities.

Let's delve into our options:

1. Traditional bank loans

This is the most conventional form of financing that small businesses can utilize to obtain. Typically, these loans are secured by collateral, and may offer lower interest rates, making them an appealing choice for businesses with strong credit. However, small and medium-sized businesses adhering to conservatism and GAAP principles might have lower perceived financial strength, which can make obtaining traditional financing more challenging, especially if the bank relies on financial statements as part of its due diligence process. This can be particularly problematic for new startups and businesses without a significant financial track record. Furthermore, liquidity provided might be limited if a business is relatively new or experiencing volatility, even with collateral in place.

2. Factoring

Factoring enables businesses to sell their accounts receivable (invoices) to a third-party (a factoring company) at a discount. The factoring company then acts as the agent to collect payments from the invoice customer, providing the business with liquidity (cash) based on a certain percentage of the invoice amount. Factoring can significantly improve cash flow for small and medium-sized businesses by offering liquidity and quick access to funds. It is also helpful that the factoring company will be the one taking care of ensuring invoices are paid, freeing up valuable resources for small businesses.

3. Government business grants

The Canadian government provides an array of business grants designed to help small businesses flourish. These grants typically target specific industries or business activities, such as clean technology, innovation, workforce development, and international trade, among others. A considerable number of grants currently emphasize research, development, and exporting. The application process for these grants can be intricate, requiring well-prepared grant proposals that effectively communicate the business's objectives, anticipated outcomes, and potential impact. This process is often competitive, as numerous businesses vie for the limited funding available. Newer businesses or those without prior grant writing experience may find this process daunting, and may benefit from seeking professional grant writing assistance or collaborating with experienced partners in their industry. Despite the challenges, securing a government grant can be a game-changer for small businesses, providing essential funding without the burden of repayment, and fostering growth, innovation, and competitiveness in the marketplace.

4. Payday loans or Microloans

Payday loans and microloans are small, short-term loans that are typically utilized to address unexpected expenses or navigate temporary cash flow gaps. While these loans may not be suitable for long-term financing needs due to their relatively higher interest rates and fees, they play a vital role in providing financial support during emergencies. By offering quick access to funds, payday loans and microloans help businesses remain afloat and operational during challenging times, allowing them to successfully weather temporary cash flow issues that are anticipated to improve in the near future. This targeted financial assistance can be a lifeline for businesses, enabling them to maintain stability and continue serving their customers as they work towards recovery and growth.

5. Merchant Cash Advance

A cash advance, particularly in the form of a Merchant Cash Advance (MCA), is an innovative financing solution that provides businesses with a lump sum of cash in exchange for a percentage of their future sales (typically credit card sales). Cash advances and MCAs can be exceptional financing options for businesses that need funds swiftly or require increased liquidity to seize opportunities that demand prompt. One of the key advantages of this financing option is its speed and flexibility. Cash advances can be processed more quickly than traditional loans, often within a matter of days, allowing businesses to address their financial needs without delay. Additionally, repayment terms are tailored to the business's sales volume, making it a more manageable solution for businesses with fluctuating revenues. MCAs are particularly valuable for new businesses and small enterprises that may face challenges in obtaining traditional bank loans due to a lack of financial history, inadequate financial book strength, or a dearth of collateral. By offering an alternative financing avenue, cash advances empower these businesses to overcome financial barriers and pursue their growth objectives. Ultimately, the various financing options available to Canadian businesses each have their own strengths and specific use cases. Traditional bank loans can be attractive for businesses with strong credit, while CEBA loans offer interest-free financing for those affected by the COVID-19 pandemic. Factoring provides immediate liquidity to businesses with outstanding invoices, and government grants can support targeted industries and activities. Payday loans or microloans can assist in managing short-term cash flow gaps. And cash advances offer rapid access to funds for businesses lacking financial history or collateral. The choice of financing option will depend on the unique needs and circumstances of each business. By understanding the advantages and limitations of each option, businesses can make informed decisions about the most suitable financing solution to support their growth, liquidity, and success.

Read more
August 19, 2026
September 30, 2026

Preparing Your Business for the Holiday Rush

The fourth quarter makes or breaks a lot of small businesses in Canada. Retailers and restaurants that get their staffing and inventory right in October and November tend to walk into January with healthy cash reserves. Those that wait until the first week of December to figure out their game plan usually spend the season scrambling, and scrambling costs money.

If you own a retail shop, a restaurant, or any business that lives and dies by foot traffic during the holidays, now is the time to lock in your plan. Here's how to think about staffing, stock, and cash flow so the next ten weeks work in your favour instead of against you.

‍

Start With Your Sales History, Not Your Gut

Too many owners plan the holiday season based on how busy last December felt rather than what the numbers actually showed. Pull your point-of-sale reports from the last two or three holiday seasons and look for patterns. Which products sold out early? Which days of the week saw the heaviest traffic? What time of day did your restaurant get slammed?

Analyzing past sales data to spot seasonal patterns is one of the most effective ways to avoid overstocking or running out of popular items. This isn't complicated analysis. Even a basic spreadsheet showing week-over-week sales from last November and December will tell you more than a gut feeling ever will.

For retailers specifically, this is also the moment to think seriously about how much inventory you actually need on hand versus how much cash you're willing to tie up in stock that might not move. If you've been turning down orders because you can't front the cost of holiday inventory, you might want to consider your options before you're forced to choose between restocking and making payroll.

‍

Staffing: The Problem Nobody Talks About Early Enough

Here's a fact that should change how you're thinking about hiring right now. The National Retail Federation recently predicted that holiday seasonal hiring would hit its lowest level in over 15 years, making early recruitment more critical than ever. That forecast is for the American market, but Canadian retailers and restaurants are competing for the same shrinking pool of available seasonal workers, and the labour crunch tends to move north with a short delay.

Practically, this means posting your seasonal job openings now, not in mid-November. It means offering shift flexibility and being upfront about pay. It also means having a real contingency plan if you can't fill every shift you need.

For restaurants, the stakes are a bit different but no less serious. Using past data to anticipate peak times helps restaurants build optimized schedules without over- or under-staffing. A kitchen that's short-staffed on a Friday night in December doesn't just lose sales, it loses customers who won't come back after a bad experience. If your restaurant's equipment is also aging and slowing down your kitchen's throughput during peak hours, that's a separate problem worth solving before the rush hits.

What Canadian Shoppers Are Actually Doing Differently

It's not enough to staff up and stock up the way you did last year. Consumer behaviour is shifting, and ignoring that shift means missing opportunities your competitors will catch. According to Retail Council of Canada's holiday shopping research, Canadian consumers are shopping earlier and comparing prices more carefully than in past years.

That earlier-shopping trend matters because it means your marketing and inventory need to be ready well before Black Friday, not scrambling to catch up to it. If your customers are comparison shopping more aggressively, your pricing, promotions, and in-store or online experience need to justify why they should buy from you instead of clicking over to a competitor's site.

Refreshing your online listings and promoting gift cards are easy, high-impact ways to prepare for the holiday shopping rush. Simple, low-cost moves like updating your Google Business listing, refreshing your website's holiday hours, and pushing gift card sales through email and social media can generate real revenue with almost no upfront cost.

‍

Give Shoppers a Reason to Walk Through Your Door

If customers are comparing prices and shopping online, your store has to earn the trip. Start with the basics: a slow checkout is one of the fastest ways to lose a holiday sale, so add a second register during peak hours and make sure your POS is ready for the volume. Then give people a reason to come in. A coupon, a limited-time discount, or a buy-one-get-one deal can do it. Costco has held its hot dog and soda combo at $1.50 since the mid-1980s because it draws people in, and they usually leave having bought a lot more than lunch.

Finally, walk your shop the way a customer would. A clean storefront, fresh signage, and a seasonal display cost far less than the sales they protect.

‍

Where Fast Funding Fits Into the Picture

Every piece of holiday prep costs money before it generates a dollar back. Inventory has to be purchased before it's sold. Staff have to be hired and trained before they're productive. Equipment repairs have to happen before the kitchen can handle a full house on a Saturday night.

This is where a lot of small business owners hit a wall, particularly if a bank has already turned them down or they don't have the time to wait six weeks for a traditional loan decision. A Merchant Cash Advance is built for exactly this kind of short-term, high-stakes timing problem. Rather than waiting on a lengthy approval process, you're leveraging future sales to access capital now, when you actually need it, not after the holiday window has already closed.

If your credit history isn't perfect, that shouldn't be the reason you miss the busiest quarter of your year. Many alternative lenders look past your credit score and focus on your recent revenue instead of your past setbacks. Fast business funding and small business loans through alternative lenders exist precisely because traditional banks move too slowly and too conservatively for the realities of running a seasonal business. 

Contractors and trades businesses often assume holiday funding conversations don't apply to them, but late Q4 and early Q1 are when many trades see a surge in emergency repair calls and pre-holiday renovation rushes. Having working capital on hand means you can staff up and stock materials without cash flow becoming the bottleneck.

‍

Get Ahead of It Now

Waiting until December to figure out staffing, inventory, and cash flow puts you behind before the season even starts. The businesses that come out of Q4 stronger are the ones making these decisions in October and November, while there's still time to act on them.

If you need capital to hire, stock up, or fix equipment before the rush hits, reach out to 2M7. We move fast, we understand Canadian small business realities, and we can get you funded well before you would have finished filling out bank paperwork.

Read more
October 15, 2026
October 15, 2026

Best unsecured business loans in Canada 2026

Best overall for a defined expense: an unsecured term loan. Best for recurring cash flow gaps: an unsecured business line of credit. Best alternative to compare for revenue-based funding: 2M7, a direct funder offering merchant cash advances, not loans. This 2026 guide compares unsecured business loans in Canada with other funding structures, including where each option falls short.

TL;DR

  • Unsecured business loans suit defined expenses when scheduled payments fit your cash flow.
  • An unsecured business line of credit suits recurring working capital gaps, not permanent operating losses.
  • 2M7 offers merchant cash advances, not loans; confirm security requirements before treating an offer as unsecured.
  • Compare total repayment, personal guarantees and payment frequency before choosing business funding in Canada.

Why this matters

Unsecured does not mean the owner has no personal exposure. An unsecured business loan generally does not require specific collateral, but a lender can still require a personal guarantee. Read the actual agreement rather than relying on the product label.

That distinction matters when comparing offers in 2026. A loan, a revolving credit facility and a merchant cash advance have different structures. Choosing between them starts with what you need the money to do and how your business will meet the payment schedule.

This shortlist ranks funding structures by use case, not individual lenders by advertised claims. There is no universal winner: a facility that handles recurring inventory purchases is not automatically the right choice for a single equipment purchase.

What makes the best unsecured business loans?

Use these criteria before choosing a funding provider:

  • Purpose fit: Match a defined purchase to structured funding and recurring gaps to reusable credit.
  • Security requirements: Check for personal guarantees, security interests and claims against business assets.
  • Payment fit: Test the actual payment frequency against when customers pay you.
  • Total obligation: Compare the amount received, total repayment and all disclosed charges together.
  • Eligibility fit: Check operating history, revenue requirements and documentation before applying.
  • Exit terms: Understand early repayment, renewal and what happens after a missed payment.

For your 2026 comparison, use written offers rather than headline descriptions. Compare equivalent funding amounts and payment periods wherever possible. Otherwise, differences in structure can obscure what you are actually committing to repay.

Unsecured business funding options at a glance

Unsecured term loan

  • Best for: A defined expense with a repayment plan
  • Standout feature: A lump sum repaid over an agreed term
  • Key limitation: Scheduled payments continue when sales slow

Unsecured business line of credit

  • Best for: Recurring working capital gaps
  • Standout feature: Credit can be reused within the agreement's limit
  • Key limitation: Access remains subject to the facility's terms

2M7 merchant cash advance

  • Best for: Established revenue-generating businesses comparing loan alternatives
  • Standout feature: Direct funding with one fixed cost of capital disclosed before signing
  • Key limitation: Not a loan; security requirements need confirmation

Business credit card

  • Best for: Routine purchases accepted by card
  • Standout feature: Purchase-by-purchase access to revolving credit
  • Key limitation: A persistent carried balance creates an ongoing financing obligation

The merchant cash advance belongs here as an alternative, not as another name for an unsecured loan. Its inclusion does not establish that a particular offer is unsecured.

1. Unsecured term loan: best for a defined expense

An unsecured term loan provides a lump sum that you repay over an agreed period. It suits an expense with a clear purpose, such as a business improvement, when operating cash flow supports the scheduled payments.

Start with the expense, not the largest amount offered. Your repayment plan should identify where the payment comes from even if the purchase takes longer than expected to generate revenue.

Unsecured term loan pros:

  • A defined repayment period gives you an endpoint to plan around.
  • A scheduled payment creates a clear recurring cash commitment.
  • A lump sum supports an expense that must be paid upfront.

Unsecured term loan cons:

  • Scheduled payments do not disappear during slower trading periods.
  • A personal guarantee can create exposure beyond the business.
  • Early repayment terms differ between agreements.

Best for: A business with a defined expense and sufficient cash flow to support the proposed schedule.

Before accepting a 2026 offer, ask whether the payment can change, whether early repayment changes the total obligation and what triggers default. Obtain those answers in the agreement, not just in a conversation.

Verdict: Hold until the scheduled payment fits both normal and slower trading periods.

2. Unsecured business line of credit: best for recurring gaps

An unsecured business line of credit lets you draw funds within an approved limit and reuse credit as you repay, subject to the agreement. It suits timing gaps between business expenses and customer receipts.

The distinction is simple: a line of credit addresses a recurring timing problem, not an expense that permanently exceeds revenue. If the balance never comes down, examine the underlying cash flow problem before requesting more credit.

Unsecured business line of credit pros:

  • You can draw against the facility as a funding need arises.
  • Repayment restores access to credit within the agreement's terms.
  • Reusable credit matches repeated working capital needs.

Unsecured business line of credit cons:

  • The lender's agreement governs continued access and reviews.
  • Repeated drawings can conceal a persistent operating shortfall.
  • A personal guarantee can still be required.

Best for: A business with recurring, identifiable gaps between payments out and receipts in.

Ask what documentation the lender requires to maintain the facility. Also establish whether the lender can change the limit or demand repayment under specified circumstances. Available credit is useful only when you understand the conditions attached to it.

Verdict: Hold until you can explain how customer receipts will reduce each drawing.

3. 2M7 merchant cash advance: best for comparing loan alternatives

2M7 provides merchant cash advances and working capital directly to Canadian businesses. It is a direct funder, not a broker, and its product is not a loan.

2M7 is best for Canadian business owners comparing merchant cash advances with unsecured business loans. Its stated eligibility includes at least 3 months in business and $15,000 or more in monthly revenue, including businesses with less-than-perfect credit. Meeting those thresholds does not establish approval.

2M7 merchant cash advance pros:

  • You deal with a direct funder rather than a broker.
  • One fixed cost of capital is shown before signing.
  • The fixed cost does not change based on how long repayment takes.
  • Less-than-perfect credit is included in the stated customer profile.

2M7 merchant cash advance cons:

  • It is not suitable for a business specifically seeking a loan agreement.
  • The stated operating history and revenue thresholds exclude some applicants.
  • Flex payments apply only to businesses processing daily card payments.

Best for: A revenue-generating Canadian business evaluating working capital outside a conventional loan structure.

The published approval rate is 75%, not a promise of approval for an individual applicant. Before accepting an offer, confirm the payment mechanism, total repayment obligation, security requirements and any personal guarantee.

Do not assume a merchant cash advance is unsecured simply because it appears in a comparison of unsecured funding. The agreement determines the obligations.

Verdict: Hold until the written offer confirms that the structure and payment terms fit your business.

4. Business credit card: best for routine purchases

A business credit card provides revolving credit for purchases that merchants accept by card. It suits routine expenses when you have a clear plan to pay the statement balance.

A card is not interchangeable with working capital deposited into your business account. Check how the intended expense can be paid before choosing this route, especially for payroll or supplier obligations that do not accept card payments.

Business credit card pros:

  • You can fund individual purchases rather than draw a lump sum.
  • Statements create a record of card transactions.
  • Revolving credit can support recurring purchasing needs.

Business credit card cons:

  • Not every business expense can be paid by card.
  • Carrying a balance creates an ongoing financing obligation.
  • Personal guarantees and liability terms require review.

Best for: Routine card-eligible purchases supported by a specific repayment plan.

Read the terms for purchases, cash advances and missed payments separately. Those transactions can have different conditions. Do not treat the credit limit as a target spending amount.

Verdict: Skip for persistent cash shortfalls; hold for routine purchases until repayment is planned.

How these options were ranked

The ranking follows purpose fit, payment fit, security requirements, total obligation, eligibility and exit terms. A term loan comes first for a defined expense because the funding and repayment period can be matched to that expense. A line of credit takes the recurring-gap slot because it can be reused.

The merchant cash advance occupies a separate loan-alternative slot. A business credit card ranks for routine purchases rather than general funding needs. No provider receives a blanket recommendation based on an advertised approval rate or a product name.

How to compare written funding offers in 2026

Use the same review sequence for each offer. This keeps a clear application process from distracting you from an unsuitable agreement.

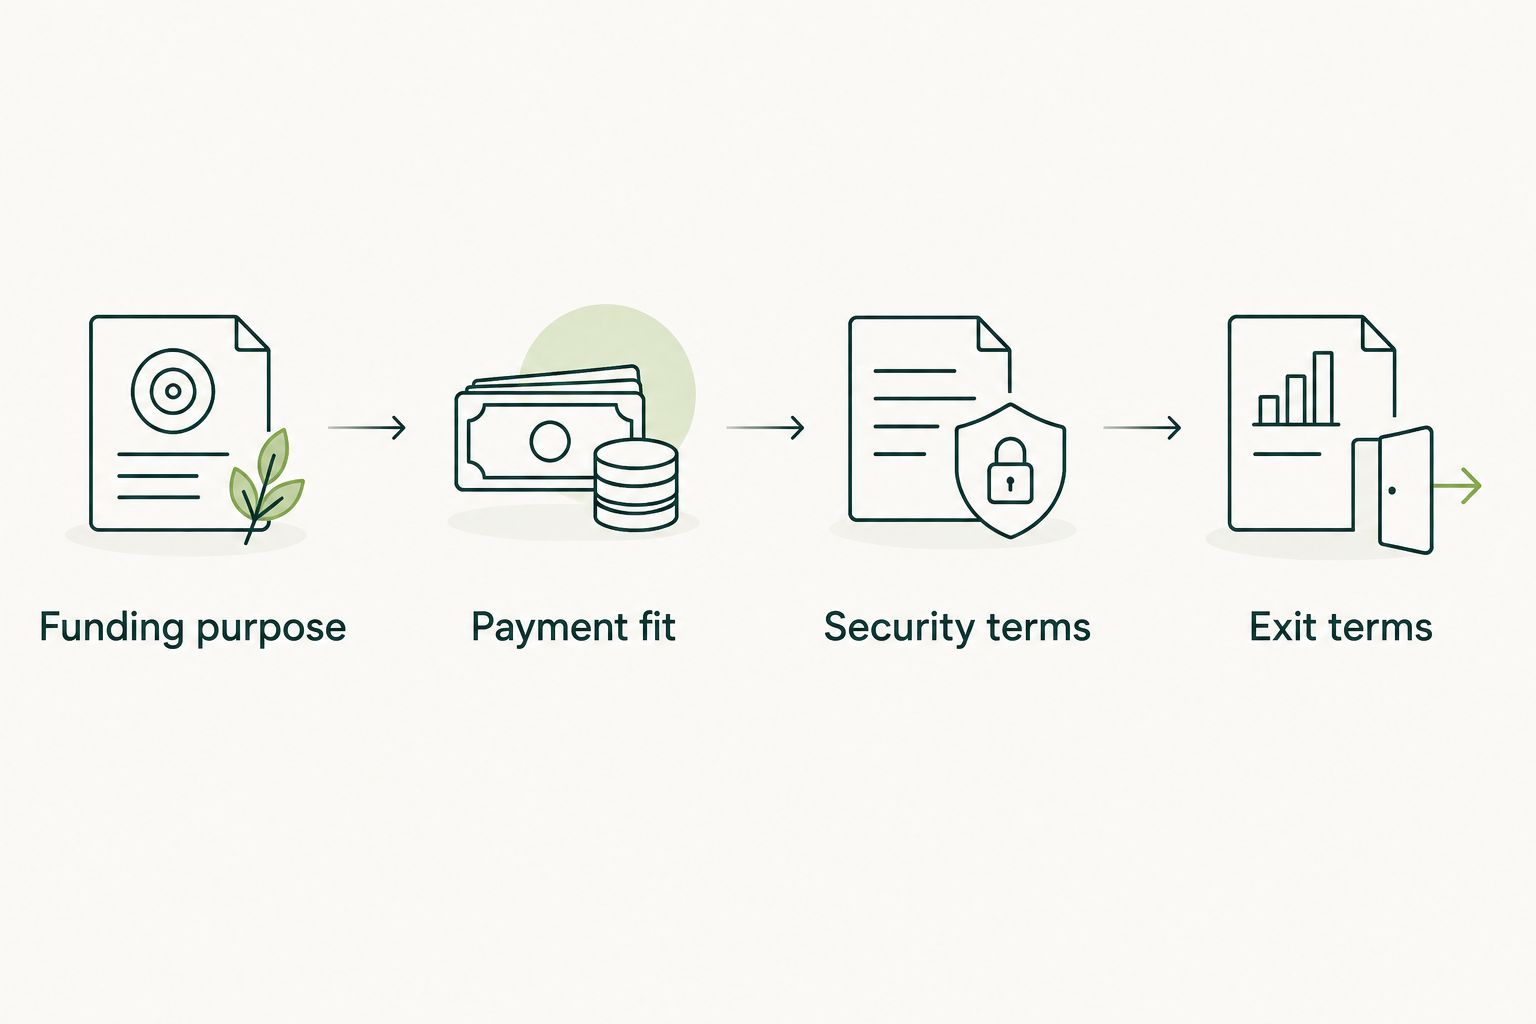
Funding purpose

Write down exactly what the funding will pay for. Separate a single purchase from a recurring operating gap, and distinguish delayed customer receipts from expenses that exceed revenue.

Payment fit

Place the proposed payments beside your expected customer receipts. Review both the amount and frequency. A payment that looks manageable in a monthly summary can still fall at the wrong point in your operating cycle.

Security terms

Ask for every personal guarantee and security provision to be identified. Confirm which party is responsible, what assets are involved and what happens if the business misses a payment.

Exit terms

Read the early repayment, renewal and default provisions before signing. Ask whether paying sooner changes what you owe and whether additional funding requires a new agreement.

Four offer-review steps covering purpose, payments, security and exit terms.

Review the agreement's obligations before choosing the funding structure.

Keep the final offer and agreement together. If a verbal explanation differs from the documents, ask for clarification before accepting. The decision should rest on the terms you will actually sign.

Which unsecured business funding should you choose?

Choose an unsecured term loan as the default for a defined expense only when scheduled repayments fit your cash flow. Choose an unsecured business line of credit for recurring timing gaps that customer receipts will clear.

Compare a merchant cash advance when you want a loan alternative and understand its payment structure. Keep a business credit card for suitable purchases rather than treating it as a general solution to an ongoing operating deficit.

The deciding question in 2026 is not simply whether funding is unsecured. It is whether the written obligation fits the business that must meet it.

FAQ

What's the best unsecured business loan in Canada in 2026?

An unsecured term loan is the default option to compare for a defined expense with a clear repayment plan. An unsecured business line of credit is a better structural fit for recurring cash flow gaps, subject to the actual agreement.

Does unsecured business funding mean no personal guarantee?

No. An unsecured business loan can still require a personal guarantee, so review personal liability separately from collateral requirements.

Does 2M7 offer unsecured business loans?

2M7 offers merchant cash advances and working capital, not loans. Confirm security requirements and personal guarantee terms in the written offer rather than assuming the funding is unsecured.

Can a Canadian business with less-than-perfect credit apply for a merchant cash advance?

Yes, the stated customer profile for this merchant cash advance includes businesses with less-than-perfect credit. Eligibility also includes at least 3 months in operation and $15,000 or more in monthly revenue; approval is not assured.

Is a business line of credit better than a term loan?

A business line of credit is better suited to recurring timing gaps, while a term loan suits a defined expense. Compare the payment requirements and access conditions before choosing either structure.

Do merchant cash advance payments always change with sales?

No. Payment arrangements depend on the funding agreement, and flex payments under the merchant cash advance described here apply only to businesses processing daily card payments.

What should I ask before accepting unsecured business funding?

Ask about total repayment, payment frequency, personal guarantees, security provisions and early repayment terms. Make sure the written agreement answers each question before signing.

One last thing

Start with the payment calendar, not the approval message. Put every proposed funding payment beside payroll, supplier bills and expected customer receipts before accepting an offer. That exercise shows whether the funding solves a timing gap or adds another obligation at the wrong time.

Related guides

Read more