ClickCease

The Small Business Owner's Guide to Business Loans in Canada

The Small Business Owner's Guide to Business Loans in Canada

The Small Business Owner's Guide to Business Loans in Canada
13
Apr 2023
11
Aug 2026

There is a wide array of services available to businesses in Canada seeking to bolster their cash liquidity. This article will explore some of the most popular options, as well as their best use cases. These financial solutions typically include a combination of bank loans, government business grants, factoring, cash advances, payday loans, and microloans.

Businesses can utilize these financial options to optimize growth, gain liquidity, bridge emergency situations, or capitalize on opportunities.

Let's delve into our options:

1. Traditional bank loans

This is the most conventional form of financing that small businesses can utilize to obtain. Typically, these loans are secured by collateral, and may offer lower interest rates, making them an appealing choice for businesses with strong credit. However, small and medium-sized businesses adhering to conservatism and GAAP principles might have lower perceived financial strength, which can make obtaining traditional financing more challenging, especially if the bank relies on financial statements as part of its due diligence process. This can be particularly problematic for new startups and businesses without a significant financial track record. Furthermore, liquidity provided might be limited if a business is relatively new or experiencing volatility, even with collateral in place.

2. Factoring

Factoring enables businesses to sell their accounts receivable (invoices) to a third-party (a factoring company) at a discount. The factoring company then acts as the agent to collect payments from the invoice customer, providing the business with liquidity (cash) based on a certain percentage of the invoice amount. Factoring can significantly improve cash flow for small and medium-sized businesses by offering liquidity and quick access to funds. It is also helpful that the factoring company will be the one taking care of ensuring invoices are paid, freeing up valuable resources for small businesses.

3. Government business grants

The Canadian government provides an array of business grants designed to help small businesses flourish. These grants typically target specific industries or business activities, such as clean technology, innovation, workforce development, and international trade, among others. A considerable number of grants currently emphasize research, development, and exporting. The application process for these grants can be intricate, requiring well-prepared grant proposals that effectively communicate the business's objectives, anticipated outcomes, and potential impact. This process is often competitive, as numerous businesses vie for the limited funding available. Newer businesses or those without prior grant writing experience may find this process daunting, and may benefit from seeking professional grant writing assistance or collaborating with experienced partners in their industry. Despite the challenges, securing a government grant can be a game-changer for small businesses, providing essential funding without the burden of repayment, and fostering growth, innovation, and competitiveness in the marketplace.

4. Payday loans or Microloans

Payday loans and microloans are small, short-term loans that are typically utilized to address unexpected expenses or navigate temporary cash flow gaps. While these loans may not be suitable for long-term financing needs due to their relatively higher interest rates and fees, they play a vital role in providing financial support during emergencies. By offering quick access to funds, payday loans and microloans help businesses remain afloat and operational during challenging times, allowing them to successfully weather temporary cash flow issues that are anticipated to improve in the near future. This targeted financial assistance can be a lifeline for businesses, enabling them to maintain stability and continue serving their customers as they work towards recovery and growth.

5. Merchant Cash Advance

A cash advance, particularly in the form of a Merchant Cash Advance (MCA), is an innovative financing solution that provides businesses with a lump sum of cash in exchange for a percentage of their future sales (typically credit card sales). Cash advances and MCAs can be exceptional financing options for businesses that need funds swiftly or require increased liquidity to seize opportunities that demand prompt. One of the key advantages of this financing option is its speed and flexibility. Cash advances can be processed more quickly than traditional loans, often within a matter of days, allowing businesses to address their financial needs without delay. Additionally, repayment terms are tailored to the business's sales volume, making it a more manageable solution for businesses with fluctuating revenues. MCAs are particularly valuable for new businesses and small enterprises that may face challenges in obtaining traditional bank loans due to a lack of financial history, inadequate financial book strength, or a dearth of collateral. By offering an alternative financing avenue, cash advances empower these businesses to overcome financial barriers and pursue their growth objectives. Ultimately, the various financing options available to Canadian businesses each have their own strengths and specific use cases. Traditional bank loans can be attractive for businesses with strong credit, while CEBA loans offer interest-free financing for those affected by the COVID-19 pandemic. Factoring provides immediate liquidity to businesses with outstanding invoices, and government grants can support targeted industries and activities. Payday loans or microloans can assist in managing short-term cash flow gaps. And cash advances offer rapid access to funds for businesses lacking financial history or collateral. The choice of financing option will depend on the unique needs and circumstances of each business. By understanding the advantages and limitations of each option, businesses can make informed decisions about the most suitable financing solution to support their growth, liquidity, and success.

Related articles

April 28, 2026
September 30, 2026

How To Get A Business Loan With a Bad Credit Score?

As a small business owner, when you go to a bank for a business loan, instead of looking at the performance of your business, the bank will check your personal credit score first. This means, even if your business is performing well and profitably, a fair credit score of 600-650 could prevent you from getting a small business loan. A credit score of under 600 portrays you as a high-risk borrower and will make it nearly impossible to borrow even a small loan. A low credit score stops business loans being disbursed to profitable and stable businesses. Bad credit history will follow you and your business for years. For example, you may have owned a successful business for a few years and now you are looking for funds to expand into another city or purchase more equipment, but when you visit the bank, the loan officer turns you away. Why? The answer is easy – his decision is based on your poor personal credit history.

Credit scores

There is no standard scale that defines your credit score. That evaluation varies from a credit agency to a credit agency as they set their own criteria. A credit report from Equifax may give a person one number, while a credit report from another institution will very likely suggest a higher or lower credit score for the same person. Credit scores in Canada are officially assessed by two entities: Equifax and TransUnion.

  • The higher the credit score, the safer it is to lend to you
  • Credit scores typically range from 300 to 900

Credit score brackets:

  1. 800-900 – Highest bracket; excellent credit history
  2. 700-799 – Very good credit history; lowest interest rates available
  3. 650-699 – the Lowest score that can receive standard loans
  4. 600-649 – Fair score; higher interest rates applicable
  5. 300-599 – Low scores; less likely to receive business loans

Therefore, if you have a credit score of 649 or lower, it will dramatically reduce the chance of your business loan being approved. Since major banks first look to the business owner’s personal credit score, even exceptional business performance may not make you eligible for loans, or high-interest rates may apply to you.

What happens if you have a low credit score?

If the borrower has a bad credit score, other than a higher likelihood of being refused a loan by the major financial institutions, there are a few other ramifications:

  • Higher interest rates on loans and lines of credit
  • Difficulty finding business premises
  • Security deposits required by utility companies
  • Higher insurance premiums for business assets

Private lenders help small businesses with bad credit history get loans

Fortunately, there are ways of getting business loans for your company even if you - the borrower - have bad credit. To get small business loans with bad credit history, private lenders are one of the best options. These are more local lenders, better tuned to market conditions, who offer more flexible loan options. There are many private lenders that can provide small business loans. Bad credit history or credit score will make little or no difference to the loan, depending on the type of loan you opt for. Moreover, the application process is much easier and repayments are more flexible. It is possible that a private lender will ask you to open a business bank account with them before they provide you with funding.

‍

‍

How to get a business loan with a bad credit score?

Merchant cash advance (MCA) lenders provide cash advances, customize private terms and business equity line of credit to small business owners. This would be the best way to get a business loan with no credit assessment, and beneficial repayment terms if you happen to have a bad credit history. Instead of checking your personal credit score, a merchant cash advance provider assesses your business’ performance and monthly credit card sales.The MCA lender will give you an upfront sum of cash in exchange for a percentage of the business’s daily credit card income.  The MCA lender will tie into the credit card processor directly to settle credit card payments so the business owner does not have to worry about missing the payments or dealing with administrative processes. There are many pros and cons of having MCA but regardless of that, it is still considered as the best way to get business fundings.A private term loan gives you the same perks as a small business loan from a major lending institution. However, the private lender does not give the same weight to your bad credit when deciding on the small business loan. Instead, the lender mitigates the risk with fixed daily repayment terms.A business equity line of credit is much less reliant on the credit history of the business owner. Therefore, if you have a bad credit history and require financing for your business, you can use your equity in the business as collateral. A business equity line of credit helps businesses resolve their cash flow issues, though it does require putting up a part of your ownership as collateral.

If the funding is for equipment specifically, our guide to bad credit equipment financing in Canada compares leasing, vendor financing, government-backed programs and merchant cash advances, including how their costs differ.

Start-up bad credit business loans

For entrepreneurs with bad credit seeking business loans for their start-up, private lenders and alternative lending are the best options. Where small business loan applications at major institutions have a less than 25% chance of approval, merchant cash advance (MCA) approvals stand at over 75%! This is because MCAs do not evaluate the business owner’s personal credit score, and only take into account business performance. Besides that, MCAs can be approved within 4-6 hours.Government loans and grants are also great options. Both have flexible repayment terms and offer additional business support to small entities. However, some of the government loans may require a good credit history and may have strict eligibility criteria.

Using business loans to rebuild your credit

Apart from using funds to expand their business, business loans can help borrowers improve their personal credit scores. Once you opt for an equity line of credit or a private term loan, make sure to pay on time and your credit score will improve over time. As a result, the better your credit score is, the lower your interest rates will be and you will have a greater chance to access financial lending markets.Borrowing is an inherent part of any business regardless of its size and the industry it operates in. Major financial institutions and private lenders usually lend to businesses with exceptional credit histories opposed to those with a bad one. Don’t let your bad credit history stop your business from getting the financing it needs. Options such as a merchant cash advance (MCA) will provide you with the required funding, as well as improve your credit card history in general. If you think it might be a good solution for you, do not hesitate to get in touch with us.

Read more
April 4, 2022
September 27, 2026

Merchant Cash Advance vs. Cheques Factoring

Managing a small business is challenging. One of the common challenges for business owners is financing. Your company might not have a lengthy credit history or collateral to apply for a bank loan. Whether you want to grow your business or cover unforeseen expenses, you have come across other financing options. Merchant cash advance and cheques factoring are some of the available options for small businesses.

What Is Merchant Cash Advance?

A merchant cash advance is an alternative financing option for small businesses. You can take the funds upfront and pay them off with a percentage of future sales. The MCA is an ideal solution for businesses that need fast funding and might not be eligible to take a bank loan. The availability of funds is another excellent advantage. If your business needs the funds fast to proceed with the operations, the cash advance will be approved within a day or two.

PROS

Fast access to funds

When timing is crucial and you can't go through the lengthy bank approval process, the MCA is your solution. Small businesses can get funds within a day or two from submission. Unlike the traditional bank process, the financial institutions that issue MCAs don't do rigorous checks. They will check the business's past sales to determine whether they qualify for a cash advance.

Ideal for businesses that work with cash and credit cards

Retail and restaurant businesses rely on a high volume of credit card sales, making them ideal for obtaining MCA. If your business depends on cash or credit cards, a cash advance is the ideal financing method. This opportunity is perfect for the ones that don't rely on invoices. Instead, they take a percentage of the credit card sales to repay the loan.

CONS

High-interest rates

Merchant cash advance comes with higher interest rates than traditional bank loans. The convenience of having the funds fast will cost more. However, the price is worth paying when you need urgent funds to proceed with the business operations.

What Is Cheques Factoring?

A post-dated cheque is a cheque that can be cashed on the indicated date on the document's face. It is a form of advance payment and can be cashed on a specific date. According to Canadian laws, a cheque can't be cleared before this date. If you still need cash to keep your business's liquidity, you can sell the cheque to a factoring company.

PROS

Fast approval

Depending on the date indicated on the check face, you might have to wait long to receive the payment. If you need to meet your business needs urgently, factoring your cheques will provide you with funds quickly. They will pay off a particular value of the face value while keeping a specific percentage as a fee.

No credit score checks

When applying for a traditional bank loan, they will do a rigorous check on your financial history. When your small business is relatively new and doesn't have a credit history, you might be restricted from obtaining such loans. Your ability for cheque factoring isn't assessed with credit history, and you aren't required to disclose collateral. This is very important, as you don't need to put your property or equipment at risk. The factoring company will check the check for authenticity.

Not deal with cheques

Having to deal with cheques is a tedious job. Passing this responsibility to a third party means less time spent sorting out cheques so that you can focus on the more important aspects of your business.

CONS

Higher cost

The factoring company will charge fees to provide you with the cash in advance. They will usually pay 80% of the amount indicated on the face. However, the high cost might pay off if you need money urgently.  

Requirements

Cheques factoring companies might have specific requirements for cashing out your document. For example, the check drawer should be a reputable entity. Also, the factoring company might have particular requirements on the cheque's active time.

Merchant Cash Advance vs. Cheques Factoring

For cheques factoring, you will pay a fee to the factoring company expressed as a percentage of the total amount. On the other hand, you will pay off your MCA as a percentage of your future sales. When choosing the suitable financing method for your company, select the one that is a better fit for your needs. We at 2M7 are dedicated to providing the needed funds to enhance your business's liquidity without restrictions on how to use them. Get in touch with us, and we will answer your specific needs! For a broader look at how merchant cash advances can support business growth, read merchant cash advance benefits for business growth.

Read more
October 14, 2026
October 14, 2026

Best small business loans in Canada 2026

Best overall for a defined investment: a bank term loan. Best for recurring cash-flow gaps: a business line of credit. Best for government-backed borrowing: the Canada Small Business Financing Program. This 2M7 guide to small business loans Canada compares six financing routes for 2026 and explains which repayment structure fits your business.

TL;DR

  • The 2M7 small business loans Canada guide recommends matching business financing to the expense and repayment source.
  • Bank term loans suit defined investments; business lines of credit suit recurring cash-flow gaps.
  • The Canada Small Business Financing Program shares lender risk; it does not guarantee approval.
  • Invoice financing suits unpaid business invoices; equipment financing ties borrowing to a specific asset.

Why this matters

The best business financing matches the expense to the repayment source. A loan for equipment and a facility for payroll between customer payments solve different problems. Choosing by the amount offered ignores that distinction.

For your 2026 shortlist, compare what happens after the money arrives: when payments begin, what secures the borrowing, and which cash receipts will repay it. A facility that funds the purchase but strains ordinary operations is the wrong fit.

Use 2M7 as your starting point for this comparison, then assess each financing proposal against the same criteria. The ranking below separates financing structures rather than pretending one lender is best for every Canadian business.

What makes the best small business loans in Canada

  • Purpose fit: Match the financing to equipment, expansion, working capital, or an unpaid invoice. Confirm that the proposed use is eligible.
  • Repayment fit: Compare payment dates with customer receipts. Scheduled instalments and revolving borrowing serve different needs.
  • Total repayment: Request the complete repayment obligation, including interest and applicable fees. A headline rate does not describe the whole agreement.
  • Security exposure: Identify collateral, guarantees, and obligations that survive a business closure. Read the agreement rather than relying on a summary.
  • Eligibility fit: Check revenue, operating history, documentation, and program restrictions before preparing an application.
  • Flexibility: Examine redraw access, early repayment terms, renewal conditions, and any restrictions on how funds are used.

Canadian business financing at a glance

Bank term loan

  • Best for: A defined investment with predictable repayments
  • Standout feature: Scheduled repayment of a lump-sum advance
  • Key limitation: Payments remain due when sales weaken

Business line of credit

  • Best for: Recurring working-capital gaps
  • Standout feature: Borrowing and repayment within an approved limit
  • Key limitation: Access depends on the facility's continuing terms

Canada Small Business Financing Program

  • Best for: Eligible spending under a government-backed program
  • Standout feature: Government shares lender risk
  • Key limitation: The participating lender still decides approval

BDC business financing

  • Best for: Development projects requiring a dedicated financing discussion
  • Standout feature: Canada's business development bank
  • Key limitation: Product eligibility and underwriting still apply

Invoice financing

  • Best for: Cash tied up in unpaid business invoices
  • Standout feature: Financing linked to receivables
  • Key limitation: Customer disputes and invoice eligibility matter

Equipment financing

  • Best for: A specific equipment purchase
  • Standout feature: Financing tied to the financed asset
  • Key limitation: It does not solve unrelated operating gaps

1. Bank term loan: best for a defined business investment

A bank term loan advances a lump sum that you repay under an agreed schedule. It fits a project with a clear scope and a repayment source you can explain, such as an expansion supported by existing operating cash flow.

Bank term loan pros:

  • Scheduled payments support cash-flow planning.
  • A defined advance fits a clearly budgeted project.
  • Repayment reduces the outstanding principal over the term.

Bank term loan cons:

  • Payments remain due even when revenue falls.
  • Collateral or personal guarantees can expose assets beyond the project.

Best for: An established business funding a defined investment rather than repeatedly covering operating shortfalls.

For a 2026 application, connect the project budget to a cash-flow forecast. Separate expected project income from cash your business already generates; the lender needs a repayment case, not just an attractive expansion idea.

Ask whether early repayment changes your obligations and whether the agreement restricts additional borrowing. Those details matter if you expect to refinance, sell an asset, or repay ahead of schedule.

Verdict — Buy: Choose a bank term loan when the investment is defined and scheduled repayments fit your operating cash flow.

2. Business line of credit: best for recurring cash-flow gaps

A business line of credit lets you borrow, repay, and borrow again within an approved limit, subject to its terms. It suits timing differences between expenses and customer receipts rather than a permanent operating loss.

Business line of credit pros:

  • Revolving access fits recurring working-capital needs.
  • You can draw funds as expenses arise.
  • Customer receipts can reduce the outstanding balance.

Business line of credit cons:

  • Renewal and access depend on the agreement and lender review.
  • A balance that never declines can conceal a structural cash-flow problem.

Best for: A business with recurring payment gaps and identifiable incoming receipts.

Map the gap before applying: when do wages, suppliers, and taxes fall due, and when do customers pay? The borrowing need is the difference between those dates, not simply the largest limit available.

Check whether the facility is repayable on demand and what reporting the lender requires. Do not assume a revolving facility provides permanent access under unchanged conditions.

Verdict — Buy: Choose a business line of credit for temporary, recurring gaps that customer receipts will clear.

3. Canada Small Business Financing Program: best for eligible borrowing

The Canada Small Business Financing Program, administered by Innovation, Science and Economic Development Canada, shares lending risk with participating financial institutions. You apply through a participating lender, which assesses the application and makes the lending decision.

For your 2026 comparison, the program's published limits include $1 million in term loans and $150,000 in lines of credit per eligible borrower. Its eligibility framework covers qualifying Canadian small businesses with gross annual revenue of $10 million or less; farming businesses are excluded and have a separate federal financing program.

Canada Small Business Financing Program pros:

  • Government risk-sharing supports participating lenders' eligible lending.
  • The program covers specified business financing purposes.
  • Published rules give you an eligibility framework to check before applying.

Canada Small Business Financing Program cons:

  • Government backing does not guarantee approval.
  • Eligible-use rules and category sublimits restrict how borrowing can be allocated.

Best for: A qualifying business whose planned spending fits the program's rules.

The overall term-loan limit is not a spending allowance for every expense category. Ask the lender to identify the applicable sublimits, eligible costs, documentation, and security requirements for your project.

Treat the program as a route to discuss with a lender, not as a government grant. Your business remains responsible for repayment under the financing agreement.

Verdict — Buy: Consider the Canada Small Business Financing Program when both your business and intended spending meet its eligibility rules.

4. BDC business financing: best for a development-focused discussion

BDC is Canada's business development bank and offers business financing. It belongs on your shortlist when you need to discuss a development project and compare the available financing structure with conventional bank borrowing.

BDC business financing pros:

  • Its mandate focuses on Canadian businesses.
  • You can discuss financing against a specific development objective.
  • A proposal provides another structure to compare with other lenders.

BDC business financing cons:

  • Eligibility and approval depend on the financing product and application.
  • A development mandate does not remove repayment obligations or underwriting.

Best for: A business preparing a defined development project and seeking another financing proposal to evaluate.

Describe the project before asking which product fits. Your plan should distinguish the purchase or expansion itself from the working capital needed to operate during implementation.

For a 2026 comparison, assess the actual BDC proposal rather than assuming public ownership makes it the default choice. Compare repayment timing, security, permitted uses, and early repayment terms with your other offers.

Verdict — Hold: Keep BDC on the shortlist until a specific proposal demonstrates a better fit for your project.

5. Invoice financing: best for unpaid business invoices

Invoice financing converts eligible receivables into access to funds before customers pay. Structures differ: a lender can advance funds against invoices, while factoring involves selling receivables under an agreement.

Invoice financing pros:

  • Funding is linked to invoices already issued.
  • It addresses the gap between invoicing and collection.
  • Receivables provide a defined transaction to assess.

Invoice financing cons:

  • Disputed or ineligible invoices can limit access.
  • Collection arrangements and responsibility for non-payment vary by contract.

Best for: A business with eligible unpaid commercial invoices and a collection-timing problem.

Read who contacts the customer, where payments go, and who bears the loss if the customer does not pay. Recourse and non-recourse arrangements are not interchangeable, and exclusions still matter.

Invoice financing does not fix a weak margin or create a sale that has not happened. If your cash shortage exists before you deliver and invoice, compare another structure instead.

Verdict — Buy: Choose invoice financing when unpaid eligible invoices, rather than missing sales, explain the cash gap.

6. Equipment financing: best for a specific asset purchase

Equipment financing ties borrowing to a particular asset, which commonly serves as security. Compare an equipment loan with a lease separately because ownership, end-of-term options, and contract obligations differ.

Equipment financing pros:

  • The financing purpose is clearly defined.
  • Repayment can be assessed against the asset's business use.
  • Asset-linked financing keeps the equipment decision separate from general working capital.

Equipment financing cons:

  • The financed asset can be at risk if you default.
  • Contract restrictions can complicate selling or replacing the equipment.

Best for: A business buying equipment with a clear operating purpose and a repayment plan.

Account for installation, training, maintenance, and the period before the equipment contributes to operations. Financing the purchase does not automatically fund those related expenses.

Ask what happens if the asset becomes unsuitable before the agreement ends. Replacement flexibility matters when your capacity needs or production methods change.

Verdict — Buy: Choose equipment financing for the asset itself, not as a substitute for an operating cash buffer.

How this ranking works

The 2M7 small business loans Canada ranking prioritizes purpose, repayment fit, security, eligibility, and flexibility. Each option owns a different use case; the order is not a lender service rating or an approval forecast.

A bank term loan is the default for a defined investment. The other routes become stronger choices when your financing need is revolving, program-eligible, development-focused, invoice-linked, or asset-specific.

Which small business financing should you choose?

Choose the structure before choosing the provider. For your 2026 decision, write down these four items and use them to compare proposals:

  • Funding purpose: State exactly what the money will pay for.
  • Repayment source: Identify the receipts that will repay the borrowing.
  • Security exposure: List the assets and guarantees required.
  • Contract terms: Check payment dates, restrictions, renewal, and early repayment.
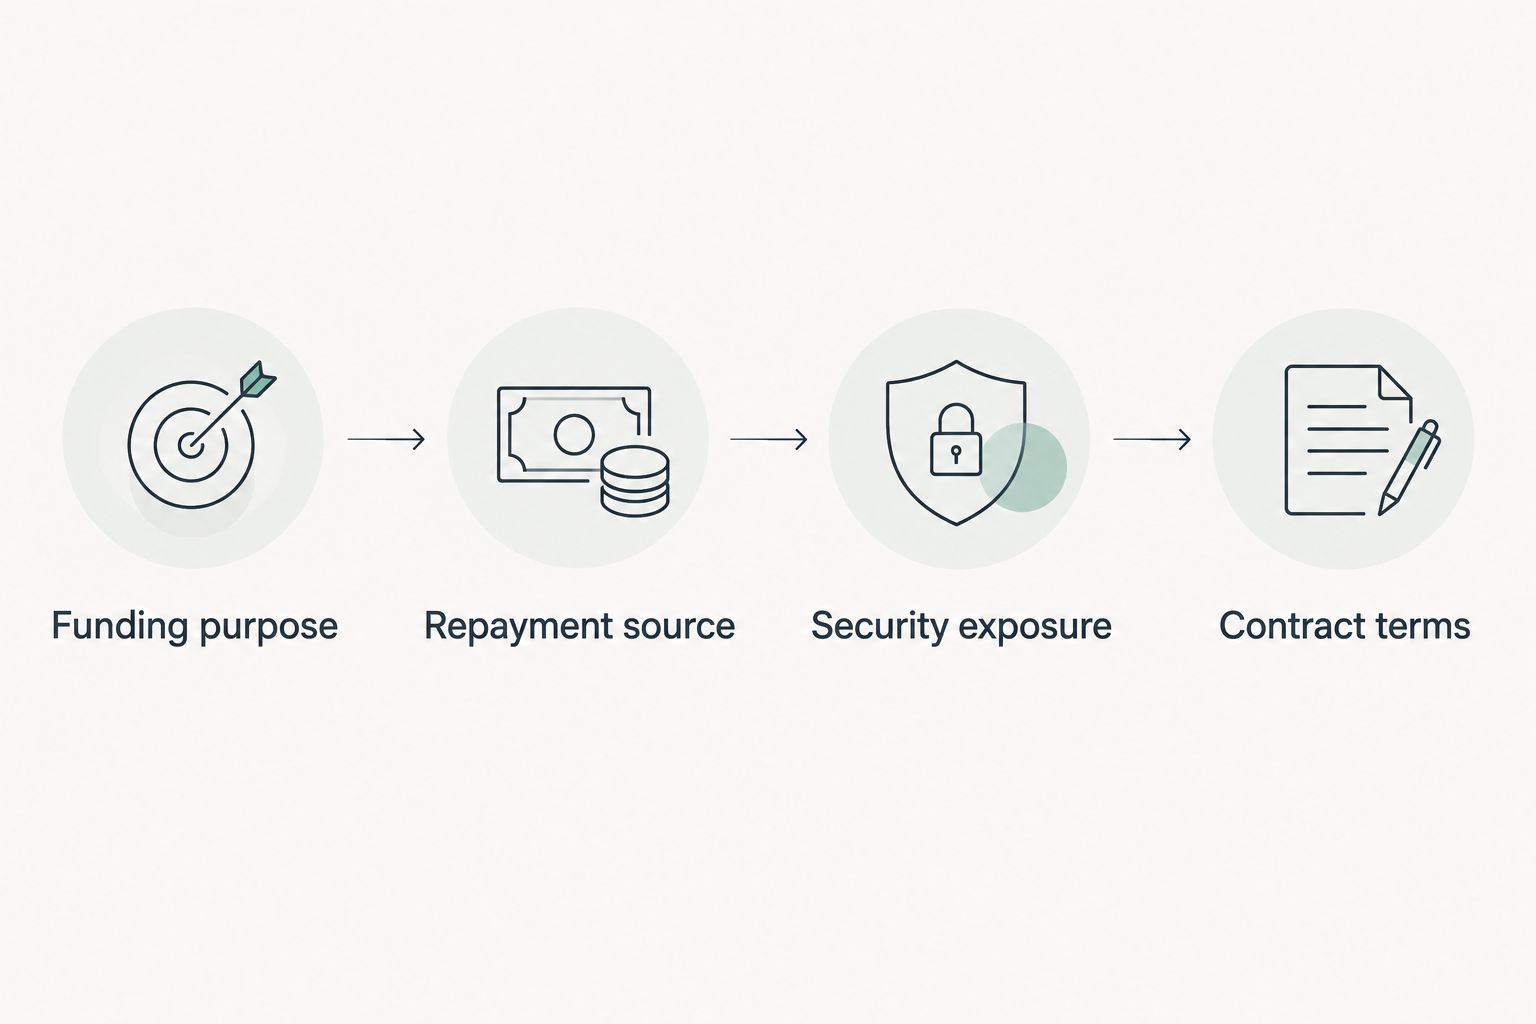
Four checks for business financing: purpose, repayment source, security exposure and contract terms.

Choose the financing structure before comparing providers.

If you remain undecided, start with a bank term loan for a defined investment or a line of credit for a recurring timing gap. Then compare the alternatives only where their distinct use case matches your business.

Do not accept more borrowing simply because it is offered. Select the amount supported by your documented need and a repayment plan that leaves ordinary operations funded.

FAQ

What's the best small business loan in Canada in 2026?

A bank term loan is the default choice for a defined investment with predictable repayments. A business line of credit fits recurring cash-flow gaps better, while invoice financing and equipment financing address narrower needs.

Is the Canada Small Business Financing Program a government loan?

The Canada Small Business Financing Program provides government risk-sharing for eligible loans made by participating financial institutions. You apply through a participating lender, and that lender decides whether to approve the application.

How much can I borrow through the Canada Small Business Financing Program?

The program's published limits include $1 million in term loans and $150,000 in lines of credit per eligible borrower. Category sublimits and eligible-use rules apply, so the overall limit is not available for every type of expense.

Is a business line of credit better than a term loan?

A business line of credit is better suited to recurring timing gaps, while a term loan fits a defined investment. Compare renewal conditions and repayment obligations before deciding which structure matches your receipts.

Is BDC financing automatically easier to get than a bank loan?

BDC financing still requires product eligibility and application assessment. Compare a specific proposal rather than assuming that BDC's public mandate guarantees approval.

Can invoice financing help before I make a sale?

Invoice financing relies on eligible receivables, so it does not fund a sale that has not produced an eligible invoice. It addresses the timing gap between invoicing and collection.

What should I compare when using the 2M7 business financing guide?

Compare funding purpose, repayment source, security exposure, and contract terms. Those checks distinguish an appropriate financing structure from an offer that merely provides the requested amount.

One last thing

Ask what happens when your repayment source arrives late. A delayed customer payment tests a financing agreement more clearly than an optimistic forecast.

Before signing, trace that delay through payment obligations, available cash, collateral, and guarantees. If the agreement forces another borrowing decision just to meet the first obligation, revisit the structure—not just the lender.

Read more