ClickCease

The Small Business Owner's Guide to Business Loans in Canada

The Small Business Owner's Guide to Business Loans in Canada

The Small Business Owner's Guide to Business Loans in Canada
13
Apr 2023
11
Aug 2026

There is a wide array of services available to businesses in Canada seeking to bolster their cash liquidity. This article will explore some of the most popular options, as well as their best use cases. These financial solutions typically include a combination of bank loans, government business grants, factoring, cash advances, payday loans, and microloans.

Businesses can utilize these financial options to optimize growth, gain liquidity, bridge emergency situations, or capitalize on opportunities.

Let's delve into our options:

1. Traditional bank loans

This is the most conventional form of financing that small businesses can utilize to obtain. Typically, these loans are secured by collateral, and may offer lower interest rates, making them an appealing choice for businesses with strong credit. However, small and medium-sized businesses adhering to conservatism and GAAP principles might have lower perceived financial strength, which can make obtaining traditional financing more challenging, especially if the bank relies on financial statements as part of its due diligence process. This can be particularly problematic for new startups and businesses without a significant financial track record. Furthermore, liquidity provided might be limited if a business is relatively new or experiencing volatility, even with collateral in place.

2. Factoring

Factoring enables businesses to sell their accounts receivable (invoices) to a third-party (a factoring company) at a discount. The factoring company then acts as the agent to collect payments from the invoice customer, providing the business with liquidity (cash) based on a certain percentage of the invoice amount. Factoring can significantly improve cash flow for small and medium-sized businesses by offering liquidity and quick access to funds. It is also helpful that the factoring company will be the one taking care of ensuring invoices are paid, freeing up valuable resources for small businesses.

3. Government business grants

The Canadian government provides an array of business grants designed to help small businesses flourish. These grants typically target specific industries or business activities, such as clean technology, innovation, workforce development, and international trade, among others. A considerable number of grants currently emphasize research, development, and exporting. The application process for these grants can be intricate, requiring well-prepared grant proposals that effectively communicate the business's objectives, anticipated outcomes, and potential impact. This process is often competitive, as numerous businesses vie for the limited funding available. Newer businesses or those without prior grant writing experience may find this process daunting, and may benefit from seeking professional grant writing assistance or collaborating with experienced partners in their industry. Despite the challenges, securing a government grant can be a game-changer for small businesses, providing essential funding without the burden of repayment, and fostering growth, innovation, and competitiveness in the marketplace.

4. Payday loans or Microloans

Payday loans and microloans are small, short-term loans that are typically utilized to address unexpected expenses or navigate temporary cash flow gaps. While these loans may not be suitable for long-term financing needs due to their relatively higher interest rates and fees, they play a vital role in providing financial support during emergencies. By offering quick access to funds, payday loans and microloans help businesses remain afloat and operational during challenging times, allowing them to successfully weather temporary cash flow issues that are anticipated to improve in the near future. This targeted financial assistance can be a lifeline for businesses, enabling them to maintain stability and continue serving their customers as they work towards recovery and growth.

5. Merchant Cash Advance

A cash advance, particularly in the form of a Merchant Cash Advance (MCA), is an innovative financing solution that provides businesses with a lump sum of cash in exchange for a percentage of their future sales (typically credit card sales). Cash advances and MCAs can be exceptional financing options for businesses that need funds swiftly or require increased liquidity to seize opportunities that demand prompt. One of the key advantages of this financing option is its speed and flexibility. Cash advances can be processed more quickly than traditional loans, often within a matter of days, allowing businesses to address their financial needs without delay. Additionally, repayment terms are tailored to the business's sales volume, making it a more manageable solution for businesses with fluctuating revenues. MCAs are particularly valuable for new businesses and small enterprises that may face challenges in obtaining traditional bank loans due to a lack of financial history, inadequate financial book strength, or a dearth of collateral. By offering an alternative financing avenue, cash advances empower these businesses to overcome financial barriers and pursue their growth objectives. Ultimately, the various financing options available to Canadian businesses each have their own strengths and specific use cases. Traditional bank loans can be attractive for businesses with strong credit, while CEBA loans offer interest-free financing for those affected by the COVID-19 pandemic. Factoring provides immediate liquidity to businesses with outstanding invoices, and government grants can support targeted industries and activities. Payday loans or microloans can assist in managing short-term cash flow gaps. And cash advances offer rapid access to funds for businesses lacking financial history or collateral. The choice of financing option will depend on the unique needs and circumstances of each business. By understanding the advantages and limitations of each option, businesses can make informed decisions about the most suitable financing solution to support their growth, liquidity, and success.

Related articles

October 16, 2026
October 16, 2026

Best merchant cash advance options for small businesses 2026

Best for a direct-funder relationship: 2M7. Best for card-sales-linked payments: a merchant cash advance with that structure explicitly written into the agreement. Best for an intermediary-led search: a broker-arranged advance. This 2026 guide compares those routes and explains when a business line of credit is the better alternative.

TL;DR

  • For merchant cash advance options Canada businesses can compare, 2M7 fits owners seeking a direct funder.
  • Card-sales-linked payments suit daily card-processing businesses; confirm exactly how payments respond to sales.
  • A broker arranges funding rather than providing it directly; identify the actual funder before signing.
  • A business line of credit is an alternative for recurring borrowing, not a merchant cash advance.

Why this matters

A merchant cash advance provides business funding against future sales, with collection terms set out in an agreement. It differs from a conventional business loan. Your decision should centre on the amount your business receives, the total contractual obligation and how collections affect operating cash flow.

The options below are not interchangeable products. Direct funding describes who provides the capital. Card-linked payments describe how collections work. A broker describes an intermediary. One agreement can combine these features.

Choose the payment structure your business can sustain, then choose the funding relationship. A familiar label does not tell you whether the agreement fits your payroll, supplier bills or sales cycle.

What makes the best merchant cash advance option?

Use these criteria to compare merchant cash advance options in Canada in 2026:

  • Funding relationship: Establish whether you are dealing with the funder or an intermediary. Know who approves the application and manages the account.
  • Eligibility fit: Check operating history, monthly revenue and any payment-processing requirements before applying.
  • Collection structure: Identify whether payments follow card sales or use another collection arrangement. Read the actual formula.
  • Total obligation: Compare the amount received with the complete amount payable. Ask for every contractual charge in writing.
  • Cash-flow fit: Test the collections against a slower sales period, not just your strongest month.
  • Contract clarity: Review early-payment conditions, security requirements and what happens when payments are missed.

Do not rank an offer by approval speed alone. Funding that arrives quickly still needs to leave enough operating cash for the work it is meant to support.

Merchant cash advance options at a glance

This 2026 comparison ranks decision routes, not competing branded products. The line of credit appears as a clearly marked alternative because recurring access to funds is a different need from a single advance.

2M7 direct-funded merchant cash advance

  • Best for: Owners seeking a direct funding relationship
  • Standout feature: Direct funder rather than a broker
  • Key limitation: Minimum operating-history and revenue requirements apply

Card-sales-linked merchant cash advance

  • Best for: Businesses processing daily card payments
  • Standout feature: Collections tied to card sales where the agreement specifies it
  • Key limitation: Not a fit for businesses without qualifying card processing

Broker-arranged merchant cash advance

  • Best for: Owners wanting an intermediary to approach funders
  • Standout feature: A separate party manages the funding search
  • Key limitation: The broker is not the source of capital

Business line of credit

  • Best for: Businesses needing recurring draws and repayments
  • Standout feature: Reusable borrowing access, subject to the agreement
  • Key limitation: A loan alternative to an advance, with its own underwriting requirements

1. 2M7: best merchant cash advance for direct-funder access

This Canadian direct funder provides merchant cash advances and working capital to small and mid-sized businesses. You deal with the funding provider rather than a broker. Funding uses include payroll, inventory, equipment and cash-flow gaps.

The stated eligibility baseline is at least 3 months in business and $15,000 in monthly revenue. Businesses with less-than-perfect credit are within its stated audience, but eligibility is not an approval decision.

Best for: An operating Canadian business that meets those thresholds and wants a direct relationship with its funder.

2M7 pros

  • Direct funding means there is no broker between your business and the capital provider.
  • The stated audience includes businesses with less-than-perfect credit.
  • One fixed cost of capital is shown before signing and does not change based on how long repayment takes.
  • Existing clients can text or call their funding representative directly.

2M7 cons

  • Businesses below the operating-history or monthly-revenue thresholds do not meet the stated baseline.
  • Flex payments are only for businesses that process daily card payments.
  • Meeting the baseline does not establish that the proposed collections fit your cash flow.

The published approval rate is 75%, not an individual promise. Assess the written offer on its own terms, including the collection arrangement and the cash your business retains after payments.

Verdict: Buy only after confirming that the written obligation and collection schedule fit your operating budget.

2. Card-sales-linked advances: best for daily card-processing businesses

A card-sales-linked merchant cash advance uses card receipts as the basis for collections where the agreement specifies that arrangement. This structure is relevant when your business processes daily card payments and wants collections connected to those receipts.

Do not assume every merchant cash advance works this way. The label alone does not establish the collection percentage, payment frequency or treatment of sales outside the card channel.

Best for: A business with daily card transactions that can verify the relationship between card sales and collections.

Card-sales-linked advance pros

  • The agreement can connect collections to the payment channel your business uses daily.
  • A clearly stated collection formula lets you model the effect of different card-sales levels.
  • Reviewing card receipts alongside collections helps you assess the operating cash left for other bills.

Card-sales-linked advance cons

  • Businesses without qualifying daily card processing need a different structure.
  • Card receipts alone do not show your full cash position, including supplier payments and payroll.
  • Sales-linked collections do not remove the contractual obligation or make the funding cost disappear.

Ask the funder to explain how refunds, chargebacks and processing changes affect collections. Get the answers in writing rather than relying on a general description of flexibility.

Verdict: Buy only when the agreement explicitly links collections to card sales and your cash-flow forecast supports it.

3. Broker-arranged advances: best for an intermediary-led search

A merchant cash advance broker helps arrange funding from another provider. The broker is an intermediary, not the business supplying the capital. That distinction matters when you need to understand who makes decisions and who handles the account after funding.

The value of this route depends on the actual search process. Ask which funders the broker approaches, how information is shared and how compensation works before submitting documents.

Best for: An owner who wants an intermediary to manage a funding search and is prepared to check the underlying funder independently.

Broker-arranged advance pros

  • An intermediary can coordinate the application process with the funders it works with.
  • The broker can help explain the offers it presents.
  • You can assess its proposed search process before authorising submissions.

Broker-arranged advance cons

  • A broker's presence does not establish that every relevant funding option has been considered.
  • You must distinguish the broker's responsibilities from the funder's contractual obligations.
  • Compensation and information-sharing arrangements need separate scrutiny.

Compare written agreements, not just the broker's summary. Identify the legal funding counterparty, the party collecting payments and the contact responsible for account questions.

Verdict: Hold until you understand the funder, the broker's role and every disclosed charge.

4. Business lines of credit: best alternative for recurring draws

A business line of credit is borrowing access that lets you draw funds up to an approved limit, subject to the agreement. Repayments can restore available borrowing capacity under its terms. It is not a merchant cash advance.

Include this alternative when your real need is repeated access to working capital rather than one defined funding amount. Compare the lender's underwriting, interest, charges and account conditions with the advance being considered.

Best for: A business that needs recurring draws and can satisfy the lender's requirements.

Business line of credit pros

  • You can draw funds as needed within the approved facility's terms.
  • Repayment can restore borrowing capacity rather than requiring a separate advance.
  • The structure supports a recurring funding need when the facility remains in place.

Business line of credit cons

  • Approval and account terms depend on the lender's underwriting requirements.
  • Interest, charges and security requirements need careful comparison.
  • Access remains subject to the agreement rather than being an unconditional reserve.

A line of credit is not automatically the right answer. Match its draw rules and repayment requirements to your actual collection cycle, especially when customer payments arrive after supplier bills fall due.

Verdict: Buy if recurring access is the need and the facility's terms fit; skip it as a substitute for fixing persistent operating losses.

How to compare written offers before signing

In 2026, use the same business forecast for every offer. Otherwise, you risk comparing one proposal against an optimistic month and another against a conservative month.

Define the need

Name the expense and the business outcome it supports. Payroll, inventory replenishment and equipment purchases have different cash-flow patterns. Separate the amount needed for that purpose from any additional amount offered.

Confirm eligibility

Check the stated revenue, operating-history and processing requirements. Explain your revenue sources accurately. A business paid mainly by invoices should not evaluate a daily-card-processing requirement as though those payment channels were identical.

Review collections

Write down when collections occur and what determines their size. Identify the business account or payment channel involved. Ask what the agreement requires if sales fall or a scheduled payment cannot be completed.

Test cash flow

Place the proposed collections beside payroll, rent, supplier commitments and existing obligations. Use your own slower-period records rather than an invented industry average. The useful result is the cash left to operate, not simply whether the collection can clear.

Read conditions

Review early payment, additional funding, missed payments, security and any personal obligations. Ask for unclear terms to be explained before signing. Keep the signed agreement and disclosures together for reference.
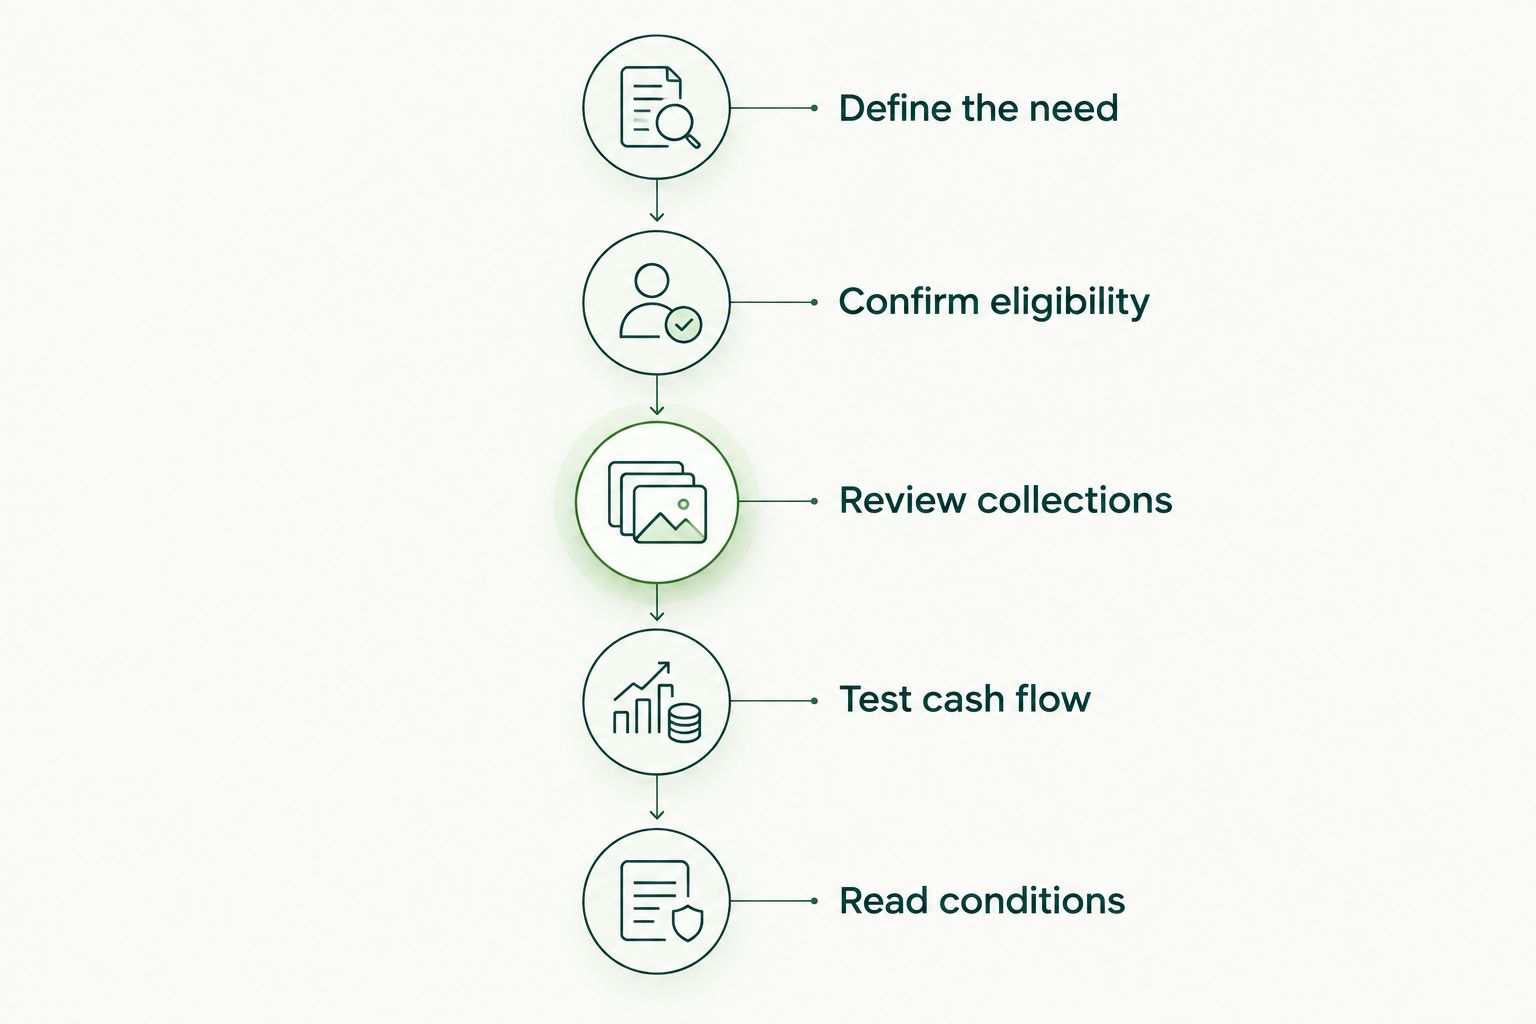
Five steps for checking a business funding offer before signing

Check operating cash flow before accepting the agreement.

The final comparison should make the trade-off visible: how much operating cash the funding adds now, what your business must pay under the agreement and what remains available for ordinary expenses.

How this ranking works

The 2026 ranking prioritises a clear funding relationship, eligibility fit, collection transparency and a distinct use case. It does not treat direct funding, broker involvement and card-linked collections as mutually exclusive products.

The first recommendation answers who you deal with. The second addresses payment structure. The third addresses how you search. The fourth tests whether a different borrowing structure better matches recurring needs.

Which merchant cash advance option should you choose?

2M7 is best for Canadian business owners seeking a direct-funded merchant cash advance without a broker. Start there if that relationship is your priority and you meet the stated operating-history and revenue thresholds.

If daily card receipts drive your cash flow, scrutinise the collection formula next. If you prefer an intermediary-led search, check the broker's role and the underlying funder separately. If you need repeated draws, compare a business line of credit before committing to an advance.

For a 2026 decision, choose the agreement your business can support during a slower period, not the largest amount offered. Discuss your funding options with a funding specialist and ask for the complete terms before deciding.

FAQ

What's the best merchant cash advance option in Canada?

The best option is the one whose eligibility requirements, collection structure and contractual obligation fit your business. Choose a direct funder for a direct funding relationship, and assess card-linked collections separately from who supplies the capital.

Is a merchant cash advance a business loan?

A merchant cash advance is not a conventional business loan. It provides business funding against future sales under an agreement, so compare its actual terms rather than treating it as interchangeable with a line of credit.

Does every merchant cash advance adjust payments when sales fall?

No, the merchant cash advance label does not establish how collections change with sales. Check the written formula and ask the funder to explain what happens during a slower period.

Is a direct funder better than a broker?

A direct funder suits owners who want to deal with the capital provider rather than an intermediary. A broker suits owners who want help arranging a funding search, but the underlying funder's agreement still needs independent review.

Can a business with less-than-perfect credit apply?

Less-than-perfect credit does not rule out every merchant cash advance option. Check each provider's stated eligibility requirements, and distinguish permission to apply from an actual approval decision.

What should I compare besides the funding amount?

Compare the complete contractual obligation, collection frequency, collection formula and early-payment conditions. Test those terms against payroll, suppliers and other existing commitments using your own cash-flow records.

When is a business line of credit a better alternative?

A business line of credit fits a recurring need for draws and repayments when your business meets the lender's requirements. It is a different borrowing structure, so compare underwriting, interest, charges and account conditions rather than assuming it works like an advance.

One last thing

A payment that changes with sales and a cost that changes over time are different features. Do not confuse them. Ask two separate questions: what determines each collection, and what determines the total contractual obligation?

That distinction makes a funding conversation more useful. You can evaluate flexibility without assuming it changes what the agreement requires your business to pay.

Related guides

Read more
October 19, 2026
October 19, 2026

Best equipment financing for trucking companies in Canada 2026

Best overall for truck ownership: an equipment loan. Best for planned replacement: an equipment lease. Best for recurring repair bills: a business line of credit. Best for equipment-related working capital: a merchant cash advance when its repayment terms fit your revenue. This 2026 guide compares equipment financing for trucking companies by purpose, ownership and cash flow, rather than treating every funding option as interchangeable.

TL;DR

  • Equipment financing for trucking companies starts with a choice: finance the vehicle or fund the business around it.
  • Equipment loans suit ownership; equipment leases suit businesses that prefer use over immediate ownership.
  • Business lines of credit suit recurring operating expenses, subject to approved terms and limits.
  • 2M7 provides merchant cash advances for Canadian businesses seeking equipment-related working capital, not conventional equipment loans.

Why this matters

A truck purchase and a repair-related cash flow gap are different funding problems. A vehicle can support your business for years, while a repair bill needs to be matched against the cash available after the truck returns to work.

Match the funding structure to the expense before comparing providers. Otherwise, you can end up using operating cash for a long-term asset or taking on a repayment schedule that leaves too little room for fuel, insurance and payroll.

2M7 is a Canadian direct funder, not a broker, offering merchant cash advances and working capital. That makes it relevant to equipment-related cash needs, but not interchangeable with a lender financing a specific truck.

What makes the best trucking equipment financing?

Use these criteria to compare your 2026 options before requesting an offer:

  • Funding purpose: Separate buying a truck from paying for repairs, equipment, payroll or a cash flow gap.
  • Ownership: Establish who owns the equipment during the agreement and what happens at the end.
  • Cash flow: Compare payment timing with actual collections, not just the dates you issue invoices.
  • Security: Identify the truck, other assets or guarantees covered by the agreement.
  • Total obligation: Review the complete repayment obligation, charges and end-of-term requirements in writing.
  • Eligibility: Check business history, revenue, credit and equipment requirements before preparing an application.

No option wins every category. A suitable purchase agreement can still be unsuitable for recurring expenses, and an accessible working capital offer can still put pressure on operating cash.

Trucking equipment financing at a glance

Equipment loan

  • Best for: Buying a truck you intend to keep
  • Standout feature: Financing tied to an equipment purchase
  • Key limitation: Security and repayment obligations require close review

Equipment lease

  • Best for: Using equipment with a planned replacement strategy
  • Standout feature: Contract defines equipment use and end-of-term choices
  • Key limitation: Ownership is not automatic

Business line of credit

  • Best for: Recurring repairs and operating expenses
  • Standout feature: Reusable borrowing capacity under the agreement
  • Key limitation: Approval, limits and renewal terms constrain access

Merchant cash advance

  • Best for: Equipment-related working capital supported by business revenue
  • Standout feature: Funding assessed against the operating business
  • Key limitation: It is not a substitute for reviewing truck-specific financing

These are financing structures, not a ranking of named lenders. Actual suitability depends on the written offer, your business finances and the equipment involved.

1. Equipment loan: best for long-term truck ownership

An equipment loan finances an equipment purchase through a lending agreement. For a trucking company buying a vehicle it intends to keep, it is the clearest starting point because the funding decision centres on the asset and the business's ability to repay.

Ask whether the lender accepts the truck's age, condition, seller and intended use. Do not assume an offer for one vehicle applies to another, even when both serve the same route.

Equipment loan pros:

  • Connects the financing request to a defined equipment purchase.
  • Supports an ownership-focused fleet plan.
  • Provides a repayment schedule you can assess against operating cash flow.

Equipment loan cons:

  • Security arrangements can restrict your ability to sell or refinance the truck.
  • Payments continue when the truck is idle or undergoing repairs, unless the agreement provides otherwise.

Best for: An established owner-operator or fleet buying equipment for continued use.

Before accepting an equipment loan in 2026, ask what happens if you sell the truck, repay early or need to replace it after a breakdown. Also confirm whether the agreement covers only the equipment or requires additional security.

Verdict: Buy through an equipment loan when ownership is the goal and the payment leaves room for maintenance and downtime.

2. Equipment lease: best for a planned replacement strategy

An equipment lease gives your business the right to use equipment under a contract. The agreement determines payments, responsibilities and what happens when the lease ends.

A lease belongs on your shortlist when access to the truck matters more than immediate ownership. It requires careful end-of-term planning, not just a comparison of periodic payments.

Equipment lease pros:

  • Separates the decision to use equipment from outright ownership.
  • Can support a defined equipment replacement plan.
  • Establishes contractual choices for the end of the lease.

Equipment lease cons:

  • Returning or purchasing the equipment depends on the specific agreement.
  • Usage, condition and early termination provisions can limit flexibility.

Best for: A trucking company with a clear replacement plan and predictable equipment requirements.

Request the full end-of-term wording before signing. Check for purchase obligations, return conditions and any restrictions that conflict with your intended operation. Do not assume maintenance, insurance or repairs are included simply because the vehicle is leased.

For a 2026 comparison, put the lease's total obligations beside the equipment loan's total obligations. A smaller periodic payment does not establish which agreement is better for your business.

Verdict: Buy into a lease only when its use restrictions and end-of-term terms fit your fleet plan.

3. Business line of credit: best for recurring repair expenses

A business line of credit lets you borrow within an approved limit under the lender's terms. Its main role in trucking is managing recurring operating expenses, rather than replacing a dedicated truck-purchase agreement.

Repairs, parts and maintenance do not always line up with customer collections. A credit line gives you a structure to assess those repeated cash needs without treating each expense as a separate equipment acquisition.

Business line of credit pros:

  • Provides reusable borrowing capacity under the agreement.
  • Supports different operating expenses rather than one named asset.
  • Lets you distinguish short-term cash needs from long-term equipment ownership.

Business line of credit cons:

  • Approved limits and renewal conditions can constrain your plans.
  • A continuously drawn balance can conceal an unresolved operating shortfall.

Best for: A trucking business with recurring expenses and a credible plan to restore available credit from collections.

Check whether the facility is secured, what reporting is required and how repayment works. Ask about the lender's rights to change or demand repayment of the facility; do not assume access remains unchanged indefinitely.

If your plan depends on keeping the line fully drawn, reassess the underlying cash flow. Reusable credit works best when your business can repay drawings, not simply move expenses into a growing balance.

Verdict: Hold off on using a line of credit for a truck purchase unless the written terms and repayment plan support that use.

4. Merchant cash advance: best for equipment-related working capital

A merchant cash advance provides business funding through an agreement distinct from a conventional equipment loan. Consider it when the need extends beyond acquiring a vehicle, such as equipment expenses alongside payroll, inventory or a cash flow gap.

2M7 is best suited to Canadian businesses seeking merchant cash advance working capital, rather than a conventional truck-purchase loan. It serves businesses operating for at least 3 months with $15,000 or more in monthly revenue, including businesses with less-than-perfect credit.

Merchant cash advance pros:

  • Addresses operating-business needs, including equipment-related expenses.
  • Offers an alternative structure to conventional equipment borrowing.
  • Provides a direct-funder option through 2M7, without a broker between the business and funder.

Merchant cash advance cons:

  • It is not an equipment loan and should not be compared as though the contracts are identical.
  • Repayment obligations still need to fit cash flow after essential operating expenses.

Best for: A revenue-generating Canadian business that meets the funder's requirements and needs working capital rather than asset-specific financing.

For 2M7 working capital, the cost structure is one fixed cost of capital shown before signing; it does not change based on how long repayment takes. Review the total obligation and repayment mechanism alongside your other written offers. Flex payments are only for businesses that process daily card payments, so do not assume that feature applies to a trucking operation paid through invoices.

Verdict: Buy into a merchant cash advance only when its business purpose and repayment terms fit your collections.

How to compare your written offers

Use the same sequence for every 2026 offer. Comparing unlike figures, such as a lease payment against an advance amount, does not tell you which agreement fits.

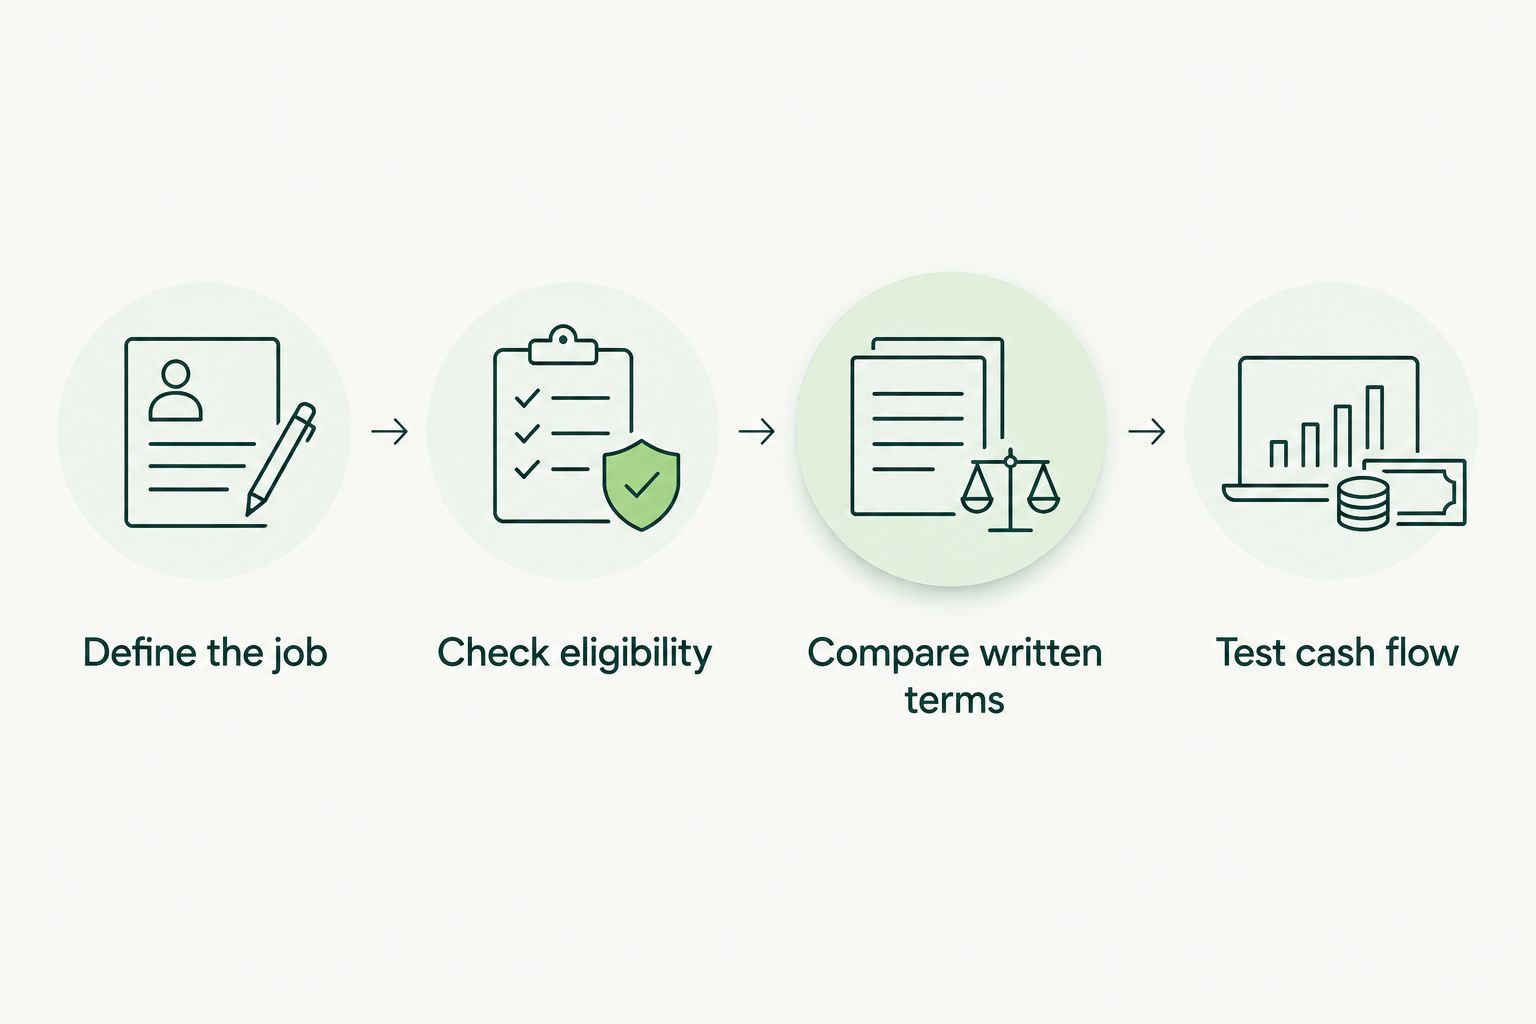
  1. Define the job: Write down whether you need a truck, a repair, replacement equipment or operating cash. Separate expenses that serve different purposes.
  2. Check eligibility: Confirm business, revenue, credit and equipment requirements before committing to an application process.
  3. Compare written terms: Record the amount provided, total obligation, payment timing, security, guarantees and exit conditions.
  4. Test cash flow: Place repayments beside expected collections and essential expenses. Check what happens during downtime or delayed customer payments.

A workable offer leaves your business able to operate the truck after obtaining the funding. Approval alone does not answer that question.

Four steps for comparing trucking equipment funding offers

Start with the expense and finish by testing the repayment against operating cash flow.

How the options are ranked

The ranking follows funding purpose, ownership, cash flow, security, total obligation and eligibility. Equipment loans lead for ownership; leases serve planned use and replacement; credit lines address recurring expenses; merchant cash advances address operating-business funding needs.

This is a purpose-based buying guide, not a claim that one provider offers the lowest cost or approves every trucking business. Compare the actual contracts before choosing.

Which equipment financing should you choose?

Start with an equipment loan if you are buying a truck you intend to keep. Compare a lease when your priority is equipment use with a defined replacement plan.

Choose a business line of credit for recurring expenses only when you can explain how collections will repay drawings. Consider a merchant cash advance when the need is working capital and the agreement fits your revenue.

For your 2026 decision, keep the truck purchase and the operating reserve separate on paper. You need to know both how you will acquire the equipment and how you will keep it earning.

Discuss your funding options

Speak with a funding specialist about working capital for your Canadian business.

Discuss funding options

FAQ

What's the best equipment financing for trucking companies in Canada?

An equipment loan is the strongest starting point when your goal is to buy and keep a truck. Compare a lease for planned equipment use, a credit line for recurring expenses and a merchant cash advance for working capital needs.

Is leasing a truck better than financing a purchase?

Leasing is better suited to a use-and-replacement plan, while an equipment loan suits an ownership plan. Compare total obligations, return conditions, security and early exit terms before choosing.

Can I use working capital for truck equipment?

Working capital can support equipment-related business expenses when the funding agreement permits the use. Separate the equipment expense from ongoing payroll, fuel and maintenance so you can assess the full cash requirement.

Does 2M7 offer conventional equipment loans?

2M7 provides merchant cash advances and working capital, not conventional equipment loans. It is a Canadian direct funder, not a broker.

Can a newer trucking business qualify for a merchant cash advance?

The stated eligibility baseline is at least 3 months in business and $15,000 or more in monthly revenue. Meeting that baseline does not establish approval or the terms of an offer.

What should I check before signing a trucking finance agreement?

Check the total obligation, payment timing, security, guarantees and early exit terms. For leases, also check equipment return conditions and any purchase requirements.

Do flexible payments apply if customers pay trucking invoices?

Do not assume flexible payments apply to invoice-based collections. The flex-payment feature described here is only for businesses that process daily card payments.

One last thing

The truck payment is not the truck's full cash requirement. Before signing, put fuel, insurance, maintenance, payroll and a downtime allowance beside the proposed repayment. An agreement that fits only while every invoice arrives on time does not leave your business room to handle disruption.

Related guides

Read more
April 13, 2023
August 11, 2026

The Small Business Owner's Guide to Business Loans in Canada

There is a wide array of services available to businesses in Canada seeking to bolster their cash liquidity. This article will explore some of the most popular options, as well as their best use cases. These financial solutions typically include a combination of bank loans, government business grants, factoring, cash advances, payday loans, and microloans.

Businesses can utilize these financial options to optimize growth, gain liquidity, bridge emergency situations, or capitalize on opportunities.

Let's delve into our options:

1. Traditional bank loans

This is the most conventional form of financing that small businesses can utilize to obtain. Typically, these loans are secured by collateral, and may offer lower interest rates, making them an appealing choice for businesses with strong credit. However, small and medium-sized businesses adhering to conservatism and GAAP principles might have lower perceived financial strength, which can make obtaining traditional financing more challenging, especially if the bank relies on financial statements as part of its due diligence process. This can be particularly problematic for new startups and businesses without a significant financial track record. Furthermore, liquidity provided might be limited if a business is relatively new or experiencing volatility, even with collateral in place.

2. Factoring

Factoring enables businesses to sell their accounts receivable (invoices) to a third-party (a factoring company) at a discount. The factoring company then acts as the agent to collect payments from the invoice customer, providing the business with liquidity (cash) based on a certain percentage of the invoice amount. Factoring can significantly improve cash flow for small and medium-sized businesses by offering liquidity and quick access to funds. It is also helpful that the factoring company will be the one taking care of ensuring invoices are paid, freeing up valuable resources for small businesses.

3. Government business grants

The Canadian government provides an array of business grants designed to help small businesses flourish. These grants typically target specific industries or business activities, such as clean technology, innovation, workforce development, and international trade, among others. A considerable number of grants currently emphasize research, development, and exporting. The application process for these grants can be intricate, requiring well-prepared grant proposals that effectively communicate the business's objectives, anticipated outcomes, and potential impact. This process is often competitive, as numerous businesses vie for the limited funding available. Newer businesses or those without prior grant writing experience may find this process daunting, and may benefit from seeking professional grant writing assistance or collaborating with experienced partners in their industry. Despite the challenges, securing a government grant can be a game-changer for small businesses, providing essential funding without the burden of repayment, and fostering growth, innovation, and competitiveness in the marketplace.

4. Payday loans or Microloans

Payday loans and microloans are small, short-term loans that are typically utilized to address unexpected expenses or navigate temporary cash flow gaps. While these loans may not be suitable for long-term financing needs due to their relatively higher interest rates and fees, they play a vital role in providing financial support during emergencies. By offering quick access to funds, payday loans and microloans help businesses remain afloat and operational during challenging times, allowing them to successfully weather temporary cash flow issues that are anticipated to improve in the near future. This targeted financial assistance can be a lifeline for businesses, enabling them to maintain stability and continue serving their customers as they work towards recovery and growth.

5. Merchant Cash Advance

A cash advance, particularly in the form of a Merchant Cash Advance (MCA), is an innovative financing solution that provides businesses with a lump sum of cash in exchange for a percentage of their future sales (typically credit card sales). Cash advances and MCAs can be exceptional financing options for businesses that need funds swiftly or require increased liquidity to seize opportunities that demand prompt. One of the key advantages of this financing option is its speed and flexibility. Cash advances can be processed more quickly than traditional loans, often within a matter of days, allowing businesses to address their financial needs without delay. Additionally, repayment terms are tailored to the business's sales volume, making it a more manageable solution for businesses with fluctuating revenues. MCAs are particularly valuable for new businesses and small enterprises that may face challenges in obtaining traditional bank loans due to a lack of financial history, inadequate financial book strength, or a dearth of collateral. By offering an alternative financing avenue, cash advances empower these businesses to overcome financial barriers and pursue their growth objectives. Ultimately, the various financing options available to Canadian businesses each have their own strengths and specific use cases. Traditional bank loans can be attractive for businesses with strong credit, while CEBA loans offer interest-free financing for those affected by the COVID-19 pandemic. Factoring provides immediate liquidity to businesses with outstanding invoices, and government grants can support targeted industries and activities. Payday loans or microloans can assist in managing short-term cash flow gaps. And cash advances offer rapid access to funds for businesses lacking financial history or collateral. The choice of financing option will depend on the unique needs and circumstances of each business. By understanding the advantages and limitations of each option, businesses can make informed decisions about the most suitable financing solution to support their growth, liquidity, and success.

Read more