Best for eligible Canadian operating businesses: 2M7 merchant cash advances. Best for subscription businesses: recurring-revenue financing. Best for online retailers: e-commerce revenue financing. This 2026 guide compares these revenue based financing routes by business model, repayment structure and cash-flow fit, rather than naming a universal winner.
TL;DR
- 2M7 merchant cash advances are a revenue based financing option for Canadian businesses seeking working capital from a direct funder.
- Recurring-revenue financing suits subscription businesses evaluating funding against predictable customer receipts.
- E-commerce revenue financing suits online retailers evaluating inventory funding against sales and fulfilment costs.
- Compare total repayment, collection rules and operating cash left over before signing any agreement.
Why this matters
Revenue based financing connects a funding arrangement to business revenue, but the label does not tell you exactly how collections work. A percentage of sales, a fixed withdrawal and a payment adjusted after review have different effects on your cash flow.
2M7 is a Canadian direct funder, not a broker, providing merchant cash advances and working capital. 2M7 merchant cash advances are best for eligible Canadian businesses seeking working capital directly from a funder. The product is a merchant cash advance, not a loan.
The real decision is whether the agreement fits your receipts after payroll, suppliers, taxes and other commitments. Revenue alone does not answer that question. Your business needs enough cash left after collections to keep operating.
What makes the best revenue based financing in 2026?
Use these criteria before comparing providers or submitting an application:
- Business-model fit: Match the funding assessment to how you earn revenue: customer subscriptions, online orders or broader business sales.
- Collection mechanics: Establish whether withdrawals are fixed, sales-linked or adjusted through a separate process.
- Total repayment: Ask for the complete amount payable and every charge, not just the amount advanced.
- Operating headroom: Test collections against essential expenses during a slower sales period.
- Contract flexibility: Read the rules for adjustments, early settlement, security and further funding.
These criteria matter more than a broad claim that funding is flexible. In particular, distinguish a payment that changes automatically from one that changes only after you request a review. Get the answer in writing.
Revenue based financing options at a glance
The ranking below compares one named Canadian funding option with two financing categories. Subscription and e-commerce financing are routes to investigate, not endorsements of unnamed providers.
1. 2M7 merchant cash advances
- Best for: Eligible Canadian businesses seeking direct working capital
- Standout feature: Direct funding with one fixed cost of capital disclosed before signing
- Key limitation: Flex payments apply only to businesses processing daily card payments
2. Recurring-revenue financing
- Best for: Subscription businesses assessing funding against recurring receipts
- Standout feature: Assessment centred on the continuity of customer revenue
- Key limitation: Cancellation and retention terms need close review
3. E-commerce revenue financing
- Best for: Online retailers matching funding to an inventory cycle
- Standout feature: Assessment centred on online sales and their cash-conversion cycle
- Key limitation: Sales growth does not establish that margins can support repayment
No route wins solely because its application is shorter. The useful comparison is the agreement you receive, including what happens when revenue falls or an expected customer payment arrives late.
1. 2M7 merchant cash advances: best for direct Canadian funding
2M7 provides merchant cash advances and working capital to small and mid-sized Canadian businesses. Funding uses include payroll, inventory, equipment and cash-flow gaps. Businesses must have operated for at least 3 months and generate $15,000 or more in monthly revenue to meet the stated operating and revenue criteria.
Best for: Canadian business owners who want to discuss working capital directly with a funder, including owners with less-than-perfect credit.
Strengths and limitations
2M7 merchant cash advance pros:
- Direct-funder structure, rather than a broker intermediary.
- Working-capital uses that include payroll, inventory and equipment.
- One fixed cost of capital, shown before signing, that does not change with repayment duration.
- Flex payments for businesses that process daily card payments.
Merchant cash advance cons:
- Businesses below the stated operating-history or monthly-revenue criteria do not meet those criteria.
- Flex payments are restricted to businesses processing daily card payments; do not assume they apply to every applicant.
- The fixed cost of capital does not decrease simply because repayment takes less time.
What to verify before signing
Ask how collections will work for your business and what balance remains after each collection. Confirm the total repayment and any contractual obligations separately from the funding amount. Meeting initial criteria is not the same as receiving approval.
For your 2026 decision, put the proposed collection schedule beside your actual payroll and supplier dates. A business with healthy monthly sales can still face a difficult week if several obligations fall together.
Verdict: Buy only if the written agreement leaves enough operating cash after collections. Choose this route for its direct-funder fit, not as a substitute for reviewing the contract.
2. Recurring-revenue financing: best for subscription businesses
Recurring-revenue financing is a route for businesses whose customers pay on an ongoing subscription or contractual basis. A funder evaluates the revenue stream and sets an agreement around its own eligibility and collection rules. The category name does not establish that payments automatically decline when customer receipts fall.
Best for: Subscription businesses that can explain customer retention, cancellations and the timing of recurring receipts.
Strengths and limitations
Recurring-revenue financing pros:
- Gives recurring customer receipts a central role in the funding discussion.
- Creates a basis for comparing funding obligations with subscription collections.
- Supports a focused assessment of retention and revenue continuity rather than headline sales alone.
Recurring-revenue financing cons:
- Recurring billing does not eliminate cancellations, failed payments or customer concentration.
- Collection terms differ between agreements; a recurring-revenue assessment does not promise variable repayment.
- The route is a poor match when your business cannot distinguish recurring revenue from one-off sales.
What to verify before signing
Ask what the funder counts as recurring revenue. Separate signed contracts, collected receipts and projected renewals in your own records, then check which of those the assessment uses.
Review what happens if a major customer cancels. Your business still needs to understand the collection obligation, adjustment process and reporting requirements under that scenario. A funding offer based on subscription revenue is not evidence that the business can comfortably support it.
Verdict: Hold until the agreement explains collections after customer losses. Recurring-revenue financing belongs on the shortlist when subscription receipts are central to your business, not merely because you offer a subscription product.
3. E-commerce revenue financing: best for online inventory cycles
E-commerce revenue financing is a route for online retailers evaluating funding against sales activity. Your assessment should connect the proposed advance to inventory purchases, customer receipts, refunds, fulfilment and other selling costs. The relevant question is how much cash each sales cycle produces, not just how much revenue it records.
Best for: Online retailers with sales records and a clear plan for converting funded inventory into collected cash.
Strengths and limitations
E-commerce revenue financing pros:
- Focuses the funding discussion on an identifiable sales channel.
- Gives you a practical way to compare inventory purchases with expected customer receipts.
- Encourages a cash-flow assessment that includes refunds and fulfilment rather than gross sales alone.
E-commerce revenue financing cons:
- Returns and selling expenses reduce the cash available for collections.
- Unsold inventory can leave funding obligations running ahead of customer receipts.
- Revenue-linked terminology does not establish the treatment of refunds, taxes or marketplace deductions.
What to verify before signing
Ask which sales figure drives the agreement: gross orders, settled receipts or another defined measure. Then check how returns and deductions affect that figure. The definitions need to match the records you can produce.
For a 2026 inventory decision, separate buying stock from selling it profitably. Confirm that your expected receipts cover the stock purchase, selling expenses and funding obligation without depending on another advance.
Verdict: Hold until the inventory cycle supports the collection schedule. E-commerce revenue financing fits an evidenced stock-to-cash plan, not a sales target on its own.
How the options are ranked
The order prioritizes business-model fit, clear collections and operating headroom. Direct Canadian funding comes first for the general small-business reader; subscription and e-commerce routes follow because their usefulness depends on a more specific revenue model.
This is a decision framework, not a claim that every provider in a category offers the same terms. No approval rate, repayment structure or contract provision transfers automatically from one funder to another.
Your own ranking should change with your business. A subscription operator should start with recurring-revenue fit; an online retailer should start with the inventory cycle. Compare actual agreements using the same criteria before deciding.
Check repayment against your operating cash
Use this sequence when you receive an offer. Keep the exercise tied to collected cash rather than invoices or sales forecasts alone.
- Collected revenue: Start with receipts that reach your business account.
- Essential expenses: Identify payroll, suppliers, rent, taxes and existing commitments.
- Funding collections: Apply the agreement's collection method and timing.
- Cash remaining: Check what remains for operations and unexpected expenses.
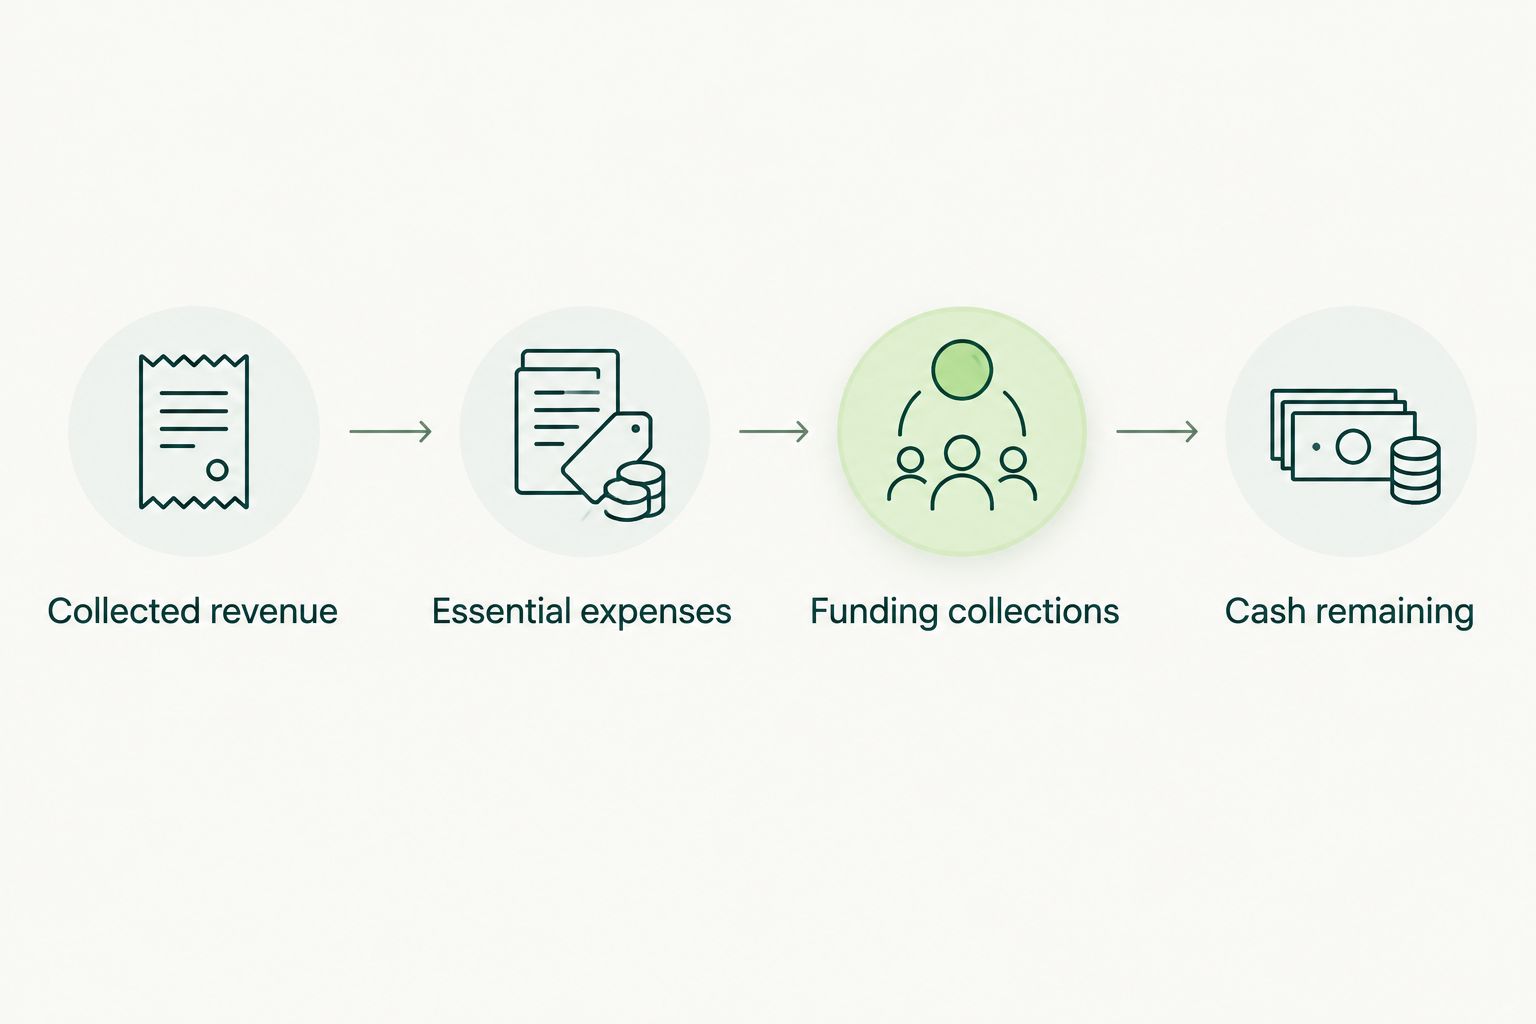
Assess the cash left for operations, not just the revenue used to qualify.
Repeat the exercise using a slower period from your own records. Do not replace that evidence with an invented industry benchmark. If collections leave too little cash, discuss a different amount or structure before proceeding.
Also read the agreement for security interests, personal guarantees, reporting obligations and restrictions on additional funding. Ask whether each applies; never infer the answer from the phrase revenue based financing.
Which revenue based financing should you choose?
Choose the route that matches your revenue model and preserves operating cash. For an eligible Canadian operating business, start with a direct-funder discussion. For a subscription business, examine how recurring receipts are assessed; for an online retailer, examine the stock-to-cash cycle.
For 2026, make the written agreement your deciding document. An approval tells you funding is offered. It does not tell you whether the collections fit your business.
Discuss your funding options
Speak with a funding specialist about your business revenue and working-capital needs.
Discuss funding options
FAQ
What is revenue based financing?
Revenue based financing connects a funding arrangement to business revenue. The contract determines eligibility, total repayment and whether collections are fixed, sales-linked or adjusted through a separate process.
What is the best revenue based financing option in Canada?
The best option matches your business model and leaves enough cash for operations after collections. Compare direct merchant cash advances, recurring-revenue financing and e-commerce financing against the written terms offered to your business.
Is a 2M7 merchant cash advance a loan?
A 2M7 merchant cash advance is a merchant cash advance, not a loan. The Canadian direct funder provides working capital for uses including payroll, inventory, equipment and cash-flow gaps.
Will payments automatically fall if my sales drop?
Do not assume payments automatically fall when sales drop. Confirm whether the contract uses a sales percentage, a fixed withdrawal or a separate adjustment process, including any eligibility conditions.
Can a business with less-than-perfect credit apply?
Less-than-perfect credit is within the stated customer profile for the direct-funder option described here. Approval is not guaranteed, and the business must still meet the applicable assessment criteria.
How should I compare financing costs in 2026?
Compare the complete amount payable, collection timing and all contractual charges. Ask what happens after early settlement or slower repayment rather than assuming either changes the cost.
What should an online retailer check before accepting funding?
An online retailer should check whether collected sales cover inventory, refunds, fulfilment, other operating expenses and funding collections. Gross order value alone does not establish repayment capacity.
One last thing
A revenue-linked assessment and a revenue-linked payment are different things. Before signing, ask the funder to show how the same agreement operates during both a stronger and a slower period from your records.
That explanation should identify the collection amount or calculation, the adjustment process and the cash your business retains. If the answer remains unclear, wait for written clarification.
Related guides


