ClickCease

5 Low-Cost Ways to Market Your Small Business in Canada

5 Low-Cost Ways to Market Your Small Business in Canada

29
Sep 2026
12
Oct 2026

Marketing is the first line item owners cut and the last one they should. A business that stays invisible does not grow. A large spend is not the answer either. Owners who win on a tight budget pick a few tactics that pay back quickly. They run them consistently and track the results. Here are five that work, followed by how to fund a larger push when the numbers justify it.

1. Improve your online presence 

Your website and social profiles work like a storefront that never closes. Most of your competitors already have one, and customers expect to find you online before they ever call or visit. Being online is only the baseline. Being easy to find and easy to trust is what earns the sale.

Start with what costs nothing

Claim and complete your Google Business Profile. Make sure your website loads quickly on a phone. Put one clear offer on your homepage. Then pick one social platform where your customers actually spend time and post there consistently for ninety days before you judge the result. Spreading yourself across four platforms produces four weak accounts.

2. Sell more to the customers you already have

BDC reports that selling to a new customer can cost about five times as much as selling to an existing one. The cost gap between new and existing customers should shape your marketing budget. Writing personally to your ten best customers only takes an afternoon. Inviting them to preview a new product costs almost nothing. A retail shop can go further with a simple points card that rewards the third and fifth visit. Repeat buyers are also your cheapest source of honest feedback, so ask them what you should change. A loyalty program raises the value of each customer without raising your ad spend.

‍

‍

3. Ask for referrals

Referrals need no ad spend. The lead also arrives already trusting you.  Most owners skip them because asking feels awkward. Ask at the moment the customer is happiest, right after a job goes well or a compliment lands. A restaurant can slip a card in with the bill that gives both the guest and their friend a free appetizer. A service business can ask at final payment. Make the offer simple enough to explain in one sentence.

4. Own your local market

For most small businesses the customer base sits within a short drive. Reputation inside that radius compounds. Ask every happy customer for a Google review. Sponsor a minor hockey team or a charity drive so your name shows up where your neighbours already look. Contractors can photograph finished jobs and put a sign at every active site. A trucking company can send five local shippers a short weekly note on available capacity, so it is the first call when freight needs to move. Small, repeated visibility beats one expensive campaign.

5. Build an email list you own

A social following depends on someone else's algorithm. An email list does not. Collect addresses at checkout, on invoices and through a sign-up form on your website. Follow Canada's anti-spam rules from the first sign-up. The CRTC guidance says CASL requires consent, sender identification and an unsubscribe mechanism for commercial messages.  Consent can be express or implied, but implied consent expires: two years after a purchase and six months after an inquiry. Ask for express consent at sign-up and record how and when each person opted in.

When a bigger push makes sense

Low-cost tactics have a ceiling, and the hidden cost is your time. At some point a paid campaign, a website rebuild, a seasonal inventory build or a marketing hire is the faster route to revenue. The question is how to pay for it without starving day-to-day operations.

Fund it against a measurable return

Only fund marketing you can measure. Set a target such as cost per lead, then work out how many sales it takes to cover the spend. Give each campaign its own promo code or landing page so you know which dollars produced sales. Cut anything that fails after sixty days and put that money behind what works.

If the math works, the funding structure matters as much as the campaign. A merchant cash advance is not a loan, so there is no interest rate. You pay a one-time cost of capital that you know before you sign. 2M7 Financial Solutions’ advances range from $5,000 to $300,000. Most applications receive a decision within 24 hours, which fits a campaign with a fixed launch date. To qualify, a business must operate in Canada, have run for at least three months and bring in at least $15,000 a month.

Match repayment to revenue

Marketing pays back on a delay. An ad you run in March may not produce full revenue until May. Fixed payments that start immediately can squeeze operations during that gap. Businesses that process daily credit and debit payments can choose flex payments, where repayment rises and falls with sales. Fixed payments are also available.

Bad credit does not end the conversation

Many owners assume a weak credit history rules out funding. With 2M7, bad credit will not automatically sink an application. The team weighs monthly revenue, time in business and industry alongside it.

Put your marketing budget to work

If a marketing push is on your calendar, contact 2M7. More than 5,000 Canadian businesses have partnered with 2M7. Send three months of bank statements, a photo ID and a void cheque, and we will reach out as soon as possible. The team will help you choose between fixed and flex payments during the process. Then spend the money on the campaign instead of waiting on it.

FAQs

‍

Can I use a merchant cash advance to pay for marketing?

Yes. 2M7 funding can go toward advertising and promotions, and it has no narrow spending restrictions tied to specific categories. Business owners use it for things like a paid ad campaign or the inventory needed for a seasonal push. Funding ranges from $5,000 to $300,000.

How is a merchant cash advance different from a business loan?

A merchant cash advance is not a loan, so there is no interest rate. You pay a one-time cost of capital instead. 2M7 shows you that cost before you sign, and you pay it off over time along with the funds. No collateral is required.

What are the eligibility requirements?

Your business must be located in Canada. It must have operated for at least three months and bring in at least $15,000 a month. You also cannot have an open bankruptcy. Bad credit does not automatically rule you out, because 2M7 also looks at monthly revenue, time in business and industry. You will need three months of bank statements, a photo ID and a void cheque.

Can I choose how I repay the funding?

Yes. 2M7 offers fixed and flex payment options. Fixed payments stay at a scheduled amount, while flex payments are based on a percentage of daily credit and debit sales and are available to businesses that process those payments.

What is the cheapest way to market a small business in Canada?

The cheapest tactics cost time instead of money. Claim your Google Business Profile and ask happy customers for reviews. Ask for referrals and sell more to the customers you already have. Add an email list you own so you are not relying on a social algorithm. No single tactic wins for every business. Pick two or three, run them consistently for ninety days and track what brings in sales before you spend on paid ads. 

‍

Related articles

September 29, 2026
October 12, 2026

5 Low-Cost Ways to Market Your Small Business in Canada

Marketing is the first line item owners cut and the last one they should. A business that stays invisible does not grow. A large spend is not the answer either. Owners who win on a tight budget pick a few tactics that pay back quickly. They run them consistently and track the results. Here are five that work, followed by how to fund a larger push when the numbers justify it.

1. Improve your online presence 

Your website and social profiles work like a storefront that never closes. Most of your competitors already have one, and customers expect to find you online before they ever call or visit. Being online is only the baseline. Being easy to find and easy to trust is what earns the sale.

Start with what costs nothing

Claim and complete your Google Business Profile. Make sure your website loads quickly on a phone. Put one clear offer on your homepage. Then pick one social platform where your customers actually spend time and post there consistently for ninety days before you judge the result. Spreading yourself across four platforms produces four weak accounts.

2. Sell more to the customers you already have

BDC reports that selling to a new customer can cost about five times as much as selling to an existing one. The cost gap between new and existing customers should shape your marketing budget. Writing personally to your ten best customers only takes an afternoon. Inviting them to preview a new product costs almost nothing. A retail shop can go further with a simple points card that rewards the third and fifth visit. Repeat buyers are also your cheapest source of honest feedback, so ask them what you should change. A loyalty program raises the value of each customer without raising your ad spend.

‍

‍

3. Ask for referrals

Referrals need no ad spend. The lead also arrives already trusting you.  Most owners skip them because asking feels awkward. Ask at the moment the customer is happiest, right after a job goes well or a compliment lands. A restaurant can slip a card in with the bill that gives both the guest and their friend a free appetizer. A service business can ask at final payment. Make the offer simple enough to explain in one sentence.

4. Own your local market

For most small businesses the customer base sits within a short drive. Reputation inside that radius compounds. Ask every happy customer for a Google review. Sponsor a minor hockey team or a charity drive so your name shows up where your neighbours already look. Contractors can photograph finished jobs and put a sign at every active site. A trucking company can send five local shippers a short weekly note on available capacity, so it is the first call when freight needs to move. Small, repeated visibility beats one expensive campaign.

5. Build an email list you own

A social following depends on someone else's algorithm. An email list does not. Collect addresses at checkout, on invoices and through a sign-up form on your website. Follow Canada's anti-spam rules from the first sign-up. The CRTC guidance says CASL requires consent, sender identification and an unsubscribe mechanism for commercial messages.  Consent can be express or implied, but implied consent expires: two years after a purchase and six months after an inquiry. Ask for express consent at sign-up and record how and when each person opted in.

When a bigger push makes sense

Low-cost tactics have a ceiling, and the hidden cost is your time. At some point a paid campaign, a website rebuild, a seasonal inventory build or a marketing hire is the faster route to revenue. The question is how to pay for it without starving day-to-day operations.

Fund it against a measurable return

Only fund marketing you can measure. Set a target such as cost per lead, then work out how many sales it takes to cover the spend. Give each campaign its own promo code or landing page so you know which dollars produced sales. Cut anything that fails after sixty days and put that money behind what works.

If the math works, the funding structure matters as much as the campaign. A merchant cash advance is not a loan, so there is no interest rate. You pay a one-time cost of capital that you know before you sign. 2M7 Financial Solutions’ advances range from $5,000 to $300,000. Most applications receive a decision within 24 hours, which fits a campaign with a fixed launch date. To qualify, a business must operate in Canada, have run for at least three months and bring in at least $15,000 a month.

Match repayment to revenue

Marketing pays back on a delay. An ad you run in March may not produce full revenue until May. Fixed payments that start immediately can squeeze operations during that gap. Businesses that process daily credit and debit payments can choose flex payments, where repayment rises and falls with sales. Fixed payments are also available.

Bad credit does not end the conversation

Many owners assume a weak credit history rules out funding. With 2M7, bad credit will not automatically sink an application. The team weighs monthly revenue, time in business and industry alongside it.

Put your marketing budget to work

If a marketing push is on your calendar, contact 2M7. More than 5,000 Canadian businesses have partnered with 2M7. Send three months of bank statements, a photo ID and a void cheque, and we will reach out as soon as possible. The team will help you choose between fixed and flex payments during the process. Then spend the money on the campaign instead of waiting on it.

FAQs

‍

Can I use a merchant cash advance to pay for marketing?

Yes. 2M7 funding can go toward advertising and promotions, and it has no narrow spending restrictions tied to specific categories. Business owners use it for things like a paid ad campaign or the inventory needed for a seasonal push. Funding ranges from $5,000 to $300,000.

How is a merchant cash advance different from a business loan?

A merchant cash advance is not a loan, so there is no interest rate. You pay a one-time cost of capital instead. 2M7 shows you that cost before you sign, and you pay it off over time along with the funds. No collateral is required.

What are the eligibility requirements?

Your business must be located in Canada. It must have operated for at least three months and bring in at least $15,000 a month. You also cannot have an open bankruptcy. Bad credit does not automatically rule you out, because 2M7 also looks at monthly revenue, time in business and industry. You will need three months of bank statements, a photo ID and a void cheque.

Can I choose how I repay the funding?

Yes. 2M7 offers fixed and flex payment options. Fixed payments stay at a scheduled amount, while flex payments are based on a percentage of daily credit and debit sales and are available to businesses that process those payments.

What is the cheapest way to market a small business in Canada?

The cheapest tactics cost time instead of money. Claim your Google Business Profile and ask happy customers for reviews. Ask for referrals and sell more to the customers you already have. Add an email list you own so you are not relying on a social algorithm. No single tactic wins for every business. Pick two or three, run them consistently for ninety days and track what brings in sales before you spend on paid ads. 

‍

Read more
October 19, 2026
October 19, 2026

Best equipment financing for healthcare and dental practices 2026

Best overall: a dedicated equipment loan for a planned, long-term purchase. Best for scheduled upgrades: equipment leasing. Best for equipment plus operating expenses: 2M7 merchant cash advance funding. This 2026 guide compares equipment financing for healthcare practices by ownership, payment structure and fit for your cash flow.

TL;DR

  • Dedicated equipment loans are the default equipment financing for healthcare practices buying assets for long-term use.
  • Equipment leasing suits dental and healthcare practices that want an agreed equipment replacement or return path.
  • 2M7 merchant cash advance funding suits equipment purchases combined with payroll, inventory or other working capital needs.
  • Compare total repayment, ownership terms and payment obligations before choosing funding.

Why this matters

A dental chair and the payroll needed to operate a practice are different funding needs. An equipment agreement addresses the asset; working capital addresses the business around it. Bundling both into the wrong agreement makes comparison harder.

For a 2026 purchase, start with the equipment's expected useful life and the practice's available cash. Then compare financing structures. A lower scheduled payment does not establish a lower total cost, and equipment delivery does not necessarily mean the equipment is ready to generate revenue.

Choose the funding structure before choosing the provider. That keeps ownership, payment obligations and installation expenses in the same decision.

What makes the best equipment financing for healthcare practices

Use these criteria to compare written offers for medical, dental and other practice equipment:

  • Ownership: Establish who owns the equipment during the agreement and what happens at the end.
  • Useful life: Match the funding period to how long you expect to use the asset, not just the payment you prefer.
  • Total obligation: Compare the full amount payable, including required fees and any end-of-term purchase obligation.
  • Cash flow fit: Check payment frequency against patient collections, insurer payments and other operating commitments.
  • Funding scope: Confirm whether the agreement covers equipment alone or also delivery, installation, training and operating expenses.
  • Exit terms: Read early settlement, equipment return, replacement and security provisions before signing.

For your 2026 shortlist, request these details in writing. An equipment quotation and a financing quotation answer different questions; you need both to judge the purchase.

Equipment financing options at a glance

The ranking below reflects a planned equipment purchase as the default situation. Each alternative serves a different need rather than claiming to be the cheapest for every practice.

Dedicated equipment loan

  • Best for: Planned purchases for long-term ownership
  • Standout feature: Borrowing tied to an equipment purchase
  • Key limitation: Security, guarantees and eligible expenses depend on the agreement

Equipment lease

  • Best for: Planned replacement or return
  • Standout feature: Contract defines equipment use and end-of-term choices
  • Key limitation: Ownership and exit rights are not automatic

2M7 merchant cash advance

  • Best for: Equipment plus working capital
  • Standout feature: Direct funding for equipment and operating needs
  • Key limitation: Existing business and revenue requirements apply

Business line of credit

  • Best for: Smaller purchases made in stages
  • Standout feature: Draw funding as eligible expenses arise
  • Key limitation: Access remains subject to the facility's terms and limit

1. Dedicated equipment loan: best for long-term ownership

A dedicated equipment loan finances an equipment purchase through a lending agreement. It is the strongest starting point when you know the asset, intend to keep it and can support scheduled payments from practice cash flow.

For a dental practice buying a chair or a healthcare practice buying diagnostic equipment, ownership matters beyond delivery. Check whether the lender takes security over the equipment, other business assets or both, and whether a personal guarantee is required.

Equipment loan pros

  • Supports a purchase intended for long-term use.
  • Separates a major capital purchase from routine operating spending.
  • Lets you compare a defined borrowing amount and repayment schedule.
  • Provides a clear basis for comparing purchase funding against leasing.

Equipment loan cons

  • Required security and guarantees can extend beyond the equipment itself.
  • Installation, training or related expenses need explicit approval for inclusion.
  • Selling or replacing financed equipment can require the lender's consent.

Best for: Established practices purchasing equipment they expect to keep rather than replace on a short cycle.

Ask the lender how it handles used equipment, supplier deposits and delivery delays. Do not assume approval for the machine also covers renovations or the period before it becomes operational.

Verdict: Buy with a dedicated equipment loan when long-term ownership is the priority and the complete repayment schedule fits your practice.

2. Equipment leasing: best for planned replacement

Equipment leasing gives your practice the right to use equipment under a contract. The agreement determines payments, responsibilities and what you can do when the term ends.

A lease deserves a place on your shortlist when you expect to replace equipment as practice requirements change. It is not automatically a subscription with a simple return process: purchase options, renewal provisions and return conditions must appear in the contract.

Equipment lease pros

  • Makes equipment use, rather than immediate ownership, the starting point.
  • Can support a planned replacement cycle when the contract provides for it.
  • Defines end-of-term choices before you commit.
  • Creates an alternative to borrowing for an outright purchase.

Equipment lease cons

  • Payments do not automatically give your practice ownership.
  • Early termination and equipment returns can create additional obligations.
  • Maintenance, insurance and servicing are not automatically included.

Best for: Dental and healthcare practices with a clear replacement plan and acceptable contractual return or purchase terms.

Before choosing a lease in 2026, ask what happens if the equipment stops meeting your clinical needs before the term ends. Also confirm who handles removal, shipping and any required restoration when you return it.

Verdict: Buy through leasing when the replacement plan is clear; skip a lease whose exit conditions you cannot accept.

3. 2M7 merchant cash advance: best for mixed funding needs

A merchant cash advance provides business funding rather than an equipment loan. This route fits a different problem: your practice needs equipment and working capital for expenses such as payroll, inventory or a cash flow gap.

2M7 is a Canadian direct funder, not a broker. It serves businesses operating for at least 3 months with $15,000 or more in monthly revenue, including businesses with less-than-perfect credit.

Merchant cash advance pros

  • Supports equipment and working capital needs through the same funding category.
  • Provides a direct relationship with the funder rather than a broker.
  • Includes consideration for businesses with less-than-perfect credit.
  • Uses one fixed cost of capital, disclosed before signing, that does not change with repayment duration.

Merchant cash advance cons

  • Minimum operating history and monthly revenue requirements apply.
  • A fixed cost of capital does not become lower simply because repayment takes less time.
  • Flex payments are only for businesses processing daily card payments.

Best for: Operating practices that need equipment funding alongside payroll, inventory or other working capital, rather than asset-only financing.

The published 75% approval rate is not an individual approval decision. Confirm your practice's eligibility, the proposed payment structure and the full obligation before treating funding as committed.

For healthcare practices paid through a mix of insurer reimbursements, patient payments and other sources, discuss that collection pattern directly. Do not assume a payment feature designed for daily card processing applies to your practice.

Verdict: Buy through merchant cash advance funding when the need spans equipment and operating expenses and the written payment terms fit your collections.

4. Business line of credit: best for staged smaller purchases

A business line of credit provides access to borrowing up to an approved limit, subject to its terms. It suits purchases made at different times rather than a single large asset acquisition.

For example, a practice adding equipment room by room can compare a credit facility with separate purchase agreements. The important distinction is access versus commitment: an available limit is not a reason to spend it all.

Business line of credit pros

  • Supports borrowing as individual eligible expenses arise.
  • Helps separate purchase timing from a single equipment delivery date.
  • Can address incidental business expenses as well as equipment, subject to permitted use.
  • Lets you reserve borrowing for actual purchases rather than estimated future needs.

Business line of credit cons

  • Equipment purchases consume capacity that might otherwise cover operating needs.
  • Rates, payment requirements and review conditions depend on the agreement.
  • A revolving balance needs a deliberate repayment plan.

Best for: Practices making smaller, staged purchases while preserving a defined reserve for day-to-day operations.

Set a repayment target for each equipment purchase before drawing funds. Otherwise, a long-lived asset can sit inside a revolving balance without a clear point at which the purchase is paid off.

Verdict: Buy through a line of credit for staged purchases; skip it when the purchase would absorb the practice's operating reserve.

Compare written offers in the same order

You cannot compare an equipment lease with working capital funding by looking at the scheduled payment alone. Put each offer against the same purchase plan and include the obligations that sit outside the headline payment.

Purchase scope

List the equipment, delivery, installation, training and any site work separately. Mark which expenses each agreement actually covers. Confirm when suppliers require payment and when the practice becomes responsible for financing payments.

Total obligation

Request the full amount payable and the payment schedule. For a lease, include any required purchase payment if ownership is your goal. For other funding, confirm fees, early settlement conditions and security requirements.

Collection fit

Map the proposed payment dates against collections and existing commitments. Include payroll, rent and supplier payments. A purchase that fits annual revenue can still place pressure on cash between collection dates.

Exit terms

Ask what happens if you replace the equipment, sell the practice or settle the agreement early. Get written answers. A verbal explanation does not replace the signed terms.
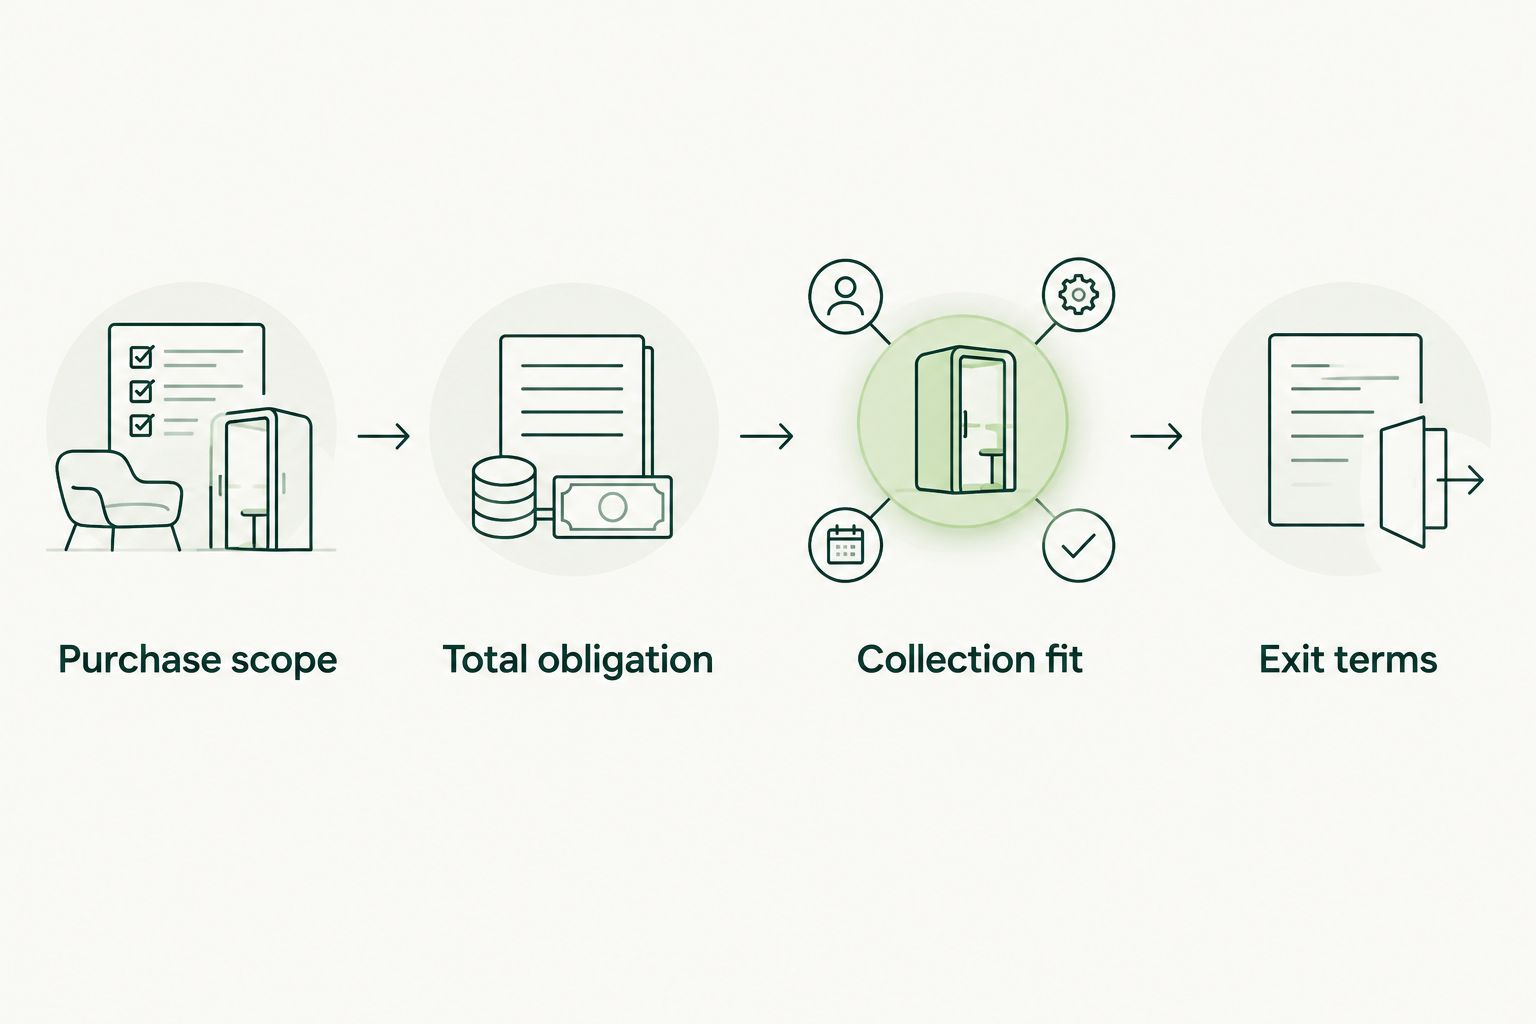
Four checks for equipment funding: purchase scope, total obligation, collection fit and exit terms.

Compare the complete obligation and collection schedule, not just the scheduled payment.

How the options are ranked

This 2026 ranking puts a dedicated equipment loan first because the default task is purchasing equipment for continued use. Leasing takes the replacement-planning slot, merchant cash advance funding addresses mixed equipment and operating needs, and a line of credit addresses staged purchases.

The ranking uses ownership, useful life, total obligation, cash flow fit, funding scope and exit terms. It is a comparison of funding structures, not a provider scorecard or a claim that one agreement has the lowest cost.

Which equipment financing should you choose?

Start with a dedicated equipment loan for a defined purchase you intend to keep. Compare a lease alongside it when replacement or return is part of your plan, not simply because its scheduled payment looks smaller.

Choose 2M7 equipment funding when the purchase forms part of a broader working capital need and a merchant cash advance fits your practice's collections. Keep a line of credit focused on staged purchases that leave enough capacity for operating needs.

For a 2026 decision, the final test is practical: can you explain the complete payment obligation, ownership position and exit terms without relying on the sales presentation? If not, hold the decision until those points are clear.

FAQ

What's the best equipment financing for healthcare practices?

A dedicated equipment loan is the default starting point for a planned purchase intended for long-term use. Compare leasing for planned replacement, merchant cash advance funding for mixed operating needs, and a line of credit for staged purchases.

Is leasing better than buying equipment for a dental practice?

Leasing is a better fit when the agreement supports your intended replacement or return plan. Buying is the stronger starting point when long-term ownership matters; compare the complete obligations rather than scheduled payments alone.

Does 2M7 offer equipment loans to healthcare practices?

2M7 provides merchant cash advances and working capital, not equipment loans. Equipment is an eligible funding use, and a practice must meet the funder's business and revenue requirements.

Can a newer healthcare practice apply for merchant cash advance funding?

The stated entry requirements include at least 3 months in business and $15,000 or more in monthly revenue. Meeting those thresholds does not establish an individual approval decision or funding amount.

Can equipment financing cover installation and training?

Installation and training are covered only when the agreement includes them. Ask for an itemised list of eligible expenses before committing to equipment or supplier deposits.

What should a dental practice compare besides the payment amount?

Compare the full amount payable, payment frequency, ownership, security requirements and exit terms. Include maintenance obligations and any end-of-term purchase or return requirements.

Are flex payments suitable for every healthcare practice?

Flex payments are only for businesses that process daily card payments. A practice should confirm eligibility based on its actual collections rather than assuming all patient or insurer receipts qualify.

One last thing

Check the gap between equipment delivery and equipment use. Installation, training or site preparation can separate those dates, while payment obligations follow the agreement. Put both dates on your purchase plan before signing, then confirm which expenses your funding covers during that gap.

Related guides

Read more
July 22, 2026
September 27, 2026

How to Build a Cash Flow Cushion for Your Business

Ask most Canadian small business owners what keeps them up at night and the answer is rarely competition or marketing. It's money. More specifically, it's the unpredictable gap between money coming in and money going out. Over 20% of small businesses in Canada are actively concerned about cash flow issues, and given how tight operating conditions have been, that number makes sense. Profitable businesses fail every year in this country. Not because the product wasn't good or the customers weren't there, but because the timing was off.

A cash flow cushion is how you protect yourself from that timing problem. It's not about hoarding cash or being conservative to the point of paralysis. It's about building the kind of financial breathing room that lets you make decisions from a position of stability rather than panic.

Here's how to actually do it.

‍

Start With a Realistic Picture of Your Cash Flow

You can't build a cushion if you don't know where the gaps are. The first step is getting honest about your monthly inflows and outflows. Not revenue projections, not what you hope to collect. Actual cash.

Map out your recurring fixed costs: rent, payroll, insurance, loan payments, subscriptions. Then layer in your variable costs: inventory, supplies, fuel, contractors. Finally, look at when your customers actually pay you. If you're invoicing net-30 or net-60, there's a real lag between completing work and seeing money. That lag is where businesses get into trouble.

Build a rolling 90-day cash flow forecast and update it every two weeks. You're looking for months where outflows spike or inflows dip. Payroll runs, GST/HST remittances, lease renewals, slow seasons: all of it shows up clearly when you're looking forward instead of reacting.

‍

Tighten Up What You Can Control

Before looking at outside financing, squeeze your existing cycle. Send invoices the same day work is completed. Offer a small early-payment discount if your margins allow for it (1-2% is enough to change behavior for most customers). Chase overdue accounts on a consistent schedule rather than waiting until you desperately need the money.

On the payables side, don't pay early out of habit. Know your terms and use them. If a supplier offers net-30 and you've been paying in five days, you're giving away cash float. Negotiate better terms when you can. Suppliers who value the relationship will often extend payment windows for reliable customers.

Take an honest look at inventory. Excess stock is cash sitting on a shelf. Float's 2025 Canadian Business Report found that average cash balances across Canadian businesses dropped nearly 5% while total debt stayed flat, meaning businesses are spending down reserves just to keep operating. That's a dangerous place to be when a slow month hits.

‍

Target a Cash Reserve, Then Build It Methodically

Most financial advisors suggest keeping three to six months of operating expenses in reserve. For many small businesses, that number feels unreachable. Start smaller. Even 30 days of operating expenses in a separate account changes the math significantly when something goes sideways.

The key is treating the reserve contribution like any other fixed expense. A set percentage of every deposit goes to the reserve account. Even 3-5% of monthly revenue, consistently applied, builds real cushion over a year or two.

If your business is seasonal, plan around your peaks. When revenue is strong, bank more than your baseline. Build the cushion before the slow months arrive, not after.

‍

Use Financing as a Strategic Tool, Not a Crisis Response

Here's something a lot of business owners get backwards: the best time to access financing is before you need it. When you're approaching a lender from a stable position, you have options. When you're in crisis, you don't.

Lines of credit work well for businesses with relatively predictable revenue patterns. Apply when things are going well, even if you don't intend to use the credit immediately. Having the facility in place means you can respond to opportunity or a cash dip without scrambling.

For businesses with strong daily or weekly sales volume but inconsistent bank lending access, a merchant cash advance can provide fast, flexible capital that repays in proportion to your sales. That structure is genuinely useful for managing cash flow because payments naturally flex with your revenue. For a closer look at how this type of funding fits a growing business, read benefits of a merchant cash advance for expansion.

For businesses in construction and trades, project timing creates serious cash flow volatility and receivables often lag months behind work performed. Know what your options are before you're staring down a payroll gap. Retailers carrying large inventory positions ahead of peak seasons can look at inventory and growth funding that moves with how their business actually cycles. 

The right type of fast business funding depends entirely on your business model. A restaurant has different needs than a trucking company. Knowing which products fit your situation, before you're under pressure, is part of building a real cushion strategy.

‍

Don't Overlook Your Credit Profile

Your ability to access affordable financing is directly tied to how lenders see you. If your credit has taken hits, whether personal or business, that limits your options and raises your cost of capital. But it doesn't eliminate them.

Alternative lenders evaluate businesses differently than traditional banks do. Revenue history, consistency, and industry matter as much or more than a clean credit score. Access-to-capital concerns among small businesses hit 29% in 2025, well above the historical average of 22%. That pressure is real, but it's also created a broader ecosystem of lenders who specialize in situations traditional banks won't touch.

If your credit has taken hits, you have more options than you think. It's practical knowledge worth having before you actually need it.

‍

Build the Habit, Not Just the Balance

A cash flow cushion isn't a one-time project. It's a discipline. The businesses that consistently weather downturns, seasonal dips, and unexpected costs are almost never the ones with the most revenue. They're the ones that made financial visibility and reserve-building a weekly habit, not an annual conversation with their accountant.

According to the federal government's Key Small Business Statistics report, small businesses contribute over 33% of Canada's private sector GDP and employ nearly half the private sector workforce. The stakes for getting this right extend well beyond any single balance sheet.

The cash isn't always there yet. But the plan for getting there can start today.

If you're looking for guidance on which financing options make sense for your business right now, the team at 2M7.ca is available to walk you through.

‍

Read more