ClickCease

5 Reasons Why Successful Businesses Also Borrow Money

5 Reasons Why Successful Businesses Also Borrow Money

5 Reasons Why Successful Businesses Also Borrow Money
26
May 2021
20
Sep 2026

There's a huge misconception in the world of business. People tend to think that if a company (that's not a startup) has to borrow money, it's not successful. Yes, in certain situations, you do need some capital to get up and running from a few bad months. However, usually, it isn't bad for your company. It can be a huge boost for your business and take your sales to a new height that you didn't know existed. Here are five reasons why successful businesses needs to borrow money.

Meet Consumer Demands

If you're running a successful business, you're going to scale over time. Your customers will increase, and your current production capacity won't meet your future demands. Scaling is an important part of the journey, and if you don't speed up production, the sign that says 'out of stock' will run your enterprise into the ground. Taking a merchant cash advance (MCA) could be a great way to upgrade equipment and start meeting consumer demands. It does cost you money upfront, but in the long run, it'll boost your profits tenfold. For a closer look at how this type of funding fits a growing business, read using a merchant cash advance to grow your business.

Stepping Away from a Rough Patch

We mentioned COVID-19 a while ago, and it is a major reason why companies need to be open to the idea of borrowing money. Millions of businesses globally shut down because either their services weren't required by the public or they couldn't maintain enough profits to stay above water. If your company struggled to find ground but still made it to the early post-COVID era we're in right now, you're lucky. However, things might not be such food to you if you can't get yourself back to a certain level of stability. By taking a merchant cash advance, you might be able to hire new personnel, find new contractors to work with, spend more on advertising, and get back to work!

Making Payments on Time

Even some of the top businesses in the world need raw materials to make their products. And, most of the time, payments from customers take months until they're in the pocket of the finance department. To make sure you make all your payments on time, an MCA will help you keep the wheel spinning, and since you already have the money needed to pay it back, you're good to go.

Keeping Up With Competition

No matter what you sell, there's probably some other businesses out there that has been in the same industry for longer than you have. This means that they have a stable grip on the market and have a better cash flow to scale their business. Taking a merchant cash advance is like a quick hack to catch up to your competition and speed up sales much quickly as compared to the other, more traditional routes.

Reducing Personal Investments

If you’re running a small to medium business, it’s always tempting to put in all your personal savings to keep the business afloat. Building a cash reserve is a good way to keep financial problems at bay. However, a recommendable way to save yourself from the pitfall of personal investments is to borrow money. By bringing in the cash you need from other places, you’re keeping your bank account safe and sound.

Closing Thoughts

The word 'debt' is not the final nail in the coffin for your company. With proper planning, it can help you reach heights that you never imagined. That is where we come in. 2M7 Financial Solutions is a company that offers merchants cash advances, which you can return from a specific percentage of your sales. If you're looking for a reliable company to help you outshine your competition, request a quote, we will be happy to assist you.

Related articles

July 1, 2026
September 27, 2026

5 Ways to Boost Your Business Cash Flow

Cash flow is the kind of problem that feels personal. You know your business is generating revenue. You know invoices are out. And yet the bank account tells a story that doesn't match the one in your head.

This is one of the most common situations Canadian small business owners find themselves in, and it has nothing to do with whether the business is viable. It has to do with timing. Money moves out before it moves back in, and in the gap between those two things, businesses that are technically profitable can still feel like they're barely keeping pace.

The good news: this is a solvable problem. Here's what actually works.

1. Stop Waiting to Invoice

The fastest way to tighten your cash cycle is to close the gap between when work is done and when the invoice goes out. Many business owners batch invoices at the end of the month out of habit. That habit costs you weeks of float every billing cycle.

Send the invoice the day the job is done, the product ships, or the milestone is reached. Most accounting software (QuickBooks, FreshBooks, Wave) lets you automate this. If you're still sending invoices manually, that's worth fixing too, but start with the timing.

While you're at it, look at your payment terms. Net-30 is standard, but it's a convention rather than a requirement. Many businesses successfully shift to Net-15 or even Net-7 for certain clients. Some add a small early payment discount of 1–2% to make faster payment genuinely attractive. Over the course of a year, shortening your average days outstanding has a real impact on how much cash you have available at any given time.

2. Get Serious About Receivables

Sending the invoice is step one. Collecting on it is the step most businesses handle inconsistently.

Pull your accounts receivable aging report. If you don't know where to find it, it's in your accounting software, which shows every outstanding invoice sorted by how long it's been unpaid. According to a Stripe analysis of 250,000 invoices, an invoice that remains unpaid past 90 days has only an 18% chance of being collected. Anything past 45 days deserves a phone call, not another email. Anything past 60 is a cash flow problem, not just an administrative one.

A few things that help:

  • Follow up within 3 days of an invoice going past due, not 30
  • Accept multiple payment methods, because the easier you make it to pay, the faster people pay
  • For clients with consistently slow payment patterns, consider requiring a deposit before work starts
  • For large project-based work, build milestone payments into the contract so you're not waiting until completion to see money

None of this is aggressive. It's running your business like the cash matters, because it does.

3. Negotiate Your Payables Without Burning Relationships

Most business owners put more energy into speeding up what comes in than managing what goes out. Both sides of the equation matter.

Talk to your suppliers. If you have a solid payment history with them, many will extend your terms from Net-30 to Net-45 or Net-60 without much pushback. That extension alone can give you meaningful breathing room when you're waiting on a large receivable. Some suppliers also offer a discount for early payment. That discount is worth taking when you have cash and worth skipping when you don't.

The same principle applies to equipment and asset purchases. Outright purchases wipe cash immediately. Leasing or financing that equipment spreads the cost over time and preserves working capital for things that are harder to finance, like payroll, inventory, and operating costs that don't come with payment terms attached.

This isn't about avoiding payment. It's about aligning when money goes out with when money comes in.

4. Know Your Cash Cycle, Not Just Your Profit Margin

Your income statement tells you whether your business model is working. Your cash flow statement tells you whether your business will survive long enough to prove it.

As QuickBooks Canada notes, without proper cash flow management, even profitable businesses can face serious obstacles. The two statements can tell completely opposite stories at the same time because revenue is recorded when it's earned, not when it's collected. If you invoiced $80,000 last month on Net-60 terms, that $80,000 does not exist as cash yet.

Understanding your cash conversion cycle, which is how long it actually takes from the first dollar spent to getting paid, gives you the visibility to plan ahead. A retailer buying inventory before a peak season, a contractor fronting materials before a draw payment, a service business billing at month-end and chasing payment for 45 days: each of these has a predictable cycle. Once you know yours, you can anticipate the gaps instead of reacting to them.

A 13-week cash forecast sounds like something only larger companies bother with. It isn't. Even a rough projection of what's coming in and going out over the next quarter gives you enough lead time to act before a shortfall becomes a crisis.

5. Use Working Capital as a Tool, Not a Last Resort

Here's a shift in thinking that changes how a lot of business owners operate: external capital isn't only for emergencies. For businesses where the cash cycle is structurally long, where spending always precedes earning, a working capital facility is a sign of clarity rather than distress.

The business owners who handle cash flow best tend to have financing in place before they need it. Not because they're struggling, but because they know a real opportunity won't wait for a bank's approval timeline.

For Canadian small businesses that don't meet the documentation requirements of the Big 5 banks, or simply can't wait weeks for an answer, a Merchant Cash Advance works differently. Rather than borrowing against credit history or collateral, you're accessing capital against your future revenue. Repayment comes as a percentage of daily sales, so it flexes with how your business is actually performing. Strong month? It pays down faster. Slow stretch? The repayment eases automatically. For a closer look at how this type of funding fits a growing business, read how a merchant cash advance supports a growing business.

At 2M7, the approval process is built around your current business performance: your bank statements, your revenue trends, your cash flow. Not a credit score from two years ago. Businesses operating for at least 3 months with at least $15,000 per month in revenue can apply with just three documents (bank statements, a photo ID, and a void cheque), and can be approved within 24 hours with funds deposited the same day. If you want to understand what that might look like for your situation, the conversation starts here.

The Real Problem Isn't Cash. It's Timing.

Most cash flow problems aren't evidence that something is broken. They're evidence of a gap between when you earn and when you collect. It's one of the oldest tensions in business, and every business owner confronts it eventually.

The ones who handle it best aren't necessarily the ones with the most cash on hand. They're the ones who understand the cycle, manage it deliberately, and know what tools are available when the gap needs bridging.

If you're working through a cash flow challenge right now, or you want to get ahead of one before peak season hits, 2M7 works with Canadian small business owners at exactly this stage.

‍

Read more
October 14, 2026
October 14, 2026

Best equipment financing options in Canada 2026

Best overall for long-term ownership: an equipment loan. Best for planned replacement: an equipment lease. Best for flexible purchases: a business line of credit. This 2M7 guide compares equipment financing options in Canada for 2026 by ownership, cash flow and contract restrictions—not by advertised payments alone.

TL;DR

  • 2M7’s equipment financing Canada guide ranks equipment loans first for businesses seeking long-term ownership.
  • Equipment leases suit planned replacement, but return conditions and purchase options need close review.
  • Business lines of credit suit flexible purchases when repayment does not crowd out operating cash.
  • Compare vendor-arranged financing with direct financing using the same equipment quote and repayment assumptions.

Why this matters

Equipment financing affects more than your payment schedule. It determines whether you own the asset, what security the financier takes and what happens when you replace or sell the equipment.

A payment that fits today does not settle the decision. Your business also needs enough cash for maintenance, insurance, payroll and periods when the equipment produces less revenue.

For 2026, start with the asset’s job in your business. A machine you intend to keep needs a different financing assessment from equipment you expect to replace as your work changes.

What makes the best equipment financing option?

Use these criteria before comparing offers. The strongest option fits the equipment’s working life and your repayment capacity without creating an unwanted exit obligation.

  • Ownership: Decide whether you need title to the equipment or only the right to use it.
  • Payment fit: Match scheduled obligations to cash your business can reliably generate, not its busiest period.
  • Total obligation: Compare the full payment schedule, fees and any required final payment or purchase amount.
  • Security: Identify the assets pledged and whether a personal guarantee is required.
  • Exit terms: Check early repayment, early termination, sale restrictions and end-of-term responsibilities.
  • Asset fit: Confirm that the proposed arrangement accepts the specific equipment, condition and intended use.

Ask for written terms. A verbal explanation of ownership or an end-of-term purchase option is not a substitute for the contract.

Equipment financing options at a glance

These 5 financing routes serve different needs. Vendor-arranged financing describes how you obtain the offer; the underlying contract can still be a loan or lease.

Equipment loan

  • Best for: Long-term ownership
  • Standout feature: Finances an equipment purchase with scheduled repayment
  • Key limitation: Security and repayment obligations remain until discharged

Equipment lease

  • Best for: Planned replacement
  • Standout feature: Provides equipment use under an agreed lease term
  • Key limitation: Ownership and exit depend on the contract

Business line of credit

  • Best for: Flexible purchases
  • Standout feature: Allows borrowing and repayment within an approved facility
  • Key limitation: Equipment debt can consume working-capital capacity

Vendor-arranged financing

  • Best for: Purchase coordination
  • Standout feature: Connects the equipment purchase with a financing application
  • Key limitation: Convenience does not establish the best financing terms

Secured business loan

  • Best for: Equipment within a broader project
  • Standout feature: Can fund an eligible project containing equipment and other expenses
  • Key limitation: Security can extend beyond the purchased equipment

The table ranks financing structures, not lenders. Approval criteria, documentation and contract terms differ between providers, so the same structure can produce very different obligations.

1. Equipment loan: best equipment financing for long-term ownership

An equipment loan finances the purchase of equipment and requires repayment under an agreed schedule. The business purchases the asset, while the lender can take security over it or other agreed assets.

An equipment loan is the default choice when ownership is the goal and scheduled repayments fit the business. That does not make every equipment loan suitable: the security agreement, repayment terms and asset restrictions still decide whether the offer works.

Equipment loan pros

  • Supports purchasing equipment you intend to keep.
  • Provides a defined repayment schedule under the agreement.
  • Separates the purchase from a lease-return decision.
  • Lets you assess financing alongside the equipment’s expected working life.

Equipment loan cons

  • Repayments continue even when the equipment is idle.
  • Security requirements can restrict disposal of the asset.
  • Early repayment conditions require review before signing.

Best for: Businesses buying equipment for continuing use rather than routine replacement.

Before accepting a 2026 equipment loan, ask what happens if the asset needs replacement before repayment ends. You need to know whether sale proceeds can discharge the financing, whether lender consent is required and whether any remaining balance survives the sale.

Verdict — Buy: Choose an equipment loan when you want ownership and can support the repayment schedule through quieter trading periods.

2. Equipment lease: best equipment financing for planned replacement

An equipment lease gives your business the right to use equipment under an agreement with the lessor. The contract determines the payment schedule, permitted use, maintenance responsibilities and end-of-term choices.

A lease is not automatically a path to ownership. If ownership matters, identify the purchase option and its conditions before comparing the lease with a loan.

Equipment lease pros

  • Suits businesses focused on equipment use rather than immediate ownership.
  • Establishes a defined term for the equipment arrangement.
  • Allows a planned end-of-term decision where the contract provides suitable choices.
  • Can align with a replacement plan when the lease conditions support it.

Equipment lease cons

  • Early termination can create contractual obligations.
  • Return conditions can add work and expense at the end.
  • A purchase option is not the same as an unconditional transfer of ownership.

Best for: Businesses with a defined replacement plan and equipment needs that fit the lease term.

For a 2026 lease comparison, request the return requirements alongside the payment schedule. Equipment condition, transport responsibilities and notice deadlines belong in the decision, not in a separate file you read later.

Also distinguish financing from service. Maintenance, repairs and replacement equipment are included only when the agreement explicitly says so.

Verdict — Buy: Choose an equipment lease when the use period and end-of-term obligations match your replacement plan; skip it when ownership terms are unclear.

3. Business line of credit: best equipment financing for flexible purchases

A business line of credit allows borrowing within an approved limit under the facility’s terms. It can fund equipment purchases where the agreement permits that use, without a separate equipment-financing contract for each purchase.

Flexibility is its main advantage. The trade-off is that the equipment purchase uses capacity your business might otherwise need for operating expenses.

Business line of credit pros

  • Supports purchases at different times within the approved facility.
  • Allows repayment and further borrowing under the agreement.
  • Avoids matching every purchase to a separate equipment contract.
  • Provides flexibility when the final purchasing schedule is uncertain.

Business line of credit cons

  • Equipment borrowing reduces remaining credit capacity.
  • Variable-rate terms expose borrowing costs to rate changes.
  • An accessible facility still needs a deliberate repayment plan.

Best for: Businesses making flexible purchases while preserving enough unused capacity for operations.

Do not treat the available limit as an equipment budget. First reserve the capacity needed for supplier payments, payroll and revenue interruptions, then assess what remains.

Compare a line of credit with a dedicated equipment loan when the purchase will stay financed for a long period. Flexible borrowing is useful only if the repayment plan fits the asset and does not leave operating cash permanently constrained.

Verdict — Hold: Use a business line of credit for equipment only after setting a repayment plan and protecting working-capital capacity.

4. Vendor-arranged financing: best equipment financing for purchase coordination

Vendor-arranged financing connects an equipment purchase with a financing offer or application through the seller. The seller might introduce a financing provider or present an arrangement available for that purchase.

This is a purchasing channel, not a distinct financial contract. Determine whether the actual offer is a loan, lease or another agreement before assessing its suitability.

Vendor-arranged financing pros

  • Coordinates the equipment quote with the financing application.
  • Keeps the proposed asset clearly identified during the process.
  • Gives you an offer to compare with independently obtained financing.

Vendor-arranged financing cons

  • The presented offer does not represent every financing option.
  • Purchase convenience can distract from security and exit terms.
  • The financing provider and equipment seller can be separate parties.

Best for: Buyers who want coordinated purchasing but will still compare the written financing agreement.

Request the equipment quote separately from the financing schedule. This makes it easier to compare the same asset across offers without confusing equipment charges with financing obligations.

For a 2026 purchase, ask who handles an equipment dispute and who collects payments. Do not assume a dispute with the seller automatically pauses obligations to a separate financier.

Verdict — Hold: Consider vendor-arranged financing after comparing its underlying contract with a direct financing offer for the same equipment.

5. Secured business loan: best equipment financing for a broader project

A secured business loan can fund eligible business purposes under the lender’s agreement. Equipment can form part of a wider project that also includes installation, premises work or other approved expenses.

This route deserves consideration when the equipment purchase is only one part of the funding need. Its central limitation is the security package: assets beyond the equipment can be pledged.

Secured business loan pros

  • Can address an eligible project rather than an isolated asset purchase.
  • Allows equipment and related approved expenses to be assessed together.
  • Provides a repayment structure for the agreed borrowing.

Secured business loan cons

  • Security can extend beyond the financed equipment.
  • Broader funding needs require careful documentation of eligible uses.
  • Project delays do not automatically change repayment obligations.

Best for: Businesses funding equipment within a defined expansion or installation project.

Separate the equipment budget from the rest of the project before applying. You need to understand which expenses the proposed facility covers and which must come from existing cash.

Compare this route against a dedicated equipment loan plus separately funded project expenses. The choice depends on repayment fit and security exposure, not simply whether one agreement feels easier to administer.

Verdict — Hold: Choose a secured business loan when the wider project justifies it and the pledged assets are acceptable.

How the options are ranked

This 2M7 equipment financing guide ranks each route by its clearest use case: ownership, planned replacement, purchasing flexibility, purchase coordination or broader project funding.

Equipment loans take the default position because they directly address an equipment purchase with ownership as the objective. Leases take the replacement slot; lines of credit take the flexibility slot. Vendor arrangements and broader secured loans require an additional check because the channel or project scope does not itself establish suitable financing terms.

No ranking substitutes for reviewing the actual contract. An unsuitable equipment loan loses to a lease that genuinely fits your business.

Check cash flow before choosing

Build a 12-month cash-flow forecast that includes the proposed financing obligations and equipment operating expenses. Use 3 cash-flow scenarios: expected trading, weaker revenue and an equipment interruption.

Follow this sequence before signing:

  • Define ownership: State whether you need to own the asset or use it for a defined period.
  • Check obligations: Include scheduled payments, required fees and end-of-term commitments.
  • Stress cash flow: Test repayment alongside payroll, suppliers, maintenance and insurance.
  • Review exit: Read the conditions for repayment, termination, sale or return.

The weaker-revenue scenario should show whether your business can meet obligations without relying on the equipment operating continuously. The interruption scenario should include the operational consequence of downtime as well as the financing payment.
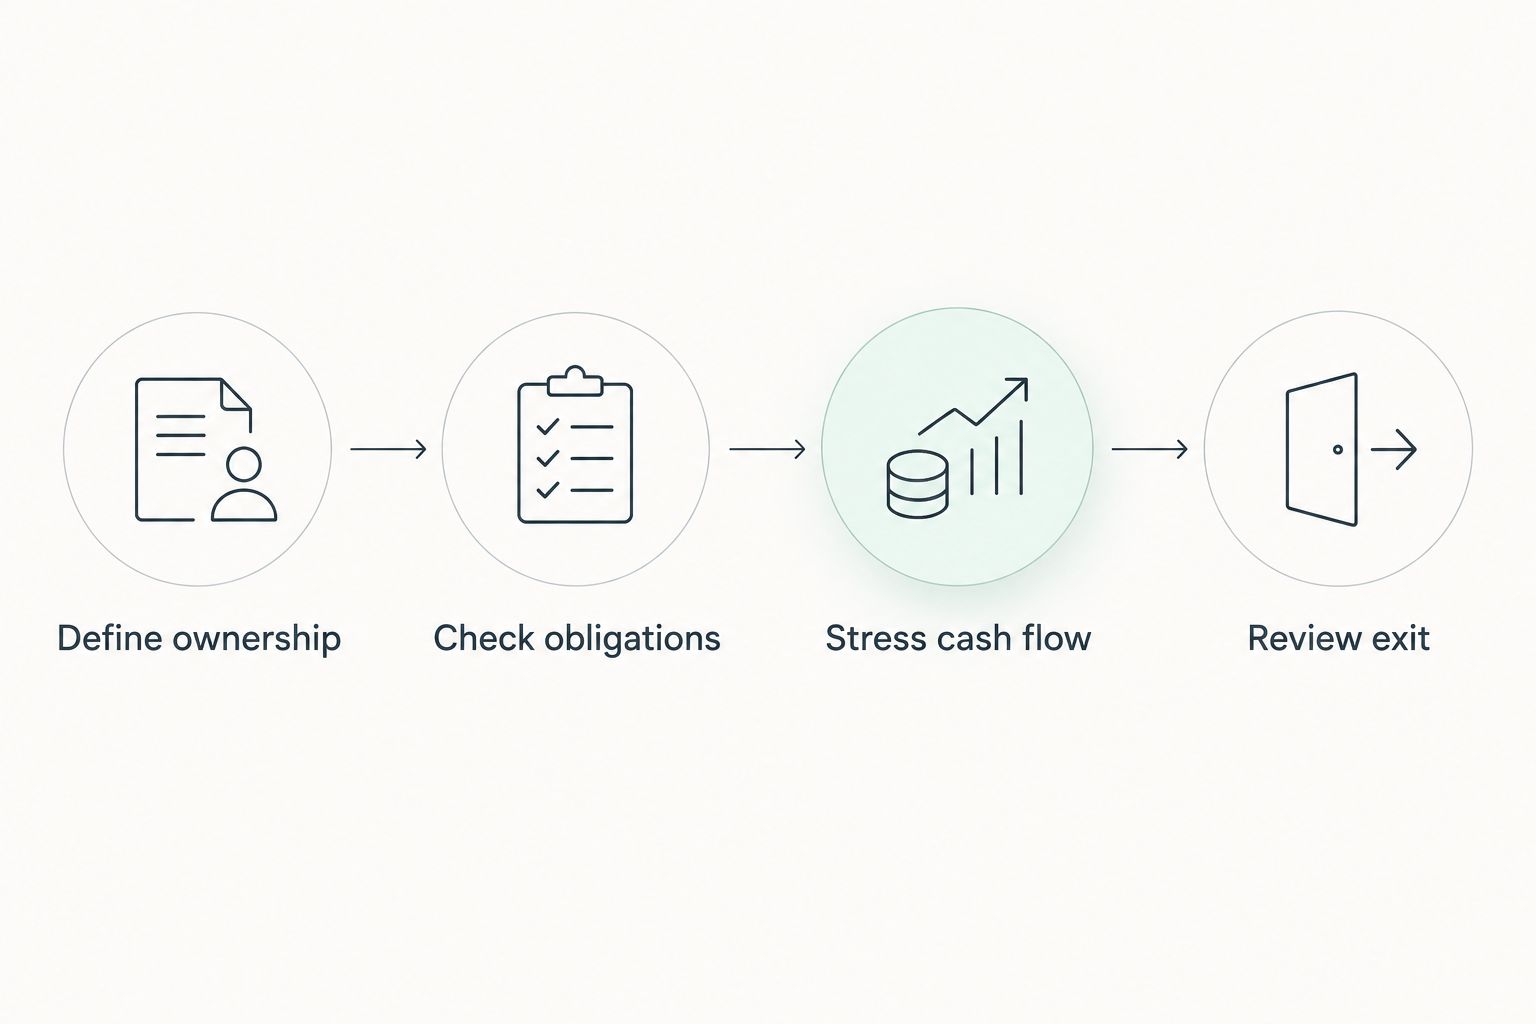
Four checks covering ownership, obligations, cash flow and exit terms

Check repayment capacity and exit terms before accepting the financing agreement.

Keep assumptions consistent across offers. Comparing one arrangement using strong sales and another using cautious sales tells you nothing useful about the financing itself.

Which equipment financing option should you choose?

Choose an equipment loan first when you want to own equipment for continuing use. Compare a lease when replacement is planned, and consider a line of credit only when equipment borrowing leaves sufficient operating capacity.

For equipment financing in Canada in 2026, use the 2M7 guide to choose the structure before comparing providers. Then compare written offers for the same equipment, funding need and intended use period.

If none of the offers survives your cash-flow checks, wait. Financing does not fix a purchase that your business cannot support.

FAQ

What’s the best equipment financing option in Canada?

An equipment loan is the default option for businesses seeking long-term ownership and scheduled repayment. A lease fits planned replacement better when its end-of-term conditions match the business’s needs.

Is an equipment loan better than a lease?

An equipment loan is better aligned with ownership; a lease is better aligned with use over an agreed term. Compare security, repayment obligations and exit conditions before choosing.

Can I buy equipment with a business line of credit?

You can use a business line of credit for equipment when the facility permits that use. Set a repayment plan and preserve enough capacity for operating expenses.

Does an equipment lease include maintenance?

An equipment lease includes maintenance only when the agreement explicitly provides it. Review responsibility for repairs, servicing, insurance and equipment downtime separately.

Is vendor financing a loan or a lease?

Vendor-arranged financing can involve a loan or lease, depending on the underlying agreement. Identify the actual financing provider and contract type before comparing the offer.

How much does equipment financing cost in Canada?

Equipment financing costs depend on the written offer, including financing charges, fees and required final obligations. Compare complete schedules for the same equipment and funding need rather than payments alone.

What should I check before signing an equipment financing agreement?

Check ownership, payment obligations, security, guarantees and exit conditions before signing. Test the agreement against expected trading, weaker revenue and an equipment interruption.

One last thing

The end of the agreement belongs in the beginning of your decision. Before accepting equipment financing in 2026, write down exactly what you must do to own, return, sell or replace the asset.

If you cannot explain that outcome in plain language, pause and get the relevant contract clause clarified. The final obligation matters as much as the first payment.

Read more
October 15, 2026
October 15, 2026

Best alternative business financing options in Canada 2026

Best overall for eligible businesses seeking sales-based working capital: 2M7 merchant cash advances. Best for recurring borrowing: a business line of credit; best for unpaid invoices: invoice factoring. This 2026 guide compares six alternative business financing options in Canada by funding purpose, eligibility and repayment fit.

TL;DR

  • 2M7 merchant cash advances suit eligible Canadian businesses seeking alternative business financing for working capital.
  • Business lines of credit suit recurring borrowing; invoice factoring suits businesses waiting on customer invoices.
  • Equipment financing matches funding to assets; purchase order financing supports eligible supplier payments.
  • Equity financing suits growth plans where owners accept shared ownership instead of scheduled repayments.

Why this matters

The best financing option matches the expense, the cash coming back and the repayment obligation. An equipment purchase, an unpaid invoice and a payroll gap are different problems. Treating them as the same borrowing need makes comparison harder.

For your 2026 funding decision, start with the transaction rather than the provider. Identify what you need to pay, when that spending produces cash and which repayment structure your business can support. Then compare written offers within the right category.

What makes the best alternative business financing?

Use these criteria to shortlist funding before you submit applications:

  • Funding purpose: Match unrestricted working capital, invoice funding or asset financing to the actual expense.
  • Eligibility fit: Check operating history, revenue, customer quality and security requirements before applying.
  • Repayment fit: Compare payment frequency and obligations with the timing of your receipts.
  • Total obligation: Read the complete repayment amount, charges, guarantees and contractual conditions together.
  • Ownership impact: Separate financing that creates payment obligations from investment that shares ownership.
  • Exit terms: Understand early settlement, cancellation, renewal and security-release provisions before signing.

These criteria matter more than a headline approval claim. A funding offer belongs on your shortlist only when you understand both how it helps and what your business commits to.

Alternative business financing at a glance

This 2026 ranking gives each option a distinct job. The order is a decision guide, not a claim that one funding structure beats every other structure.

2M7 merchant cash advance

  • Best for: Eligible businesses seeking sales-based working capital
  • Standout feature: Direct funding with one fixed cost of capital disclosed before signing
  • Key limitation: Minimum operating history and revenue requirements apply

Business line of credit

  • Best for: Recurring short-term borrowing
  • Standout feature: Draw, repay and reuse credit within the agreement
  • Key limitation: Access depends on approval and account terms

Invoice factoring

  • Best for: Businesses waiting on customer invoices
  • Standout feature: Funding tied to eligible receivables
  • Key limitation: Customer-facing collection arrangements need review

Equipment financing

  • Best for: Purchasing business equipment
  • Standout feature: Financing connected to a specific asset
  • Key limitation: Not a general solution for unrelated operating expenses

Purchase order financing

  • Best for: Supplier payments for confirmed customer orders
  • Standout feature: Funding connected to order fulfilment
  • Key limitation: Order, supplier and transaction eligibility restrict its use

Equity financing

  • Best for: Growth without scheduled financing repayments
  • Standout feature: Capital exchanged for an ownership interest
  • Key limitation: Owners give up a share of ownership and potentially control

1. 2M7 merchant cash advances: best for sales-based working capital

A merchant cash advance provides business funding against future sales. 2M7 is a Canadian direct funder, not a broker, providing merchant cash advances and working capital for expenses such as payroll, inventory, equipment and cash flow gaps.

2M7 merchant cash advances are best for eligible Canadian businesses seeking sales-based working capital rather than a conventional loan. Businesses must have operated for at least 3 months and generate $15,000 or more in monthly revenue. Businesses with less-than-perfect credit are among those served.

2M7 merchant cash advance pros:

  • You deal with a direct funder rather than a broker.
  • Funding supports several operating purposes, including payroll and inventory.
  • One fixed cost of capital is shown before signing and does not change with repayment duration.

2M7 merchant cash advance cons:

  • Businesses below the operating-history or revenue thresholds do not meet the stated criteria.
  • Flexible payments are only for businesses that process daily card payments.
  • A fixed cost does not remove the need to check whether payments fit your cash flow.

Best for: An operating business with established revenue and a defined working-capital need.

Verdict: Hold until the written payment structure fits your cash flow. Meeting eligibility requirements is the starting point, not the final decision.

2. Business lines of credit: best for recurring borrowing

A business line of credit lets you draw funds up to an approved limit and reuse repaid amounts under the agreement. Banks, credit unions and non-bank providers offer credit facilities, so compare the actual contract rather than treating the provider category as the deciding factor.

A business line of credit fits repeated gaps between outgoing payments and incoming receipts. It is less useful when an ongoing operating loss, rather than timing, drives the need for funds.

Business line of credit pros:

  • You can draw funds as needs arise within the approved limit.
  • Repaid amounts become available again under revolving terms.
  • One facility can support different short-term operating expenses.

Business line of credit cons:

  • Approval, security and guarantee requirements vary by provider.
  • Review provisions and account conditions affect continued access.
  • Repeated borrowing can conceal a persistent cash shortfall.

Best for: Businesses with recurring, identifiable cash timing gaps and a clear repayment source.

Verdict: Hold until you have reviewed draw conditions and renewal terms. Choose a business line of credit for repeat use, not simply because the available limit looks attractive.

3. Invoice factoring: best for unpaid customer invoices

Invoice factoring converts eligible receivables into funding by selling invoices to a factor. The arrangement centres on customer invoices, so customer credit quality and invoice eligibility matter alongside your own business profile.

Invoice factoring is a focused option for businesses that have completed work but are waiting for payment. It does not solve a lack of sales, disputed billing or an expense unsupported by eligible receivables.

Invoice factoring pros:

  • Funding connects to work already invoiced.
  • Customer payment quality forms part of the assessment.
  • Collections support can form part of the arrangement.

Invoice factoring cons:

  • Disputed or otherwise ineligible invoices limit what you can fund.
  • Customer notification and collection practices need careful review.
  • Recourse terms determine your responsibility if a customer does not pay.

Best for: Business-to-business suppliers and service providers with eligible, unpaid invoices.

Verdict: Hold until you understand recourse and customer contact. Ask who collects payment, what customers receive and what happens when an invoice remains unpaid.

4. Equipment financing: best for a specific asset purchase

Equipment financing connects funding to machinery, vehicles or other business equipment. Depending on the agreement, the structure involves financing a purchase or leasing the asset, with different ownership and end-of-term obligations.

Choose equipment financing when the asset itself is the reason you need funding. Keep operating cash needs separate so you can assess whether the asset's business value supports the commitment.

Equipment financing pros:

  • The funding purpose is tied to an identifiable asset.
  • You can compare the agreement against the equipment's expected business use.
  • Purchase and lease structures offer different ownership arrangements.

Equipment financing cons:

  • Asset-linked funding does not necessarily cover payroll or other operating expenses.
  • Maintenance, insurance and end-of-term obligations require review.
  • Equipment can lose usefulness while contractual payments continue.

Best for: Businesses acquiring equipment with a clear operating purpose.

Verdict: Hold until ownership and end-of-term terms are clear. Compare equipment financing agreements using the full commitment, not just the payment shown on a proposal.

5. Purchase order financing: best for supplier payments

Purchase order financing supports eligible supplier payments associated with confirmed customer orders. The funder assesses the transaction, including the order, customer, supplier and fulfilment arrangements.

Purchase order financing fits an order-specific gap: you have a customer commitment but need funding to obtain the goods. It is not interchangeable with general working capital for unrelated expenses.

Purchase order financing pros:

  • Funding connects to an identifiable customer order.
  • Supplier payments are central to the structure.
  • You can assess the funding commitment against a specific transaction.

Purchase order financing cons:

  • Not every order, supplier or transaction qualifies.
  • Delivery, acceptance and customer payment conditions complicate the arrangement.
  • Financing obligations must fit the order's remaining margin.

Best for: Businesses fulfilling eligible confirmed orders that require supplier payments before customer receipts.

Verdict: Hold until the complete order economics work. Account for supplier, shipping, fulfilment and financing obligations before accepting funding.

6. Equity financing: best for growth with shared ownership

Equity financing brings capital into a business in exchange for an ownership interest. Unlike funding with scheduled repayments, the central trade-off is ownership, investor rights and the expectations attached to the investment.

Equity financing suits growth plans where an owner accepts an investment partner. A temporary cash timing problem alone is not a strong reason to give up ownership.

Equity financing pros:

  • Equity capital does not carry the same scheduled repayment structure as borrowing.
  • An investment agreement can support a longer-term growth plan.
  • Investors can contribute expertise or connections alongside capital.

Equity financing cons:

  • Existing owners give up part of their ownership.
  • Investor rights can affect decisions, reporting and future fundraising.
  • Negotiating ownership and governance takes preparation.

Best for: Businesses pursuing growth where shared ownership fits the owner's objectives.

Verdict: Hold until ownership and governance terms are understood. Assess the investor relationship as carefully as the capital offered.

How we ranked these financing options

The 2026 ranking follows funding purpose, eligibility fit, repayment fit, total obligation, ownership impact and exit terms. Each option earns a different use-case slot; the comparison does not claim that all businesses qualify or that all providers offer identical terms.

Merchant cash advances lead for eligible sales-based working capital. Business lines of credit address recurring borrowing, invoice factoring addresses receivables, equipment financing addresses assets, purchase order financing addresses orders, and equity financing addresses ownership-based investment.

Which financing option should you choose?

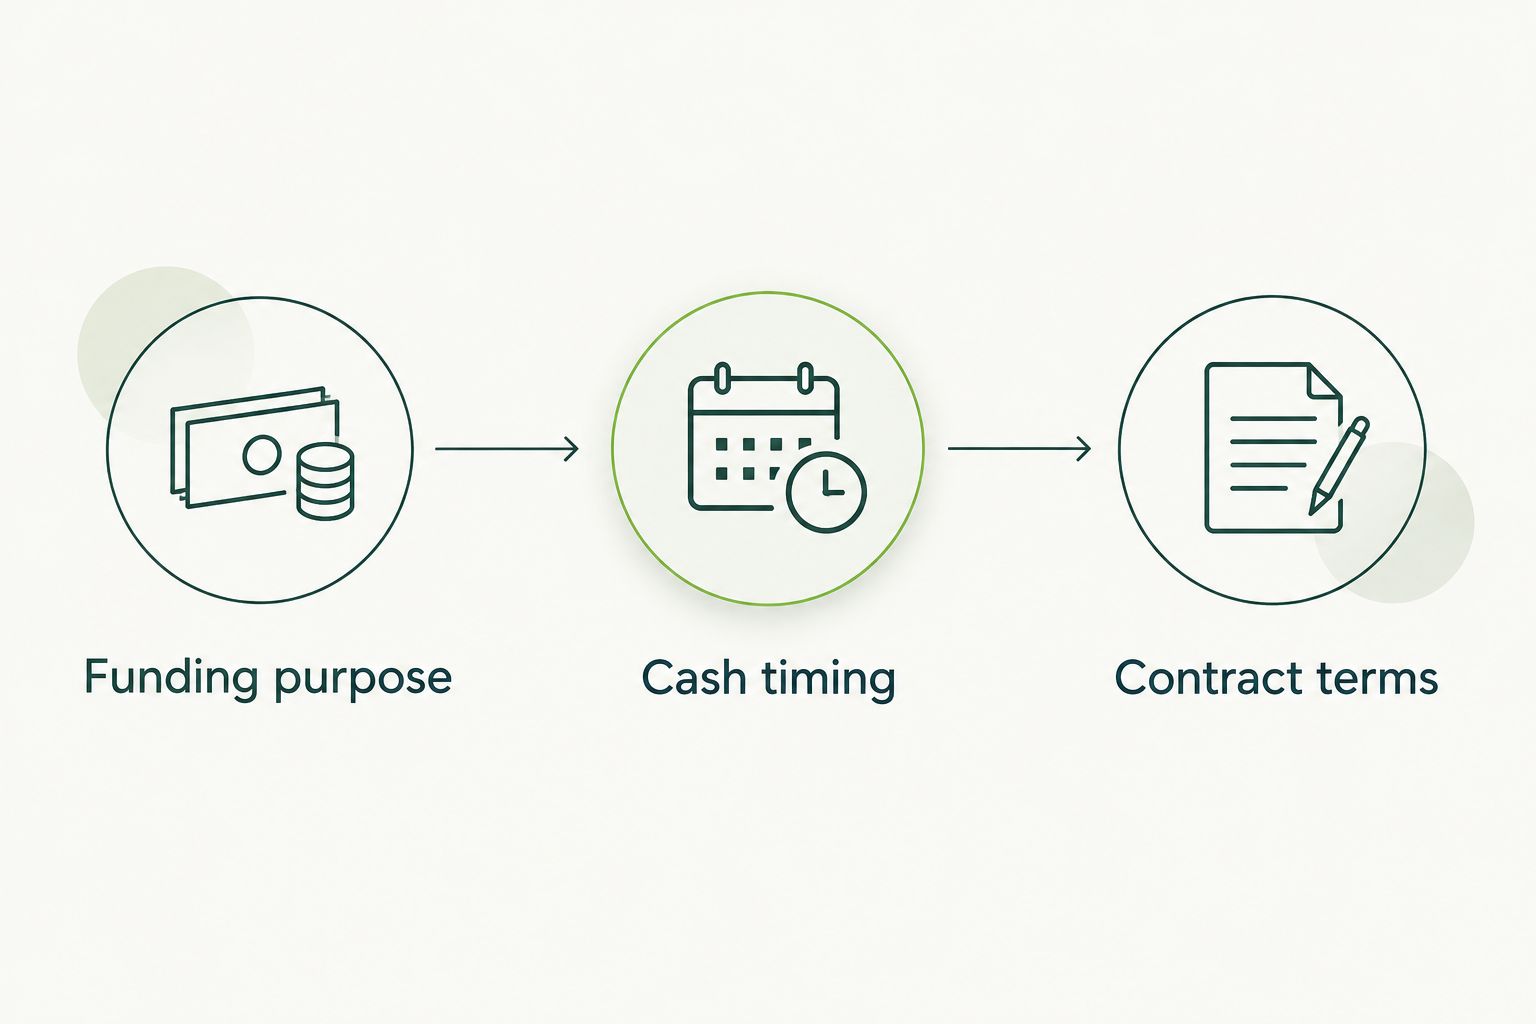
For an undecided owner, choose the category before the provider. Follow this sequence for your 2026 shortlist:

  1. Funding purpose: Name the expense and explain how it supports your business.
  2. Cash timing: Map customer receipts against the proposed payment obligations.
  3. Contract terms: Compare the full commitment, guarantees, security and exit provisions.

Three decision steps: funding purpose, cash timing and contract terms

Choose the funding category before comparing provider offers.

If you need general working capital and meet the stated operating and revenue thresholds, start by discussing a merchant cash advance. If the need comes from an invoice, an asset or a customer order, start with the category designed around that transaction.

Before signing, prepare a cash flow forecast showing the proposed obligation alongside payroll, supplier payments and existing commitments. Approval answers whether a funder will proceed. Your forecast answers whether the arrangement works for your business.

FAQ

What's the best alternative business financing option in Canada?

The best alternative business financing option depends on the funding purpose and repayment fit. Merchant cash advances address eligible working-capital needs, while invoice factoring, equipment financing and purchase order financing address specific transactions.

Is a merchant cash advance a business loan?

A merchant cash advance is funding against future sales, not a conventional business loan. Review the agreement's payment structure, total obligation and conditions before signing.

What does a business need to qualify for 2M7 funding?

The stated minimums are at least 3 months in business and $15,000 or more in monthly revenue. Meeting those thresholds does not establish approval or determine the final funding terms.

Is invoice factoring better than a business line of credit?

Invoice factoring fits eligible unpaid invoices, while a business line of credit fits recurring borrowing needs. Compare invoice eligibility, collection arrangements and recourse against the credit facility's draw and repayment conditions.

Can a business with less-than-perfect credit seek funding?

Businesses with less-than-perfect credit can seek funding from providers whose criteria include them. Approval still depends on the provider's assessment and the business meeting applicable requirements.

Do merchant cash advances always have flexible payments?

Do not assume every merchant cash advance has flexible payments. Confirm the written terms; the flexible-payment feature described in this guide is only for businesses that process daily card payments.

What should I compare besides the payment amount?

Compare the total obligation, payment frequency, guarantees, security and exit terms. For equity financing, also compare ownership dilution, investor rights and governance requirements.

One last thing

Approval is not a cash flow plan. Before accepting alternative business financing in 2026, place the proposed obligations into a quieter-sales scenario using your own records. If the plan depends on every customer paying promptly, revisit the amount or structure before signing.

Related guides

Read more