ClickCease

Four Small-Business Trends Canadian Owners Should Act On

Four Small-Business Trends Canadian Owners Should Act On

Four Small-Business Trends Canadian Owners Should Act On
7
Sep 2026
12
Oct 2026

Business trends are useful when they lead to better decisions. For Canadian small-business owners, four shifts now affect everyday operations: cyber risk is becoming more sophisticated, artificial intelligence is moving into normal workflows, customers are validating businesses across more channels, and persistent cost pressure is making cash-flow planning more important.

These trends apply differently across industries. A restaurant, contractor, retailer, and trucking company will not use the same technology or financing structure. The practical goal is to identify the changes that matter to your operation, test improvements on a manageable scale, and measure the result.

‍

1. Cyber resilience is now an operating requirement

Cybersecurity has moved well beyond antivirus software and an occasional password change. Phishing, ransomware, compromised credentials, payment fraud, and AI-assisted impersonation can disrupt sales, expose customer information, and stop a small team from operating.

CIRA’s 2025 Cybersecurity Survey collected responses from 500 cybersecurity decision-makers across Canada. Among the organizations surveyed, 43% reported being targeted in a cyberattack during the previous 12 months, while 42% reported a breach involving customer or employee data. CIRA also found that 70% were concerned about threats associated with generative AI. The Canadian Centre for Cyber Security similarly describes the national threat environment as increasingly complex and sophisticated.

The practical response is to build a small set of repeatable controls. Use multi-factor authentication for email, banking, payroll, cloud storage, and administrative accounts. Keep software and devices updated, restrict access to the information each employee actually needs, maintain tested backups, and train staff to verify unusual payment or account-change requests through a second channel.

An incident-response plan matters as much as prevention. The plan should identify who will secure accounts, contact financial institutions or technology vendors, communicate with customers, and restore critical systems. CIRA reported that 66% of surveyed organizations had used their incident-response plan in the prior year, reinforcing the value of deciding these responsibilities before an incident occurs.

‍

2. AI and digital tools need a clear business purpose

Artificial intelligence is becoming more common in Canadian businesses, but adoption alone does not guarantee a productivity improvement. Statistics Canada reports that 12.2% of Canadian firms used AI to produce goods or deliver services in 2025, double the previous year’s share, while another 14.5% planned to adopt it within the following 12 months.

The same Statistics Canada analysis offers an important caution. Firms using AI initially appeared more productive, but the direct relationship was no longer statistically significant after accounting for prior productivity and complementary capabilities such as cloud computing, data analytics, research and development, and employee technology training. The evidence suggests that AI delivers more value when it is part of a broader operating system rather than an isolated software purchase.

A sensible starting point is one repetitive, measurable workflow. A business might use a digital tool to summarize service requests, organize inventory data, draft routine customer communications, or flag overdue invoices. The owner should define the expected result, protect sensitive information, keep a person responsible for review, and compare time, error rates, or conversion outcomes before expanding the tool.

CFIB’s 2025 digital-transformation report drew on a survey of 1,683 Canadian business owners and found that firms with deeper digital adoption consistently reported stronger productivity outcomes than firms with lower adoption. The broader lesson is to connect technology spending to a process, a responsible employee, and a performance measure.

‍

3. Customers verify a business across multiple channels

A prospective customer may encounter a company through a search result, review platform, social post, industry directory, referral, or AI-generated answer. They often continue checking before they make contact. That makes consistency across the company’s website, business listings, reviews, and third-party profiles an important trust signal.

BrightLocal’s 2026 Local Consumer Review Survey used a representative panel of 1,002 U.S. adults. It found that 97% read reviews for local businesses and that respondents used an average of six review sites while evaluating businesses. After reading positive reviews, 54% said they were likely to visit the company’s website. These are U.S. consumer findings rather than Canadian population estimates, but they illustrate how reviews frequently lead to additional verification rather than an immediate purchase.

For a small business, the practical work is straightforward. Keep the business name, phone number, address, service area, hours, and product descriptions consistent wherever the company appears. Request genuine reviews as part of a normal follow-up process, respond specifically to both positive and negative feedback, and never buy or incentivize misleading reviews. Publish detailed case studies or testimonials only with appropriate customer permission.

The company website must support what people find elsewhere. Clear service explanations, real leadership information, transparent contact details, and consistent business facts help visitors evaluate credibility. They also give search engines and AI systems better source material when answering questions about the business. Owners evaluating any financing company should review its reputation, verify its claims, and use a structured set of questions before choosing a business funder.

‍

4. Cash-flow flexibility remains a competitive capability

Revenue and profit do not always arrive on the same schedule as payroll, inventory purchases, repairs, tax obligations, or supplier payments. Persistent cost pressure makes that timing gap harder to absorb.

Statistics Canada reported that 62.2% of businesses expected cost-related obstacles in the third quarter of 2025. Inflation was the most frequently cited cost obstacle, and accommodation and food services and retail trade were among the sectors most likely to identify it. The practical implication is that owners need a current cash-flow forecast rather than relying only on an annual budget or income statement.

A useful forecast maps expected cash receipts and required payments by week, highlights possible shortfalls, and defines what action the business will take if sales, collections, or costs move away from plan. Owners can also review supplier terms, deposit policies, invoicing speed, inventory levels, recurring expenses, and the minimum reserve needed to cover critical obligations.

External financing may be part of that plan, but the product should match the purpose. Innovation, Science and Economic Development Canada reports that 97% of small-business debt-financing applications were approved in 2025 and that the average interest rate declined to 5.8%. However, 75% of small businesses obtaining debt financing were required to pledge collateral, up from 66% in 2024. Availability therefore does not tell an owner whether a product is appropriate for a particular need.

Before choosing funding, compare the total repayment amount, annualized cost where available, collateral or guarantee requirements, time to funding, payment frequency, flexibility during slower periods, early-payment terms, and permitted use of proceeds. A conventional loan or line of credit may suit a planned, longer-term investment. A merchant cash advance may be considered for a shorter-term working-capital need when speed and revenue-linked remittances are important, but its total cost should be reviewed carefully. Businesses with imperfect credit can also compare the broader range of business-funding options available in Canada.

‍

Turn trends into operating decisions

The most useful response to these trends is a short operating plan. Strengthen one cyber control, test one digital workflow, correct inconsistent public information, and update a 13-week cash-flow forecast. Each action should have an owner, a deadline, and a simple measure of success.

If a working-capital need remains after reviewing expenses, collections, reserves, and conventional financing, compare the available structures carefully. 2M7 can explain how its funding works and provide the total repayment and remittance terms for review. Readers can also consult the small-business finance glossary before requesting a quote or starting an application.

‍

Sources

  1. 2025 CIRA Cybersecurity Survey
  2. National Cyber Threat Assessment 2025–2026 — Canadian Centre for Cyber Security
  3. Artificial intelligence adoption and productivity in Canadian firms — Statistics Canada
  4. Digital Transformation: How small businesses in Canada are leveraging AI and technology — CFIB
  5. Local Consumer Review Survey 2026 — BrightLocal
  6. Canadian Survey on Business Conditions, third quarter 2025 — Statistics Canada
  7. Small Business Credit Condition Trends, 2015–2025 — Innovation, Science and Economic Development Canada

‍

Related articles

October 15, 2026
October 15, 2026

Best unsecured business loans in Canada 2026

Best overall for a defined expense: an unsecured term loan. Best for recurring cash flow gaps: an unsecured business line of credit. Best alternative to compare for revenue-based funding: 2M7, a direct funder offering merchant cash advances, not loans. This 2026 guide compares unsecured business loans in Canada with other funding structures, including where each option falls short.

TL;DR

  • Unsecured business loans suit defined expenses when scheduled payments fit your cash flow.
  • An unsecured business line of credit suits recurring working capital gaps, not permanent operating losses.
  • 2M7 offers merchant cash advances, not loans; confirm security requirements before treating an offer as unsecured.
  • Compare total repayment, personal guarantees and payment frequency before choosing business funding in Canada.

Why this matters

Unsecured does not mean the owner has no personal exposure. An unsecured business loan generally does not require specific collateral, but a lender can still require a personal guarantee. Read the actual agreement rather than relying on the product label.

That distinction matters when comparing offers in 2026. A loan, a revolving credit facility and a merchant cash advance have different structures. Choosing between them starts with what you need the money to do and how your business will meet the payment schedule.

This shortlist ranks funding structures by use case, not individual lenders by advertised claims. There is no universal winner: a facility that handles recurring inventory purchases is not automatically the right choice for a single equipment purchase.

What makes the best unsecured business loans?

Use these criteria before choosing a funding provider:

  • Purpose fit: Match a defined purchase to structured funding and recurring gaps to reusable credit.
  • Security requirements: Check for personal guarantees, security interests and claims against business assets.
  • Payment fit: Test the actual payment frequency against when customers pay you.
  • Total obligation: Compare the amount received, total repayment and all disclosed charges together.
  • Eligibility fit: Check operating history, revenue requirements and documentation before applying.
  • Exit terms: Understand early repayment, renewal and what happens after a missed payment.

For your 2026 comparison, use written offers rather than headline descriptions. Compare equivalent funding amounts and payment periods wherever possible. Otherwise, differences in structure can obscure what you are actually committing to repay.

Unsecured business funding options at a glance

Unsecured term loan

  • Best for: A defined expense with a repayment plan
  • Standout feature: A lump sum repaid over an agreed term
  • Key limitation: Scheduled payments continue when sales slow

Unsecured business line of credit

  • Best for: Recurring working capital gaps
  • Standout feature: Credit can be reused within the agreement's limit
  • Key limitation: Access remains subject to the facility's terms

2M7 merchant cash advance

  • Best for: Established revenue-generating businesses comparing loan alternatives
  • Standout feature: Direct funding with one fixed cost of capital disclosed before signing
  • Key limitation: Not a loan; security requirements need confirmation

Business credit card

  • Best for: Routine purchases accepted by card
  • Standout feature: Purchase-by-purchase access to revolving credit
  • Key limitation: A persistent carried balance creates an ongoing financing obligation

The merchant cash advance belongs here as an alternative, not as another name for an unsecured loan. Its inclusion does not establish that a particular offer is unsecured.

1. Unsecured term loan: best for a defined expense

An unsecured term loan provides a lump sum that you repay over an agreed period. It suits an expense with a clear purpose, such as a business improvement, when operating cash flow supports the scheduled payments.

Start with the expense, not the largest amount offered. Your repayment plan should identify where the payment comes from even if the purchase takes longer than expected to generate revenue.

Unsecured term loan pros:

  • A defined repayment period gives you an endpoint to plan around.
  • A scheduled payment creates a clear recurring cash commitment.
  • A lump sum supports an expense that must be paid upfront.

Unsecured term loan cons:

  • Scheduled payments do not disappear during slower trading periods.
  • A personal guarantee can create exposure beyond the business.
  • Early repayment terms differ between agreements.

Best for: A business with a defined expense and sufficient cash flow to support the proposed schedule.

Before accepting a 2026 offer, ask whether the payment can change, whether early repayment changes the total obligation and what triggers default. Obtain those answers in the agreement, not just in a conversation.

Verdict: Hold until the scheduled payment fits both normal and slower trading periods.

2. Unsecured business line of credit: best for recurring gaps

An unsecured business line of credit lets you draw funds within an approved limit and reuse credit as you repay, subject to the agreement. It suits timing gaps between business expenses and customer receipts.

The distinction is simple: a line of credit addresses a recurring timing problem, not an expense that permanently exceeds revenue. If the balance never comes down, examine the underlying cash flow problem before requesting more credit.

Unsecured business line of credit pros:

  • You can draw against the facility as a funding need arises.
  • Repayment restores access to credit within the agreement's terms.
  • Reusable credit matches repeated working capital needs.

Unsecured business line of credit cons:

  • The lender's agreement governs continued access and reviews.
  • Repeated drawings can conceal a persistent operating shortfall.
  • A personal guarantee can still be required.

Best for: A business with recurring, identifiable gaps between payments out and receipts in.

Ask what documentation the lender requires to maintain the facility. Also establish whether the lender can change the limit or demand repayment under specified circumstances. Available credit is useful only when you understand the conditions attached to it.

Verdict: Hold until you can explain how customer receipts will reduce each drawing.

3. 2M7 merchant cash advance: best for comparing loan alternatives

2M7 provides merchant cash advances and working capital directly to Canadian businesses. It is a direct funder, not a broker, and its product is not a loan.

2M7 is best for Canadian business owners comparing merchant cash advances with unsecured business loans. Its stated eligibility includes at least 3 months in business and $15,000 or more in monthly revenue, including businesses with less-than-perfect credit. Meeting those thresholds does not establish approval.

2M7 merchant cash advance pros:

  • You deal with a direct funder rather than a broker.
  • One fixed cost of capital is shown before signing.
  • The fixed cost does not change based on how long repayment takes.
  • Less-than-perfect credit is included in the stated customer profile.

2M7 merchant cash advance cons:

  • It is not suitable for a business specifically seeking a loan agreement.
  • The stated operating history and revenue thresholds exclude some applicants.
  • Flex payments apply only to businesses processing daily card payments.

Best for: A revenue-generating Canadian business evaluating working capital outside a conventional loan structure.

The published approval rate is 75%, not a promise of approval for an individual applicant. Before accepting an offer, confirm the payment mechanism, total repayment obligation, security requirements and any personal guarantee.

Do not assume a merchant cash advance is unsecured simply because it appears in a comparison of unsecured funding. The agreement determines the obligations.

Verdict: Hold until the written offer confirms that the structure and payment terms fit your business.

4. Business credit card: best for routine purchases

A business credit card provides revolving credit for purchases that merchants accept by card. It suits routine expenses when you have a clear plan to pay the statement balance.

A card is not interchangeable with working capital deposited into your business account. Check how the intended expense can be paid before choosing this route, especially for payroll or supplier obligations that do not accept card payments.

Business credit card pros:

  • You can fund individual purchases rather than draw a lump sum.
  • Statements create a record of card transactions.
  • Revolving credit can support recurring purchasing needs.

Business credit card cons:

  • Not every business expense can be paid by card.
  • Carrying a balance creates an ongoing financing obligation.
  • Personal guarantees and liability terms require review.

Best for: Routine card-eligible purchases supported by a specific repayment plan.

Read the terms for purchases, cash advances and missed payments separately. Those transactions can have different conditions. Do not treat the credit limit as a target spending amount.

Verdict: Skip for persistent cash shortfalls; hold for routine purchases until repayment is planned.

How these options were ranked

The ranking follows purpose fit, payment fit, security requirements, total obligation, eligibility and exit terms. A term loan comes first for a defined expense because the funding and repayment period can be matched to that expense. A line of credit takes the recurring-gap slot because it can be reused.

The merchant cash advance occupies a separate loan-alternative slot. A business credit card ranks for routine purchases rather than general funding needs. No provider receives a blanket recommendation based on an advertised approval rate or a product name.

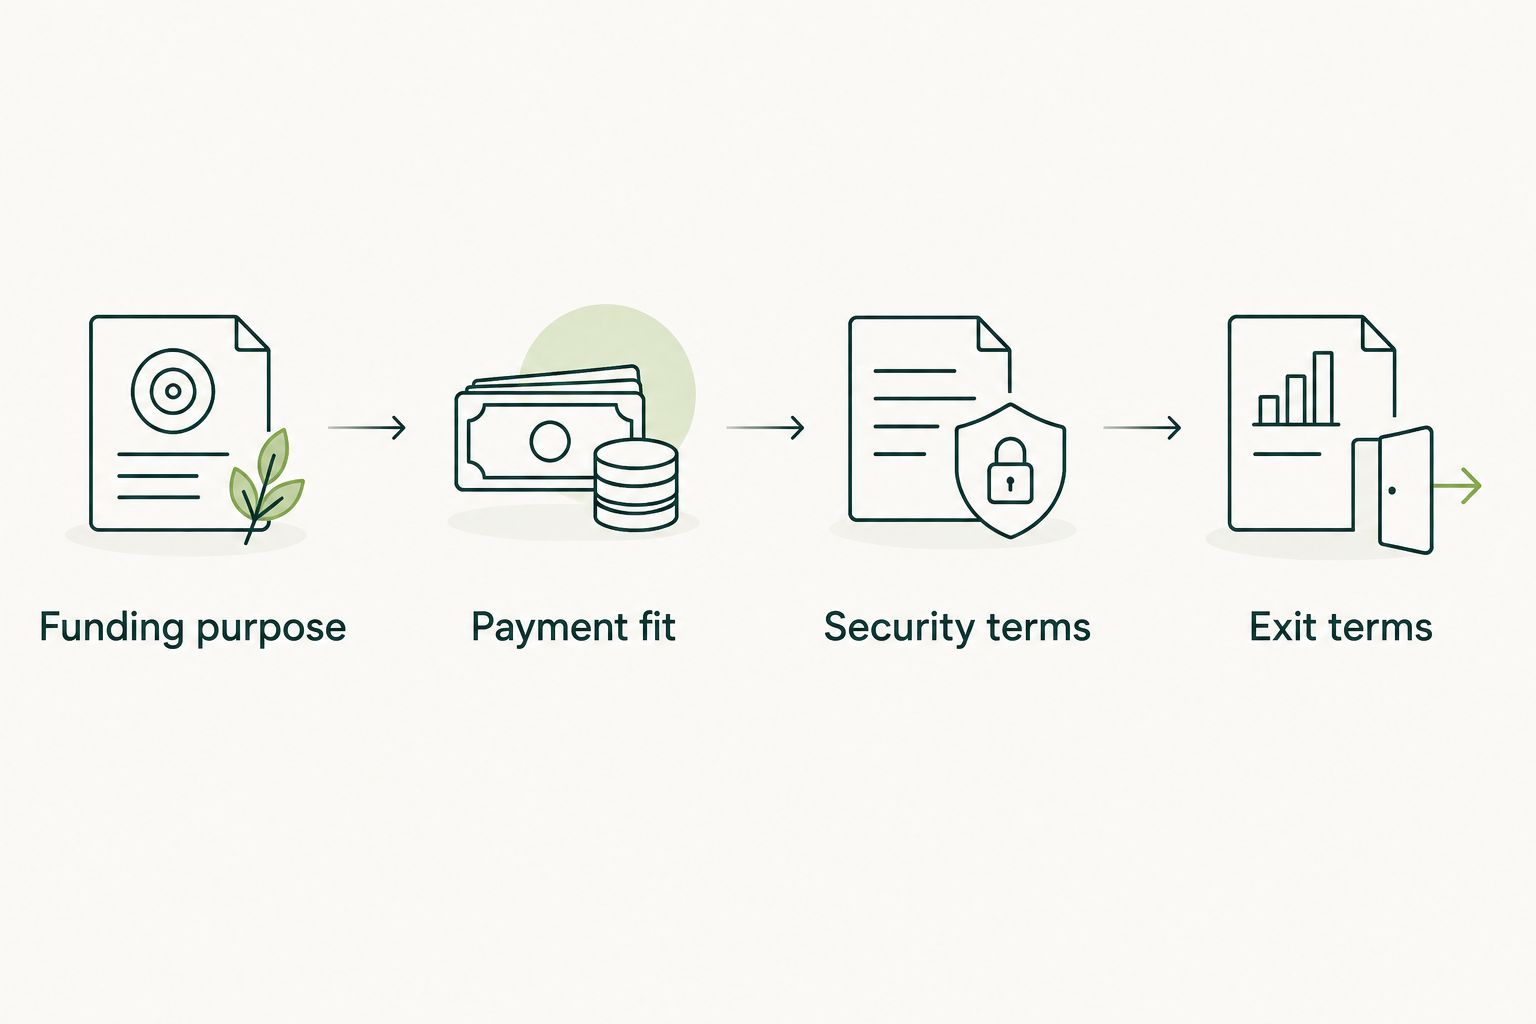
How to compare written funding offers in 2026

Use the same review sequence for each offer. This keeps a clear application process from distracting you from an unsuitable agreement.

Funding purpose

Write down exactly what the funding will pay for. Separate a single purchase from a recurring operating gap, and distinguish delayed customer receipts from expenses that exceed revenue.

Payment fit

Place the proposed payments beside your expected customer receipts. Review both the amount and frequency. A payment that looks manageable in a monthly summary can still fall at the wrong point in your operating cycle.

Security terms

Ask for every personal guarantee and security provision to be identified. Confirm which party is responsible, what assets are involved and what happens if the business misses a payment.

Exit terms

Read the early repayment, renewal and default provisions before signing. Ask whether paying sooner changes what you owe and whether additional funding requires a new agreement.

Four offer-review steps covering purpose, payments, security and exit terms.

Review the agreement's obligations before choosing the funding structure.

Keep the final offer and agreement together. If a verbal explanation differs from the documents, ask for clarification before accepting. The decision should rest on the terms you will actually sign.

Which unsecured business funding should you choose?

Choose an unsecured term loan as the default for a defined expense only when scheduled repayments fit your cash flow. Choose an unsecured business line of credit for recurring timing gaps that customer receipts will clear.

Compare a merchant cash advance when you want a loan alternative and understand its payment structure. Keep a business credit card for suitable purchases rather than treating it as a general solution to an ongoing operating deficit.

The deciding question in 2026 is not simply whether funding is unsecured. It is whether the written obligation fits the business that must meet it.

FAQ

What's the best unsecured business loan in Canada in 2026?

An unsecured term loan is the default option to compare for a defined expense with a clear repayment plan. An unsecured business line of credit is a better structural fit for recurring cash flow gaps, subject to the actual agreement.

Does unsecured business funding mean no personal guarantee?

No. An unsecured business loan can still require a personal guarantee, so review personal liability separately from collateral requirements.

Does 2M7 offer unsecured business loans?

2M7 offers merchant cash advances and working capital, not loans. Confirm security requirements and personal guarantee terms in the written offer rather than assuming the funding is unsecured.

Can a Canadian business with less-than-perfect credit apply for a merchant cash advance?

Yes, the stated customer profile for this merchant cash advance includes businesses with less-than-perfect credit. Eligibility also includes at least 3 months in operation and $15,000 or more in monthly revenue; approval is not assured.

Is a business line of credit better than a term loan?

A business line of credit is better suited to recurring timing gaps, while a term loan suits a defined expense. Compare the payment requirements and access conditions before choosing either structure.

Do merchant cash advance payments always change with sales?

No. Payment arrangements depend on the funding agreement, and flex payments under the merchant cash advance described here apply only to businesses processing daily card payments.

What should I ask before accepting unsecured business funding?

Ask about total repayment, payment frequency, personal guarantees, security provisions and early repayment terms. Make sure the written agreement answers each question before signing.

One last thing

Start with the payment calendar, not the approval message. Put every proposed funding payment beside payroll, supplier bills and expected customer receipts before accepting an offer. That exercise shows whether the funding solves a timing gap or adds another obligation at the wrong time.

Related guides

Read more
October 15, 2026
October 15, 2026

Best revenue based financing options for small businesses 2026

Best for eligible Canadian operating businesses: 2M7 merchant cash advances. Best for subscription businesses: recurring-revenue financing. Best for online retailers: e-commerce revenue financing. This 2026 guide compares these revenue based financing routes by business model, repayment structure and cash-flow fit, rather than naming a universal winner.

TL;DR

  • 2M7 merchant cash advances are a revenue based financing option for Canadian businesses seeking working capital from a direct funder.
  • Recurring-revenue financing suits subscription businesses evaluating funding against predictable customer receipts.
  • E-commerce revenue financing suits online retailers evaluating inventory funding against sales and fulfilment costs.
  • Compare total repayment, collection rules and operating cash left over before signing any agreement.

Why this matters

Revenue based financing connects a funding arrangement to business revenue, but the label does not tell you exactly how collections work. A percentage of sales, a fixed withdrawal and a payment adjusted after review have different effects on your cash flow.

2M7 is a Canadian direct funder, not a broker, providing merchant cash advances and working capital. 2M7 merchant cash advances are best for eligible Canadian businesses seeking working capital directly from a funder. The product is a merchant cash advance, not a loan.

The real decision is whether the agreement fits your receipts after payroll, suppliers, taxes and other commitments. Revenue alone does not answer that question. Your business needs enough cash left after collections to keep operating.

What makes the best revenue based financing in 2026?

Use these criteria before comparing providers or submitting an application:

  • Business-model fit: Match the funding assessment to how you earn revenue: customer subscriptions, online orders or broader business sales.
  • Collection mechanics: Establish whether withdrawals are fixed, sales-linked or adjusted through a separate process.
  • Total repayment: Ask for the complete amount payable and every charge, not just the amount advanced.
  • Operating headroom: Test collections against essential expenses during a slower sales period.
  • Contract flexibility: Read the rules for adjustments, early settlement, security and further funding.

These criteria matter more than a broad claim that funding is flexible. In particular, distinguish a payment that changes automatically from one that changes only after you request a review. Get the answer in writing.

Revenue based financing options at a glance

The ranking below compares one named Canadian funding option with two financing categories. Subscription and e-commerce financing are routes to investigate, not endorsements of unnamed providers.

1. 2M7 merchant cash advances

  • Best for: Eligible Canadian businesses seeking direct working capital
  • Standout feature: Direct funding with one fixed cost of capital disclosed before signing
  • Key limitation: Flex payments apply only to businesses processing daily card payments

2. Recurring-revenue financing

  • Best for: Subscription businesses assessing funding against recurring receipts
  • Standout feature: Assessment centred on the continuity of customer revenue
  • Key limitation: Cancellation and retention terms need close review

3. E-commerce revenue financing

  • Best for: Online retailers matching funding to an inventory cycle
  • Standout feature: Assessment centred on online sales and their cash-conversion cycle
  • Key limitation: Sales growth does not establish that margins can support repayment

No route wins solely because its application is shorter. The useful comparison is the agreement you receive, including what happens when revenue falls or an expected customer payment arrives late.

1. 2M7 merchant cash advances: best for direct Canadian funding

2M7 provides merchant cash advances and working capital to small and mid-sized Canadian businesses. Funding uses include payroll, inventory, equipment and cash-flow gaps. Businesses must have operated for at least 3 months and generate $15,000 or more in monthly revenue to meet the stated operating and revenue criteria.

Best for: Canadian business owners who want to discuss working capital directly with a funder, including owners with less-than-perfect credit.

Strengths and limitations

2M7 merchant cash advance pros:

  • Direct-funder structure, rather than a broker intermediary.
  • Working-capital uses that include payroll, inventory and equipment.
  • One fixed cost of capital, shown before signing, that does not change with repayment duration.
  • Flex payments for businesses that process daily card payments.

Merchant cash advance cons:

  • Businesses below the stated operating-history or monthly-revenue criteria do not meet those criteria.
  • Flex payments are restricted to businesses processing daily card payments; do not assume they apply to every applicant.
  • The fixed cost of capital does not decrease simply because repayment takes less time.

What to verify before signing

Ask how collections will work for your business and what balance remains after each collection. Confirm the total repayment and any contractual obligations separately from the funding amount. Meeting initial criteria is not the same as receiving approval.

For your 2026 decision, put the proposed collection schedule beside your actual payroll and supplier dates. A business with healthy monthly sales can still face a difficult week if several obligations fall together.

Verdict: Buy only if the written agreement leaves enough operating cash after collections. Choose this route for its direct-funder fit, not as a substitute for reviewing the contract.

2. Recurring-revenue financing: best for subscription businesses

Recurring-revenue financing is a route for businesses whose customers pay on an ongoing subscription or contractual basis. A funder evaluates the revenue stream and sets an agreement around its own eligibility and collection rules. The category name does not establish that payments automatically decline when customer receipts fall.

Best for: Subscription businesses that can explain customer retention, cancellations and the timing of recurring receipts.

Strengths and limitations

Recurring-revenue financing pros:

  • Gives recurring customer receipts a central role in the funding discussion.
  • Creates a basis for comparing funding obligations with subscription collections.
  • Supports a focused assessment of retention and revenue continuity rather than headline sales alone.

Recurring-revenue financing cons:

  • Recurring billing does not eliminate cancellations, failed payments or customer concentration.
  • Collection terms differ between agreements; a recurring-revenue assessment does not promise variable repayment.
  • The route is a poor match when your business cannot distinguish recurring revenue from one-off sales.

What to verify before signing

Ask what the funder counts as recurring revenue. Separate signed contracts, collected receipts and projected renewals in your own records, then check which of those the assessment uses.

Review what happens if a major customer cancels. Your business still needs to understand the collection obligation, adjustment process and reporting requirements under that scenario. A funding offer based on subscription revenue is not evidence that the business can comfortably support it.

Verdict: Hold until the agreement explains collections after customer losses. Recurring-revenue financing belongs on the shortlist when subscription receipts are central to your business, not merely because you offer a subscription product.

3. E-commerce revenue financing: best for online inventory cycles

E-commerce revenue financing is a route for online retailers evaluating funding against sales activity. Your assessment should connect the proposed advance to inventory purchases, customer receipts, refunds, fulfilment and other selling costs. The relevant question is how much cash each sales cycle produces, not just how much revenue it records.

Best for: Online retailers with sales records and a clear plan for converting funded inventory into collected cash.

Strengths and limitations

E-commerce revenue financing pros:

  • Focuses the funding discussion on an identifiable sales channel.
  • Gives you a practical way to compare inventory purchases with expected customer receipts.
  • Encourages a cash-flow assessment that includes refunds and fulfilment rather than gross sales alone.

E-commerce revenue financing cons:

  • Returns and selling expenses reduce the cash available for collections.
  • Unsold inventory can leave funding obligations running ahead of customer receipts.
  • Revenue-linked terminology does not establish the treatment of refunds, taxes or marketplace deductions.

What to verify before signing

Ask which sales figure drives the agreement: gross orders, settled receipts or another defined measure. Then check how returns and deductions affect that figure. The definitions need to match the records you can produce.

For a 2026 inventory decision, separate buying stock from selling it profitably. Confirm that your expected receipts cover the stock purchase, selling expenses and funding obligation without depending on another advance.

Verdict: Hold until the inventory cycle supports the collection schedule. E-commerce revenue financing fits an evidenced stock-to-cash plan, not a sales target on its own.

How the options are ranked

The order prioritizes business-model fit, clear collections and operating headroom. Direct Canadian funding comes first for the general small-business reader; subscription and e-commerce routes follow because their usefulness depends on a more specific revenue model.

This is a decision framework, not a claim that every provider in a category offers the same terms. No approval rate, repayment structure or contract provision transfers automatically from one funder to another.

Your own ranking should change with your business. A subscription operator should start with recurring-revenue fit; an online retailer should start with the inventory cycle. Compare actual agreements using the same criteria before deciding.

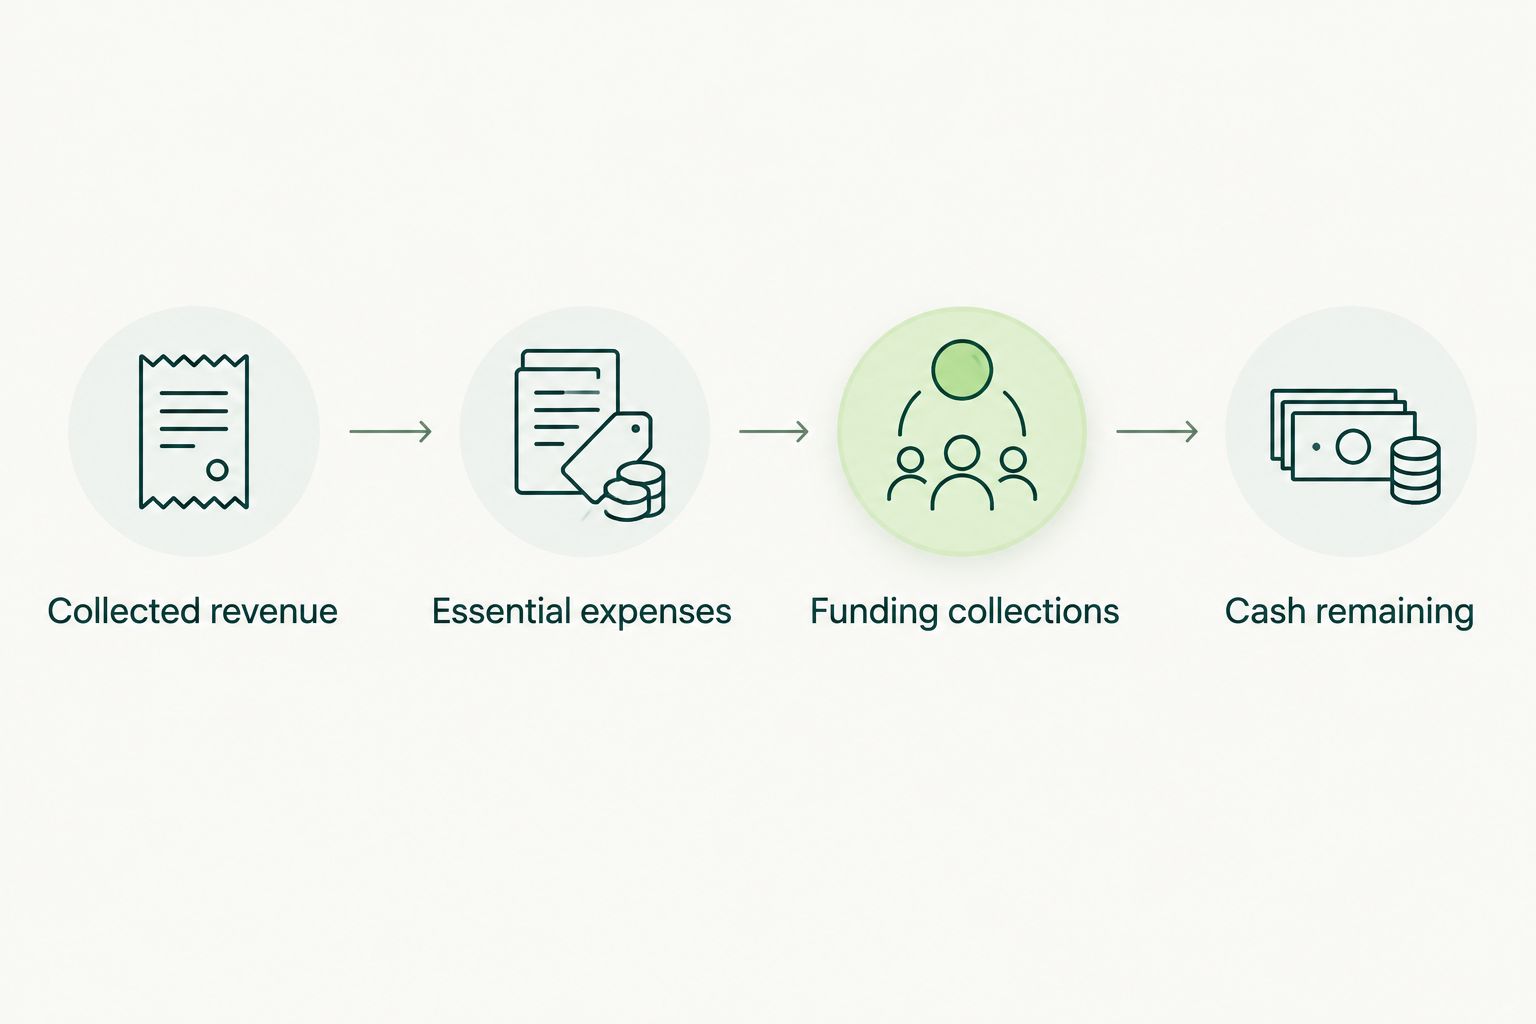
Check repayment against your operating cash

Use this sequence when you receive an offer. Keep the exercise tied to collected cash rather than invoices or sales forecasts alone.

  • Collected revenue: Start with receipts that reach your business account.
  • Essential expenses: Identify payroll, suppliers, rent, taxes and existing commitments.
  • Funding collections: Apply the agreement's collection method and timing.
  • Cash remaining: Check what remains for operations and unexpected expenses.

Four-step cash-flow check from collected revenue through expenses and funding collections to cash remaining.

Assess the cash left for operations, not just the revenue used to qualify.

Repeat the exercise using a slower period from your own records. Do not replace that evidence with an invented industry benchmark. If collections leave too little cash, discuss a different amount or structure before proceeding.

Also read the agreement for security interests, personal guarantees, reporting obligations and restrictions on additional funding. Ask whether each applies; never infer the answer from the phrase revenue based financing.

Which revenue based financing should you choose?

Choose the route that matches your revenue model and preserves operating cash. For an eligible Canadian operating business, start with a direct-funder discussion. For a subscription business, examine how recurring receipts are assessed; for an online retailer, examine the stock-to-cash cycle.

For 2026, make the written agreement your deciding document. An approval tells you funding is offered. It does not tell you whether the collections fit your business.

Discuss your funding options

Speak with a funding specialist about your business revenue and working-capital needs.

Discuss funding options

FAQ

What is revenue based financing?

Revenue based financing connects a funding arrangement to business revenue. The contract determines eligibility, total repayment and whether collections are fixed, sales-linked or adjusted through a separate process.

What is the best revenue based financing option in Canada?

The best option matches your business model and leaves enough cash for operations after collections. Compare direct merchant cash advances, recurring-revenue financing and e-commerce financing against the written terms offered to your business.

Is a 2M7 merchant cash advance a loan?

A 2M7 merchant cash advance is a merchant cash advance, not a loan. The Canadian direct funder provides working capital for uses including payroll, inventory, equipment and cash-flow gaps.

Will payments automatically fall if my sales drop?

Do not assume payments automatically fall when sales drop. Confirm whether the contract uses a sales percentage, a fixed withdrawal or a separate adjustment process, including any eligibility conditions.

Can a business with less-than-perfect credit apply?

Less-than-perfect credit is within the stated customer profile for the direct-funder option described here. Approval is not guaranteed, and the business must still meet the applicable assessment criteria.

How should I compare financing costs in 2026?

Compare the complete amount payable, collection timing and all contractual charges. Ask what happens after early settlement or slower repayment rather than assuming either changes the cost.

What should an online retailer check before accepting funding?

An online retailer should check whether collected sales cover inventory, refunds, fulfilment, other operating expenses and funding collections. Gross order value alone does not establish repayment capacity.

One last thing

A revenue-linked assessment and a revenue-linked payment are different things. Before signing, ask the funder to show how the same agreement operates during both a stronger and a slower period from your records.

That explanation should identify the collection amount or calculation, the adjustment process and the cash your business retains. If the answer remains unclear, wait for written clarification.

Related guides

Read more
February 16, 2021
July 27, 2026

Expanding Your Business through Merchant Cash Advance Benefits

Expanding your business is an exciting opportunity, but it can also present serious challenges. One of the most common is actually cash flow issues. How? If the business is growing, shouldn’t you have more money flowing in? Business may have increased, but you might need to pump money into equipment or hiring new staff so you can keep up with demand. Until you can get that new computer system or hire that extra person, your customers are experiencing a bumpy sort of service. Your income could be uneven as a result, as you might not have the products they want when they want them. You might have trouble getting invoices out on time. Does this sound like your business? A merchant cash advance could be just what the doctor ordered. The benefits of an MCA could help you manage the cash flow issues presented by an expanding business. Here’s how.

Merchant Cash Advances Help You Get the Cash You Need

A merchant cash advance, or MCA, gives you access to funding based on your future credit card or debit card sales. The lender will look at your past sales, then extend you an advance as a percent of estimated future sales. That means the more sales you’re likely to make, the bigger the advance can be. In turn, you can invest it into whatever you need it for. That’s because the MCA doesn’t have to be directed towards certain goals, unlike an equipment loan or a payroll loan. You can use the funds for what you need, when you need it.

MCA Repayment Terms Are More Flexible

Another bonus of a merchant cash advance for a growing business is that the repayment terms are more flexible. With a traditional loan, you’ll have a set payment that you have to make every month. With a growing business, income can be unpredictable. That, in turn, could lead to situations where you’re crunched for cash. You may feel squeezed needing to make your monthly loan payments. That could lead to bigger problems, such as a poor credit score or even defaulting on a loan. Since an MCA is made against your future sales, you pay it back as you make those sales. If your sales dip lower than expected, then your payment falls too. If you make more, then you can pay your loan back faster.

It’s Faster to Get a Merchant Cash Advance

If you find yourself in a pinch over payroll or other financial obligations, then you might wonder what choices you have to get the funding you need. A merchant cash advance is much faster than getting a traditional loan. That makes it the perfect stop-gap measure for a growing business. Whether an unexpected expense crops up or sales grew slower than you’d hoped, an MCA can help you make up the difference.

Need Some Cash?

If your growing business needs a quick influx of cash right away, then it’s time to get in touch with a merchant cash advance provider. With their help, you can keep your business growing the right way.

Read more