ClickCease

Which Industries Benefit the Most from Merchant Cash Advance?

Which Industries Benefit the Most from Merchant Cash Advance?

Which Industries Benefit the Most from Merchant Cash Advance?
4
May 2026
2
Oct 2026

According to the Canadian Federation of Independent Business (CFIB), 2025 was a divided year for Canadian small business: while 37% of owners reported a good year in terms of revenues and profits, 35% reported a poor one. The smallest firms felt it most. Among businesses with fewer than five employees, only 35% described 2025 as a good year, compared to 42% of larger firms. Tariff pressures, high operating costs, and slowing business dynamism have left many owners caught in a difficult position.

For those who have turned to the bank for help, the options are often limited. The federal government's Canada Small Business Financing Program (CSBFP) issued just 6,409 loans totalling nearly $1.9 billion in 2024-25, a record in program history. But with approximately 1.2 million small businesses in Canada, the reach of traditional financing programs remains narrow. The average CSBFP loan size was $294,067, which is far more than what most small business owners need to solve a specific, immediate cash flow problem.

A Merchant Cash Advance (MCA) is one alternative worth understanding. It is not a bank loan. It is an advance on your future revenue, repaid as a percentage of daily sales, with a single fixed cost of capital disclosed upfront. There are no interest charges, no hidden fees, and no collateral requirements.

Some industries tend to benefit from this kind of flexible, short-term working capital more than others. Below are five industries which benefit from a merchant cash advance:

1. Restaurants and Food Service

Canada's foodservice sector added nearly 24,000 jobs between January and November 2025 according to Restaurants Canada, a sign that demand is holding up. Growth, however, requires capital, and restaurant revenue is inherently unpredictable. Equipment needs replacing without warning. A slow season can erode a cash position that looked healthy a few months earlier. Traditional lenders typically want two or more years of financial history and strong collateral before approving financing, which many independent restaurant owners cannot provide.

A merchant cash advance can provide working capital in the range of $5,000 to $300,000, with approval typically within one business day and funds deposited within 24 hours. Because repayments are tied to a percentage of daily sales, owners pay more when business is strong and less when it slows. This structure suits the seasonal and variable nature of restaurant revenue better than a fixed monthly payment.

One restaurant owner who used 2M7 funding for a kitchen equipment upgrade described the experience this way: "Highly recommend 2M7 if you are planning any big purchases. They helped us get funding for the new kitchen equipment and we continue to upgrade our facility."

2. Construction and Trades

Construction businesses routinely face a timing problem: materials, equipment, and labour costs arrive before client payments do. Payment terms of 30, 60, or even 90 days are common, which means contractors are often funding project costs out of their own cash flow while waiting for invoices to clear. Banks are generally reluctant to lend against this kind of irregular, project-based revenue, which leaves many contractors with limited options when they need capital quickly.

A merchant cash advance can help bridge the gap between project start and payment receipt, allowing contractors to cover immediate costs without waiting on a lengthy approval process or pledging personal assets.

Sean Morales, who needed funding for a demolition project, noted: "We need funds for a demolition project for our office. These guys got it done in less than 24 hrs."

More information on how working capital applies to the construction sector is available on 2M7's construction and trades funding page.

3. Retail and E-Commerce

Canadian e-commerce orders rose 20% in 2025 according to Omnisend, reflecting continued growth in both online and in-store retail. Sustaining that growth requires inventory investment well ahead of actual sales. Retailers need to order stock months before peak seasons, and suppliers often require payment before goods are delivered. A bank approval process that takes weeks is rarely compatible with those timelines.

Merchant cash advances allow retailers to access the capital they need for inventory, seasonal staffing, or store improvements without lengthy documentation requirements or the need to pledge collateral.

Morgan Lowe, a boutique retailer who used an MCA to expand her store, said: "I am a small business owner that just recently expanded and was struggling to find funding. 2M7 came through and has been wonderful to deal with."

For businesses where inventory is the core challenge, the impact can be ongoing. Visionary Hydroponics noted: "We are a small business and maintaining inventory can be a challenge. These types of [advances] help keep product on the shelf."

Details on how 2M7 works with retailers are available on the retail inventory and growth funding page.

4. Trucking and Transportation

BMO's Fall 2025 Canada Truck Transportation update describes the Canadian trucking industry as still in a fragile state, with trade barriers and tariff uncertainty continuing to weigh on domestic and cross-border freight volumes, rates, and fleet fundamentals. For owner-operators and small fleets, this means running lean while still needing to cover fuel, maintenance, and payroll between loads.

Traditional financing in this sector often requires an established credit history and years of documented revenue, which can be difficult to demonstrate during a period of industry-wide softness. A merchant cash advance offers a more accessible path to short-term working capital, with repayments that adjust alongside revenue rather than remaining fixed regardless of conditions.

More detail on how this applies to transportation businesses is available on 2M7's trucking funding page.

5. Landscaping and Seasonal Businesses

Seasonal businesses face a structural cash flow challenge that most financing products are not designed for. Revenue arrives in concentrated bursts, while costs related to insurance, equipment upkeep, and preparing for the next season continue year-round. A lender evaluating a landscaping company's winter financials will often see a picture that looks worse than the underlying business actually is.

The CFIB's December 2025 survey found that smaller firms are the most vulnerable to sudden cost pressures and disruptions. For seasonal operators, that kind of pressure is predictable and recurring rather than exceptional.

A merchant cash advance with flexible repayment can work with this pattern rather than against it. When revenue is strong in peak season, repayments reflect that. When it drops in the off-season, repayments decrease proportionally. Owners are not locked into a fixed payment schedule that ignores the realities of how their business operates.

Who Qualifies

Businesses interested in a merchant cash advance through 2M7 need to meet a straightforward set of criteria:

  • The business is located in Canada
  • The business has been operating for at least 3 months
  • Monthly revenue is at least $15,000
  • There are no open bankruptcies

No collateral is required. Approval decisions take into account overall revenue and business activity, not credit score alone.

How Repayment Works

2M7 offers two repayment structures. Fixed payments mean the same amount is debited on a regular schedule, with the option to request a reduction if revenue drops significantly. Flex payments are tied directly to a percentage of daily sales, so repayment amounts naturally rise and fall with business activity. The flex option is available to businesses that process daily credit and debit transactions.

Before signing, the total cost of capital is presented clearly. There are no origination fees, application fees, interest charges, brokerage fees, annual maintenance fees, or early repayment penalties. The cost disclosed upfront is the only cost.

Once a business is an existing client, requesting additional funding is straightforward. Clients can contact their dedicated representative directly by phone or text, and if approved, funds can be deposited within 30 minutes.

What Business Owners Have Said

"2M7 greatly guided us through the entire process of funding for our small business. We're extremely pleased with their clear explanations of what to expect and their steady commitment to helping us." -- Kotryna Zis

"Had the pleasure of dealing with 2M7 and Yakov, who helped our business get approved with funds in my account the next day. Greatly appreciate their help. Everything that we talked about was provided." -- Brady Douglas

"2M7 has been so wonderful to work with. Every employee I speak with is incredibly helpful and kind. I would never have been able to get back on my feet after COVID-19 if not for them." -- Jenny Watson

Is a Merchant Cash Advance Right for Your Business?

A merchant cash advance is not the right fit for every situation. It works best for businesses that have consistent revenue, need capital quickly, and want repayment terms that reflect how their business actually performs rather than a fixed schedule set by a lender.

Canada's government financing programs reached fewer than 6,500 businesses last year in a country with over a million small businesses. For many owners who fall outside the criteria those programs require, alternative working capital solutions are worth exploring.

If your business is based in Canada, has been operating for at least three months, and brings in at least $15,000 per month in revenue, you can check your eligibility with 2M7 without a lengthy application process.

Related reading: What is a Merchant Cash Advance? 2M7 vs. Other Merchant Cash Advance Options The Truth About Small Business Loans 5 Low-Cost Ways to Market Your Small Business in Canada

Sources: CFIB: A Divided Year, Small Business Performance in 2025 ISED: Canada Small Business Financing Program, Overview and Highlights 2024-25 Retail Insider / Restaurants Canada: Foodservice sector added nearly 24,000 jobs in 2025 BMO: Industry Update, Canada Truck Transportation, Fall 2025 Retail Insider / Omnisend: Canadian E-Commerce Orders Rose 20% in 2025

‍

Related articles

January 18, 2021
July 27, 2026

How Do I Get a Cash Advance

You’ve done your research, and you’re convinced a merchant cash advance is a great opportunity for your business. You can get a flexible funding solution to help you cover essential business costs or even expansion. Better yet, you can quickly access the funds you need with flexible repayment terms. So, how do you get an MCA? Follow these steps and you’ll have the funding you need in no time.

Research Providers

Doing research should be your first step. There are plenty of lenders offering MCAs, but not all of them are created equal. Many of them do business online. This makes it easy to find information about where they operate and the kinds of businesses they support. Some specialize in working with small businesses, while others prefer working with large businesses. Some may have expertise in your industry. Always look for a provider who is upfront about their MCA program. Check customer reviews and testimonials. What do other business owners say about this lender?

Submit an Application

Once you’ve decided on a provider, it’s time to prepare your MCA application. Always review the lender’s specific requirements. The more complete and accurate your application, the faster the lender can approve you. You’ll need to provide:

  • Government-issued ID, to prove your identity
  • Your merchant ID number
  • Recent bank statements
  • A void cheque

Your merchant ID number allows the lender to check on your merchant account, giving them accurate information on your monthly sales. Your recent bank statements can also provide this information, as well as crucial information about cash flows. You’ll also need to provide a bank account number for your business. The business bank account is where your merchant cash advance will be deposited.

The Approval Process

The lender will approve your application within two business days. If your application is complete and accurate, the funds may arrive on within the same day. Always check what the lender will provide. Some lenders will offer up to 125 percent of your monthly sales. Next, they’ll send you an agreement. Read this over carefully, since it contains information about your repayment schedule, fees, and more. Some lenders post their general terms, including rates and fees, online. You can review them before you apply. If you’re unsure about the lender’s offer, don’t be afraid to contact them. For example, if you were hoping for more funds than they offered, you can discuss their rationale with them. Once you’re satisfied with the lender’s terms, your funds will be transferred to your bank account.

How Repayment Works

Your merchant cash advance provider should get in touch with your payments processor. They’ll set up direct deductions, which means repayment of your advance happens automatically. You can keep track of payments through your account with the provider. This makes the process perfectly transparent, and you’ll always know where you stand.

Get the Funds You Need Now

Ready to get a merchant cash advance for your business? You can get in touch with the experts for a free quote or apply now. The funds you need could be just a few clicks away.

Read more
October 19, 2026
October 19, 2026

Best business lines of credit for small businesses in Canada 2026

Best overall for collateral-backed borrowing: a secured business line of credit. Best without pledged business assets: an unsecured line. Best alternative for eligible businesses comparing merchant cash advances: 2M7, a direct funder, not a line-of-credit provider. This 2026 guide ranks funding structures by business need rather than naming a bank winner without comparable offers.

TL;DR

  • A secured business line of credit suits established businesses willing to pledge acceptable collateral.
  • An unsecured business line of credit avoids specified collateral, but personal guarantees can still apply.
  • Receivables-backed credit suits businesses with eligible unpaid customer invoices.
  • 2M7 offers merchant cash advances, not revolving credit; compare the repayment structure before choosing.

What makes the best business line of credit?

  • Reusable access: You can draw, repay and borrow again within the approved limit, subject to the agreement.
  • Cash-flow fit: Required payments leave enough money for payroll, suppliers and taxes.
  • Clear obligations: You understand interest, fees, guarantees and collateral requirements.
  • Usable capacity: The amount actually available matches your operating needs.
  • Acceptable conditions: Reporting, renewal and cancellation terms fit how your business operates.

Business credit options at a glance

1. Secured business line of credit

  • Best for: Established businesses with acceptable collateral
  • Standout feature: Revolving access supported by pledged assets
  • Key limitation: Collateral is exposed if you default

2. Unsecured business line of credit

  • Best for: Businesses seeking credit without specified pledged assets
  • Standout feature: Revolving access without designated collateral
  • Key limitation: A personal guarantee can still apply

3. Receivables-backed line of credit

  • Best for: Businesses selling to customers on payment terms
  • Standout feature: Borrowing availability tied to eligible invoices
  • Key limitation: Availability changes with receivables eligibility

4. 2M7 merchant cash advance

  • Best for: Eligible businesses considering an alternative to revolving credit
  • Standout feature: Direct funding for working-capital needs
  • Key limitation: Not a reusable credit facility

Why this matters

A business line of credit addresses a timing problem: expenses arrive before customer payments, and you need access to funds between the two. A revolving facility lets you borrow again after repayment, subject to its terms. A merchant cash advance works differently and should not be treated as an interchangeable product.

For your 2026 comparison, start with the problem you need to solve. Recurring supplier payments, outstanding invoices and a defined equipment purchase call for different conversations. The best option is the one whose repayment obligations fit your cash flow, not simply the one offering the largest limit.

1. Secured credit: best for businesses with collateral

A secured business line of credit gives you revolving access to funds against collateral the lender accepts. That security can include business assets, depending on the agreement. You draw what you need within the available limit and restore borrowing capacity through repayment, subject to the facility's conditions.

Best for: Established businesses that need recurring working capital and are comfortable pledging assets.

Secured credit pros

  • Reusable borrowing suits repeated cash-flow gaps rather than a single purchase.
  • An approved facility provides access without a separate application for every draw, subject to its terms.
  • Collateral gives the lender a defined source of security when assessing the application.

Secured credit cons

  • Pledged assets are exposed if the business defaults.
  • Security requirements can complicate future financing involving the same assets.
  • Reporting obligations and lender reviews can affect continued access.

What to check: Ask exactly which assets secure the facility. A security interest covering broad business assets has different consequences from security over one identified asset. Also ask whether a personal guarantee is required; business collateral does not automatically remove personal obligations.

Do not choose secured credit just because your business owns equipment or property. First check whether pledging those assets restricts another financing arrangement you need.

Verdict: Hold until the collateral, guarantee and renewal terms are clear. Secured credit is the default comparison point for established businesses willing to provide security, not an automatic recommendation for every asset-owning business.

2. Unsecured credit: best without specified collateral

An unsecured business line of credit provides revolving access without specified pledged collateral. The lender still evaluates the business and the application. Unsecured does not mean approval without underwriting, and it does not necessarily mean the owner has no personal responsibility.

Best for: Businesses seeking reusable working capital without assigning specified assets as collateral.

Unsecured credit pros

  • You avoid pledging specified business assets under the facility.
  • Revolving access supports repeated borrowing and repayment.
  • Keeping assets outside a specific security arrangement can preserve flexibility for other financing discussions.

Unsecured credit cons

  • A personal guarantee can still create obligations for the owner.
  • The approved limit and application requirements depend on the lender's assessment.
  • Renewal, review and cancellation provisions still matter.

What to check: Ask the lender to explain what unsecured means in the actual agreement. Confirm whether guarantees, account conditions or other obligations apply. Do not rely on the product name alone.

For a 2026 application, compare the usable limit with your largest expected cash-flow gap. A facility that cannot cover that gap does not solve your operating problem, even if its collateral requirements are attractive.

Keep the distinction between qualification and suitability clear. Approval tells you the lender accepts the application; it does not establish that the required payments fit your business.

Verdict: Hold until you understand the personal guarantee and available limit. Choose unsecured revolving credit for its structure, not because the word unsecured sounds consequence-free.

3. Receivables-backed credit: best for unpaid invoices

A receivables-backed line of credit links borrowing availability to eligible customer invoices. The lender assesses which receivables qualify and applies the agreement's borrowing rules. This differs from receiving an unrestricted limit based only on the business's overall profile.

Best for: Businesses that invoice customers on payment terms and have receivables a lender accepts.

Receivables-backed credit pros

  • The facility connects working-capital access to unpaid customer invoices.
  • Revolving borrowing can support the gap between delivering work and collecting payment.
  • Availability can reflect changes in qualifying receivables, subject to the agreement.

Receivables-backed credit cons

  • Overdue, disputed or otherwise ineligible invoices can reduce borrowing availability.
  • Reporting and invoice administration create ongoing work.
  • Customer concentration rules can limit how much of the receivables balance qualifies.

What to check: Ask how the lender treats overdue invoices, customer disputes and sales concentrated with one customer. Then calculate borrowing availability using those rules, rather than assuming every dollar invoiced creates an equal amount of credit.

A growing invoice balance does not automatically mean more usable funding. If the additional invoices fail the eligibility rules, the facility will not expand in the way you expect.

Also distinguish a receivables-backed line from factoring. A credit facility and an arrangement involving the sale of invoices have different contractual structures. Ask who collects customer payments and what happens when a customer does not pay.

Verdict: Hold until an invoice-level review confirms usable borrowing capacity. This option fits an invoicing business only when its receivables qualify.

4. 2M7: best for comparing a merchant cash advance alternative

A merchant cash advance is an alternative funding structure, not a business line of credit. It does not give you a revolving limit that automatically replenishes after repayment. Treat it as a separate decision when your business needs working capital.

2M7 merchant cash advances suit eligible Canadian businesses comparing direct funding with revolving credit. The company is a direct funder, not a broker, serving businesses operating for at least 3 months with $15,000 or more in monthly revenue. Its stated uses include payroll, inventory, equipment and cash-flow gaps.

Best for: Eligible small and mid-sized Canadian businesses considering working capital outside a revolving credit facility, including businesses with less-than-perfect credit.

Merchant cash advance pros

  • You discuss funding with a direct funder rather than a broker.
  • The stated eligibility includes businesses with at least 3 months of operating history.
  • Working-capital uses include payroll, inventory and equipment.
  • The fixed cost of capital is disclosed before signing and does not change based on repayment duration.

Merchant cash advance cons

  • Repayment does not automatically restore a reusable credit limit.
  • Eligibility requirements still apply; meeting initial thresholds is not an approval promise.
  • Flex payments apply only to businesses processing daily card payments.

What to check: Confirm the total repayment obligation, collection method and effect on operating cash flow. If flexible payments matter to your decision, establish whether your business meets the daily card-payment condition before comparing that feature with other offers.

Verdict: Skip if you specifically need revolving credit. Consider this structure when you need defined working capital and the repayment obligations fit your business.

How to compare written offers in 2026

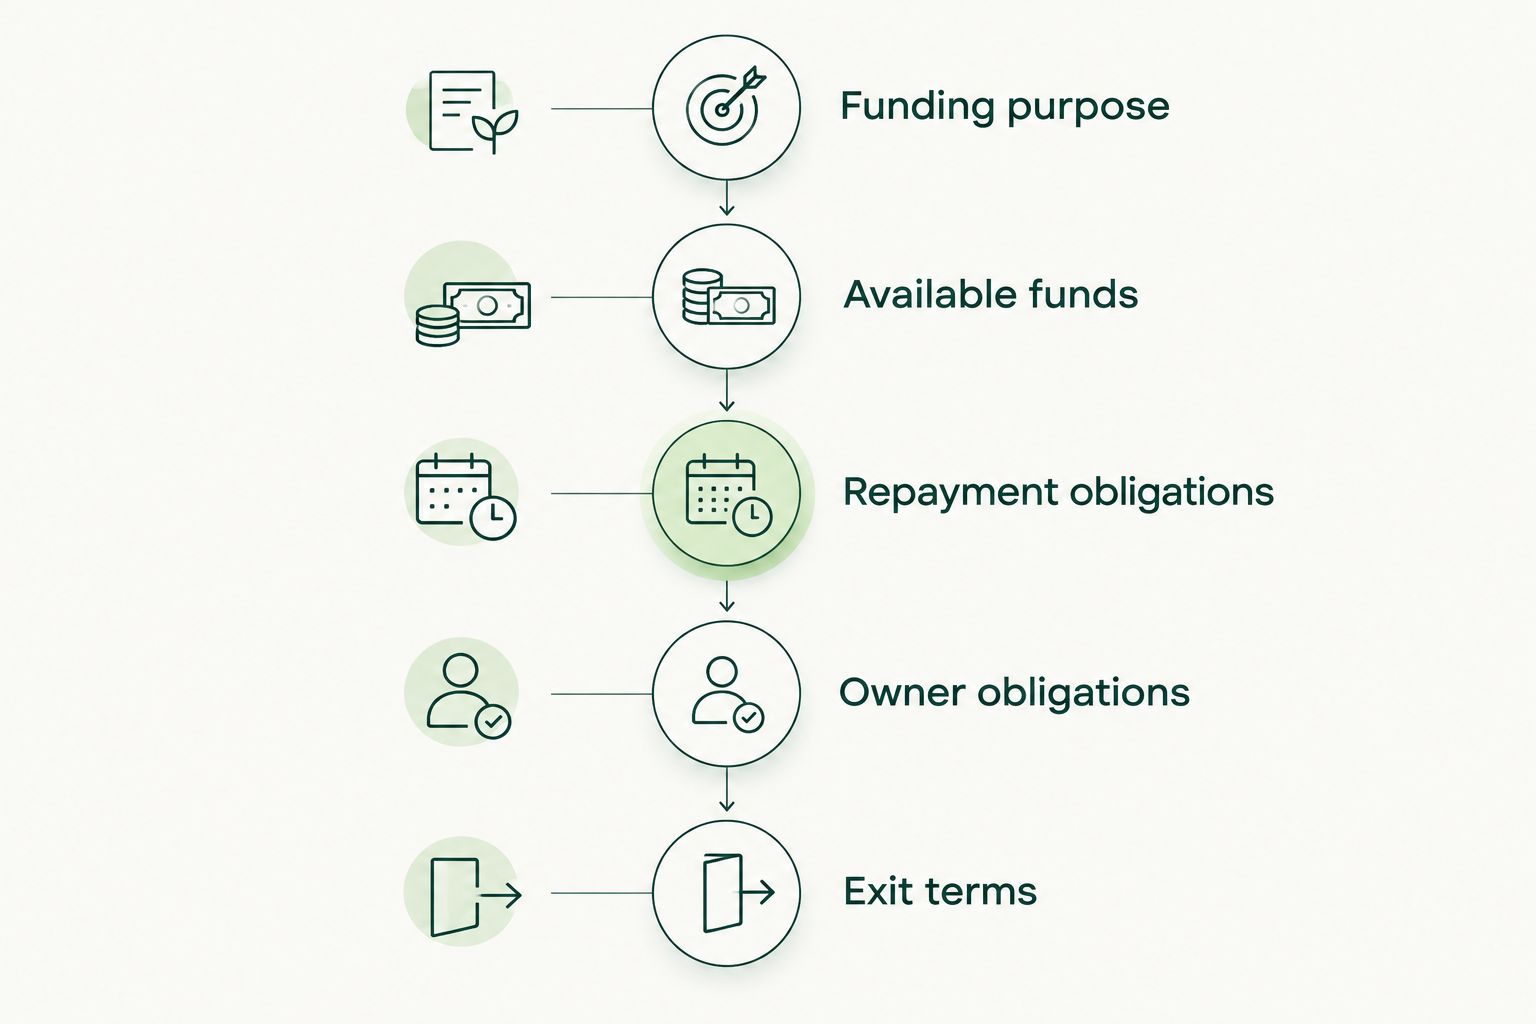
A useful funding comparison follows the money through your business. Check these elements in order before deciding which offer fits.

  1. Funding purpose: Identify the expense and whether it recurs. Separate an ongoing operating gap from a single purchase.
  2. Available funds: Confirm what you can actually draw, including restrictions tied to collateral or eligible invoices.
  3. Repayment obligations: Map required payments against expected customer receipts and essential operating expenses.
  4. Owner obligations: Identify guarantees, pledged assets and reporting duties before signing.
  5. Exit terms: Read renewal, cancellation and early-repayment provisions, including any conditions attached to them.

Do not compare a revolving credit limit directly with the amount of an advance. One describes access that can be reused under an agreement; the other describes funding that does not automatically replenish.

Five checks for comparing funding offers, from funding purpose to exit terms

Compare obligations and usable access, not just the headline funding amount.

Build your comparison from written terms rather than a headline claim. If an important condition is unclear, ask the provider to explain it before you commit. Keep the explanation with the agreement so your operating decisions reflect the same terms.

How these options are ranked

This 2026 ranking prioritises revolving access, cash-flow fit, clear obligations, usable capacity and acceptable conditions. Secured credit comes first for established businesses willing to pledge collateral; unsecured credit serves a different need, while receivables-backed credit depends on qualifying invoices.

The merchant cash advance sits separately because it is not a line of credit. This is a structure-based buying guide, not a claim that one lender offers the best terms to every Canadian applicant. Your written offer determines the final comparison.

Which business line of credit should you choose?

Start with a secured business line of credit if your established business needs reusable funding and can accept the collateral obligations. Compare unsecured credit when you want to avoid specified pledged assets. Investigate receivables-backed credit when unpaid customer invoices drive the funding gap.

If you do not need reusable access, compare a merchant cash advance separately. Ask a funding specialist to explain the repayment structure in plain language. Do not choose a non-revolving product expecting it to behave like a credit line.

Discuss your funding options

Speak with a funding specialist about working capital and whether a merchant cash advance fits your business.

Discuss funding options

FAQ

What's the best business line of credit for a small business in Canada?

The best fit depends on collateral, cash flow and the need for reusable access. Start with secured credit if you can accept asset security, unsecured credit if you want to avoid specified collateral, or receivables-backed credit if eligible invoices support the facility.

Is an unsecured business line of credit free of personal obligations?

No. An unsecured business line of credit can still require a personal guarantee. Read the guarantee and other obligations rather than treating unsecured as a promise of no personal responsibility.

Does repaying a business line of credit let me borrow again?

A revolving business line of credit generally restores borrowing availability as you repay, subject to the agreement. Limits, lender reviews and other conditions still govern what you can draw.

Is a merchant cash advance the same as a business line of credit?

No. A merchant cash advance does not provide a revolving limit that automatically replenishes after repayment. Compare its repayment obligations separately from a reusable credit facility.

Can a newer Canadian business consider 2M7 funding?

2M7 serves businesses operating for at least 3 months with $15,000 or more in monthly revenue. Those are initial eligibility criteria, not an approval promise, and its product is a merchant cash advance rather than a business line of credit.

What should I ask before signing a business credit agreement in 2026?

Ask about usable borrowing availability, repayment obligations, guarantees, collateral, reporting, renewal and cancellation. Request clarification of anything that could restrict access or affect your operating cash flow.

Is receivables-backed credit the same as invoice factoring?

No. A receivables-backed credit facility and an arrangement involving the sale of invoices have different contractual structures. Confirm invoice ownership, collection responsibilities and what happens if a customer does not pay.

One last thing

A credit limit is not the same as money you can safely spend. Before accepting any 2026 offer, place its required payments alongside payroll, tax obligations and supplier commitments. If the funding solves one payment gap but creates another, change the amount or structure before signing.

Related guides

Read more
May 18, 2026
July 26, 2026

What Lenders Look For Before Approving Small Business Funding in Canada

If you have ever sat across from a bank representative, filled out a stack of forms, and walked away empty-handed, you are not alone. Securing small business funding in Canada has become genuinely harder over the past few years. Interest rates have climbed, underwriting standards tightened, and many business owners who would have been approved without question five years ago are now facing rejection letters. That reality is frustrating, and it deserves to be named plainly before we talk about what you can actually do about it.

The good news is that understanding exactly what lenders evaluate changes the entire game. Whether you are pursuing a traditional bank loan, a Merchant Cash Advance, or another form of fast business funding, the criteria lenders use to assess your application are knowable. Here is what goes on behind the scenes.

Credit History vs. Business Health: What Actually Matters More

Personal credit scores get a lot of attention, and they do matter. But for most small business owners seeking funding outside the Big 5 banks, they are rarely the deciding factor. Alternative lenders are far more focused on the operational health of your business than they are on a three-digit number pulled from your credit bureau file.

The reason is simple: a lender who advances capital against your future revenue wants to know whether that revenue is real, consistent, and growing. A credit score tells them about your past borrowing behaviour. Bank statements tell them whether your business can actually repay what it borrows.

That said, a damaged personal credit history can still complicate your application, particularly when it comes to interest rates and loan structures. If you are worried that your credit history might disqualify you, you can read more about how to get a business loan with a bad credit score to see what other options are available.

The Big 5 Banks vs. Alternative Lenders: Understanding the Friction

Canada's major chartered banks operate under regulatory frameworks that require them to be conservative. Their approval processes are designed for businesses with established revenue, years of audited financials, strong personal credit, and collateral. For many small business owners, especially those in their first few years of operation, those requirements create a wall that is genuinely difficult to climb.

Alternative lenders exist precisely because that wall has left a large segment of the Canadian small business market underserved. Products like Merchant Cash Advances, revenue-based financing, and short-term small business loans were built for businesses that have real cash flow but do not fit a bank's rigid profile. The approval timelines are shorter, the documentation requirements are more practical, and the underwriting process is designed to assess your actual business rather than compare you to an institutional checklist.

This does not mean alternative lending is without scrutiny. Reputable alternative lenders still evaluate your application carefully. But the criteria they use tend to be more relevant to where your business actually is today.

Essential Documentation: What to Have Ready

One of the genuine advantages of working with an alternative lender like 2M7 over a traditional bank is how straightforward the documentation requirements actually are. While a bank might ask for years of audited financials, business plans, and tax returns, getting approved for a Merchant Cash Advance requires just three things:

  • Three months of business bank statements
  • A photo ID
  • A void cheque

That is it. The bank statements give lenders a clear picture of your cash flow, the frequency and consistency of deposits, your average balances, and how existing obligations are being managed. The ID and void cheque handle identity verification and ensure funds are deposited directly into the right account. 

Being organized still matters. Having these three documents ready before you apply signals that you run your business with intention, and it keeps the process moving quickly. Approvals can happen in as little as a few hours, with funds deposited within 24 hours of approval. If you want to put your best foot forward before applying, we've put together some effective strategies to help boost your business cash flow.

How Industry Risk Shapes Your Application

Not all businesses are treated equally by underwriters, and that is worth understanding before you apply. Lenders build risk models that factor in historical default rates by sector. Some industries are considered higher risk, not because of anything specific about your business, but because of how that category has performed across thousands of loans.

Restaurants, retail, and construction businesses, for example, often carry more scrutiny than professional services or healthcare businesses. Seasonal businesses face questions about cash flow stability. Newly regulated industries, or those with volatile margins, may trigger additional review.

This does not mean lenders in these sectors cannot get funded. It means the strength of your cash flow documentation, your time in business, and your repayment history need to work harder. Knowing which box your business falls into before you apply lets you structure your application in a way that addresses those concerns proactively. Regardless of your industry, the key is showing the stability of your operations.

Collateral: How It Works in the Canadian Landscape

Collateral requirements vary considerably between lenders. Traditional bank loans often require tangible assets like real property, equipment, or inventory as security. For many small business owners, that requirement alone is enough to end the conversation before it starts.

For 2M7, our Merchant Cash Advance requires no collateral. You are not asked to put your property, personal assets, or business equipment on the line. Funding is extended based on your business's revenue and performance, full stop.

At 2M7, we prioritize transparency and clarity. That means you will know your complete cost of capital before you sign, with no hidden fees or surprises down the line. If you have questions about how any part of the agreement works, we are always happy to walk you through it.

Ready to See What You Qualify For?

The application process does not need to feel like a black box. 2M7 works with Canadian small business owners every day to find funding structures that fit their actual situation, not just the profile a bank wants to see.

If you would like to talk through your options without any obligation, reach out to us directly. We will take the time to understand your business and connect you with a funding solution that makes sense.

Get Approved Today

‍

Read more