ClickCease

Four Small-Business Trends Canadian Owners Should Act On

Four Small-Business Trends Canadian Owners Should Act On

Four Small-Business Trends Canadian Owners Should Act On
7
Sep 2026
12
Oct 2026

Business trends are useful when they lead to better decisions. For Canadian small-business owners, four shifts now affect everyday operations: cyber risk is becoming more sophisticated, artificial intelligence is moving into normal workflows, customers are validating businesses across more channels, and persistent cost pressure is making cash-flow planning more important.

These trends apply differently across industries. A restaurant, contractor, retailer, and trucking company will not use the same technology or financing structure. The practical goal is to identify the changes that matter to your operation, test improvements on a manageable scale, and measure the result.

‍

1. Cyber resilience is now an operating requirement

Cybersecurity has moved well beyond antivirus software and an occasional password change. Phishing, ransomware, compromised credentials, payment fraud, and AI-assisted impersonation can disrupt sales, expose customer information, and stop a small team from operating.

CIRA’s 2025 Cybersecurity Survey collected responses from 500 cybersecurity decision-makers across Canada. Among the organizations surveyed, 43% reported being targeted in a cyberattack during the previous 12 months, while 42% reported a breach involving customer or employee data. CIRA also found that 70% were concerned about threats associated with generative AI. The Canadian Centre for Cyber Security similarly describes the national threat environment as increasingly complex and sophisticated.

The practical response is to build a small set of repeatable controls. Use multi-factor authentication for email, banking, payroll, cloud storage, and administrative accounts. Keep software and devices updated, restrict access to the information each employee actually needs, maintain tested backups, and train staff to verify unusual payment or account-change requests through a second channel.

An incident-response plan matters as much as prevention. The plan should identify who will secure accounts, contact financial institutions or technology vendors, communicate with customers, and restore critical systems. CIRA reported that 66% of surveyed organizations had used their incident-response plan in the prior year, reinforcing the value of deciding these responsibilities before an incident occurs.

‍

2. AI and digital tools need a clear business purpose

Artificial intelligence is becoming more common in Canadian businesses, but adoption alone does not guarantee a productivity improvement. Statistics Canada reports that 12.2% of Canadian firms used AI to produce goods or deliver services in 2025, double the previous year’s share, while another 14.5% planned to adopt it within the following 12 months.

The same Statistics Canada analysis offers an important caution. Firms using AI initially appeared more productive, but the direct relationship was no longer statistically significant after accounting for prior productivity and complementary capabilities such as cloud computing, data analytics, research and development, and employee technology training. The evidence suggests that AI delivers more value when it is part of a broader operating system rather than an isolated software purchase.

A sensible starting point is one repetitive, measurable workflow. A business might use a digital tool to summarize service requests, organize inventory data, draft routine customer communications, or flag overdue invoices. The owner should define the expected result, protect sensitive information, keep a person responsible for review, and compare time, error rates, or conversion outcomes before expanding the tool.

CFIB’s 2025 digital-transformation report drew on a survey of 1,683 Canadian business owners and found that firms with deeper digital adoption consistently reported stronger productivity outcomes than firms with lower adoption. The broader lesson is to connect technology spending to a process, a responsible employee, and a performance measure.

‍

3. Customers verify a business across multiple channels

A prospective customer may encounter a company through a search result, review platform, social post, industry directory, referral, or AI-generated answer. They often continue checking before they make contact. That makes consistency across the company’s website, business listings, reviews, and third-party profiles an important trust signal.

BrightLocal’s 2026 Local Consumer Review Survey used a representative panel of 1,002 U.S. adults. It found that 97% read reviews for local businesses and that respondents used an average of six review sites while evaluating businesses. After reading positive reviews, 54% said they were likely to visit the company’s website. These are U.S. consumer findings rather than Canadian population estimates, but they illustrate how reviews frequently lead to additional verification rather than an immediate purchase.

For a small business, the practical work is straightforward. Keep the business name, phone number, address, service area, hours, and product descriptions consistent wherever the company appears. Request genuine reviews as part of a normal follow-up process, respond specifically to both positive and negative feedback, and never buy or incentivize misleading reviews. Publish detailed case studies or testimonials only with appropriate customer permission.

The company website must support what people find elsewhere. Clear service explanations, real leadership information, transparent contact details, and consistent business facts help visitors evaluate credibility. They also give search engines and AI systems better source material when answering questions about the business. Owners evaluating any financing company should review its reputation, verify its claims, and use a structured set of questions before choosing a business funder.

‍

4. Cash-flow flexibility remains a competitive capability

Revenue and profit do not always arrive on the same schedule as payroll, inventory purchases, repairs, tax obligations, or supplier payments. Persistent cost pressure makes that timing gap harder to absorb.

Statistics Canada reported that 62.2% of businesses expected cost-related obstacles in the third quarter of 2025. Inflation was the most frequently cited cost obstacle, and accommodation and food services and retail trade were among the sectors most likely to identify it. The practical implication is that owners need a current cash-flow forecast rather than relying only on an annual budget or income statement.

A useful forecast maps expected cash receipts and required payments by week, highlights possible shortfalls, and defines what action the business will take if sales, collections, or costs move away from plan. Owners can also review supplier terms, deposit policies, invoicing speed, inventory levels, recurring expenses, and the minimum reserve needed to cover critical obligations.

External financing may be part of that plan, but the product should match the purpose. Innovation, Science and Economic Development Canada reports that 97% of small-business debt-financing applications were approved in 2025 and that the average interest rate declined to 5.8%. However, 75% of small businesses obtaining debt financing were required to pledge collateral, up from 66% in 2024. Availability therefore does not tell an owner whether a product is appropriate for a particular need.

Before choosing funding, compare the total repayment amount, annualized cost where available, collateral or guarantee requirements, time to funding, payment frequency, flexibility during slower periods, early-payment terms, and permitted use of proceeds. A conventional loan or line of credit may suit a planned, longer-term investment. A merchant cash advance may be considered for a shorter-term working-capital need when speed and revenue-linked remittances are important, but its total cost should be reviewed carefully. Businesses with imperfect credit can also compare the broader range of business-funding options available in Canada.

‍

Turn trends into operating decisions

The most useful response to these trends is a short operating plan. Strengthen one cyber control, test one digital workflow, correct inconsistent public information, and update a 13-week cash-flow forecast. Each action should have an owner, a deadline, and a simple measure of success.

If a working-capital need remains after reviewing expenses, collections, reserves, and conventional financing, compare the available structures carefully. 2M7 can explain how its funding works and provide the total repayment and remittance terms for review. Readers can also consult the small-business finance glossary before requesting a quote or starting an application.

‍

Sources

  1. 2025 CIRA Cybersecurity Survey
  2. National Cyber Threat Assessment 2025–2026 — Canadian Centre for Cyber Security
  3. Artificial intelligence adoption and productivity in Canadian firms — Statistics Canada
  4. Digital Transformation: How small businesses in Canada are leveraging AI and technology — CFIB
  5. Local Consumer Review Survey 2026 — BrightLocal
  6. Canadian Survey on Business Conditions, third quarter 2025 — Statistics Canada
  7. Small Business Credit Condition Trends, 2015–2025 — Innovation, Science and Economic Development Canada

‍

Related articles

October 14, 2026
October 14, 2026

Best equipment financing options in Canada 2026

Best overall for long-term ownership: an equipment loan. Best for planned replacement: an equipment lease. Best for flexible purchases: a business line of credit. This 2M7 guide compares equipment financing options in Canada for 2026 by ownership, cash flow and contract restrictions—not by advertised payments alone.

TL;DR

  • 2M7’s equipment financing Canada guide ranks equipment loans first for businesses seeking long-term ownership.
  • Equipment leases suit planned replacement, but return conditions and purchase options need close review.
  • Business lines of credit suit flexible purchases when repayment does not crowd out operating cash.
  • Compare vendor-arranged financing with direct financing using the same equipment quote and repayment assumptions.

Why this matters

Equipment financing affects more than your payment schedule. It determines whether you own the asset, what security the financier takes and what happens when you replace or sell the equipment.

A payment that fits today does not settle the decision. Your business also needs enough cash for maintenance, insurance, payroll and periods when the equipment produces less revenue.

For 2026, start with the asset’s job in your business. A machine you intend to keep needs a different financing assessment from equipment you expect to replace as your work changes.

What makes the best equipment financing option?

Use these criteria before comparing offers. The strongest option fits the equipment’s working life and your repayment capacity without creating an unwanted exit obligation.

  • Ownership: Decide whether you need title to the equipment or only the right to use it.
  • Payment fit: Match scheduled obligations to cash your business can reliably generate, not its busiest period.
  • Total obligation: Compare the full payment schedule, fees and any required final payment or purchase amount.
  • Security: Identify the assets pledged and whether a personal guarantee is required.
  • Exit terms: Check early repayment, early termination, sale restrictions and end-of-term responsibilities.
  • Asset fit: Confirm that the proposed arrangement accepts the specific equipment, condition and intended use.

Ask for written terms. A verbal explanation of ownership or an end-of-term purchase option is not a substitute for the contract.

Equipment financing options at a glance

These 5 financing routes serve different needs. Vendor-arranged financing describes how you obtain the offer; the underlying contract can still be a loan or lease.

Equipment loan

  • Best for: Long-term ownership
  • Standout feature: Finances an equipment purchase with scheduled repayment
  • Key limitation: Security and repayment obligations remain until discharged

Equipment lease

  • Best for: Planned replacement
  • Standout feature: Provides equipment use under an agreed lease term
  • Key limitation: Ownership and exit depend on the contract

Business line of credit

  • Best for: Flexible purchases
  • Standout feature: Allows borrowing and repayment within an approved facility
  • Key limitation: Equipment debt can consume working-capital capacity

Vendor-arranged financing

  • Best for: Purchase coordination
  • Standout feature: Connects the equipment purchase with a financing application
  • Key limitation: Convenience does not establish the best financing terms

Secured business loan

  • Best for: Equipment within a broader project
  • Standout feature: Can fund an eligible project containing equipment and other expenses
  • Key limitation: Security can extend beyond the purchased equipment

The table ranks financing structures, not lenders. Approval criteria, documentation and contract terms differ between providers, so the same structure can produce very different obligations.

1. Equipment loan: best equipment financing for long-term ownership

An equipment loan finances the purchase of equipment and requires repayment under an agreed schedule. The business purchases the asset, while the lender can take security over it or other agreed assets.

An equipment loan is the default choice when ownership is the goal and scheduled repayments fit the business. That does not make every equipment loan suitable: the security agreement, repayment terms and asset restrictions still decide whether the offer works.

Equipment loan pros

  • Supports purchasing equipment you intend to keep.
  • Provides a defined repayment schedule under the agreement.
  • Separates the purchase from a lease-return decision.
  • Lets you assess financing alongside the equipment’s expected working life.

Equipment loan cons

  • Repayments continue even when the equipment is idle.
  • Security requirements can restrict disposal of the asset.
  • Early repayment conditions require review before signing.

Best for: Businesses buying equipment for continuing use rather than routine replacement.

Before accepting a 2026 equipment loan, ask what happens if the asset needs replacement before repayment ends. You need to know whether sale proceeds can discharge the financing, whether lender consent is required and whether any remaining balance survives the sale.

Verdict — Buy: Choose an equipment loan when you want ownership and can support the repayment schedule through quieter trading periods.

2. Equipment lease: best equipment financing for planned replacement

An equipment lease gives your business the right to use equipment under an agreement with the lessor. The contract determines the payment schedule, permitted use, maintenance responsibilities and end-of-term choices.

A lease is not automatically a path to ownership. If ownership matters, identify the purchase option and its conditions before comparing the lease with a loan.

Equipment lease pros

  • Suits businesses focused on equipment use rather than immediate ownership.
  • Establishes a defined term for the equipment arrangement.
  • Allows a planned end-of-term decision where the contract provides suitable choices.
  • Can align with a replacement plan when the lease conditions support it.

Equipment lease cons

  • Early termination can create contractual obligations.
  • Return conditions can add work and expense at the end.
  • A purchase option is not the same as an unconditional transfer of ownership.

Best for: Businesses with a defined replacement plan and equipment needs that fit the lease term.

For a 2026 lease comparison, request the return requirements alongside the payment schedule. Equipment condition, transport responsibilities and notice deadlines belong in the decision, not in a separate file you read later.

Also distinguish financing from service. Maintenance, repairs and replacement equipment are included only when the agreement explicitly says so.

Verdict — Buy: Choose an equipment lease when the use period and end-of-term obligations match your replacement plan; skip it when ownership terms are unclear.

3. Business line of credit: best equipment financing for flexible purchases

A business line of credit allows borrowing within an approved limit under the facility’s terms. It can fund equipment purchases where the agreement permits that use, without a separate equipment-financing contract for each purchase.

Flexibility is its main advantage. The trade-off is that the equipment purchase uses capacity your business might otherwise need for operating expenses.

Business line of credit pros

  • Supports purchases at different times within the approved facility.
  • Allows repayment and further borrowing under the agreement.
  • Avoids matching every purchase to a separate equipment contract.
  • Provides flexibility when the final purchasing schedule is uncertain.

Business line of credit cons

  • Equipment borrowing reduces remaining credit capacity.
  • Variable-rate terms expose borrowing costs to rate changes.
  • An accessible facility still needs a deliberate repayment plan.

Best for: Businesses making flexible purchases while preserving enough unused capacity for operations.

Do not treat the available limit as an equipment budget. First reserve the capacity needed for supplier payments, payroll and revenue interruptions, then assess what remains.

Compare a line of credit with a dedicated equipment loan when the purchase will stay financed for a long period. Flexible borrowing is useful only if the repayment plan fits the asset and does not leave operating cash permanently constrained.

Verdict — Hold: Use a business line of credit for equipment only after setting a repayment plan and protecting working-capital capacity.

4. Vendor-arranged financing: best equipment financing for purchase coordination

Vendor-arranged financing connects an equipment purchase with a financing offer or application through the seller. The seller might introduce a financing provider or present an arrangement available for that purchase.

This is a purchasing channel, not a distinct financial contract. Determine whether the actual offer is a loan, lease or another agreement before assessing its suitability.

Vendor-arranged financing pros

  • Coordinates the equipment quote with the financing application.
  • Keeps the proposed asset clearly identified during the process.
  • Gives you an offer to compare with independently obtained financing.

Vendor-arranged financing cons

  • The presented offer does not represent every financing option.
  • Purchase convenience can distract from security and exit terms.
  • The financing provider and equipment seller can be separate parties.

Best for: Buyers who want coordinated purchasing but will still compare the written financing agreement.

Request the equipment quote separately from the financing schedule. This makes it easier to compare the same asset across offers without confusing equipment charges with financing obligations.

For a 2026 purchase, ask who handles an equipment dispute and who collects payments. Do not assume a dispute with the seller automatically pauses obligations to a separate financier.

Verdict — Hold: Consider vendor-arranged financing after comparing its underlying contract with a direct financing offer for the same equipment.

5. Secured business loan: best equipment financing for a broader project

A secured business loan can fund eligible business purposes under the lender’s agreement. Equipment can form part of a wider project that also includes installation, premises work or other approved expenses.

This route deserves consideration when the equipment purchase is only one part of the funding need. Its central limitation is the security package: assets beyond the equipment can be pledged.

Secured business loan pros

  • Can address an eligible project rather than an isolated asset purchase.
  • Allows equipment and related approved expenses to be assessed together.
  • Provides a repayment structure for the agreed borrowing.

Secured business loan cons

  • Security can extend beyond the financed equipment.
  • Broader funding needs require careful documentation of eligible uses.
  • Project delays do not automatically change repayment obligations.

Best for: Businesses funding equipment within a defined expansion or installation project.

Separate the equipment budget from the rest of the project before applying. You need to understand which expenses the proposed facility covers and which must come from existing cash.

Compare this route against a dedicated equipment loan plus separately funded project expenses. The choice depends on repayment fit and security exposure, not simply whether one agreement feels easier to administer.

Verdict — Hold: Choose a secured business loan when the wider project justifies it and the pledged assets are acceptable.

How the options are ranked

This 2M7 equipment financing guide ranks each route by its clearest use case: ownership, planned replacement, purchasing flexibility, purchase coordination or broader project funding.

Equipment loans take the default position because they directly address an equipment purchase with ownership as the objective. Leases take the replacement slot; lines of credit take the flexibility slot. Vendor arrangements and broader secured loans require an additional check because the channel or project scope does not itself establish suitable financing terms.

No ranking substitutes for reviewing the actual contract. An unsuitable equipment loan loses to a lease that genuinely fits your business.

Check cash flow before choosing

Build a 12-month cash-flow forecast that includes the proposed financing obligations and equipment operating expenses. Use 3 cash-flow scenarios: expected trading, weaker revenue and an equipment interruption.

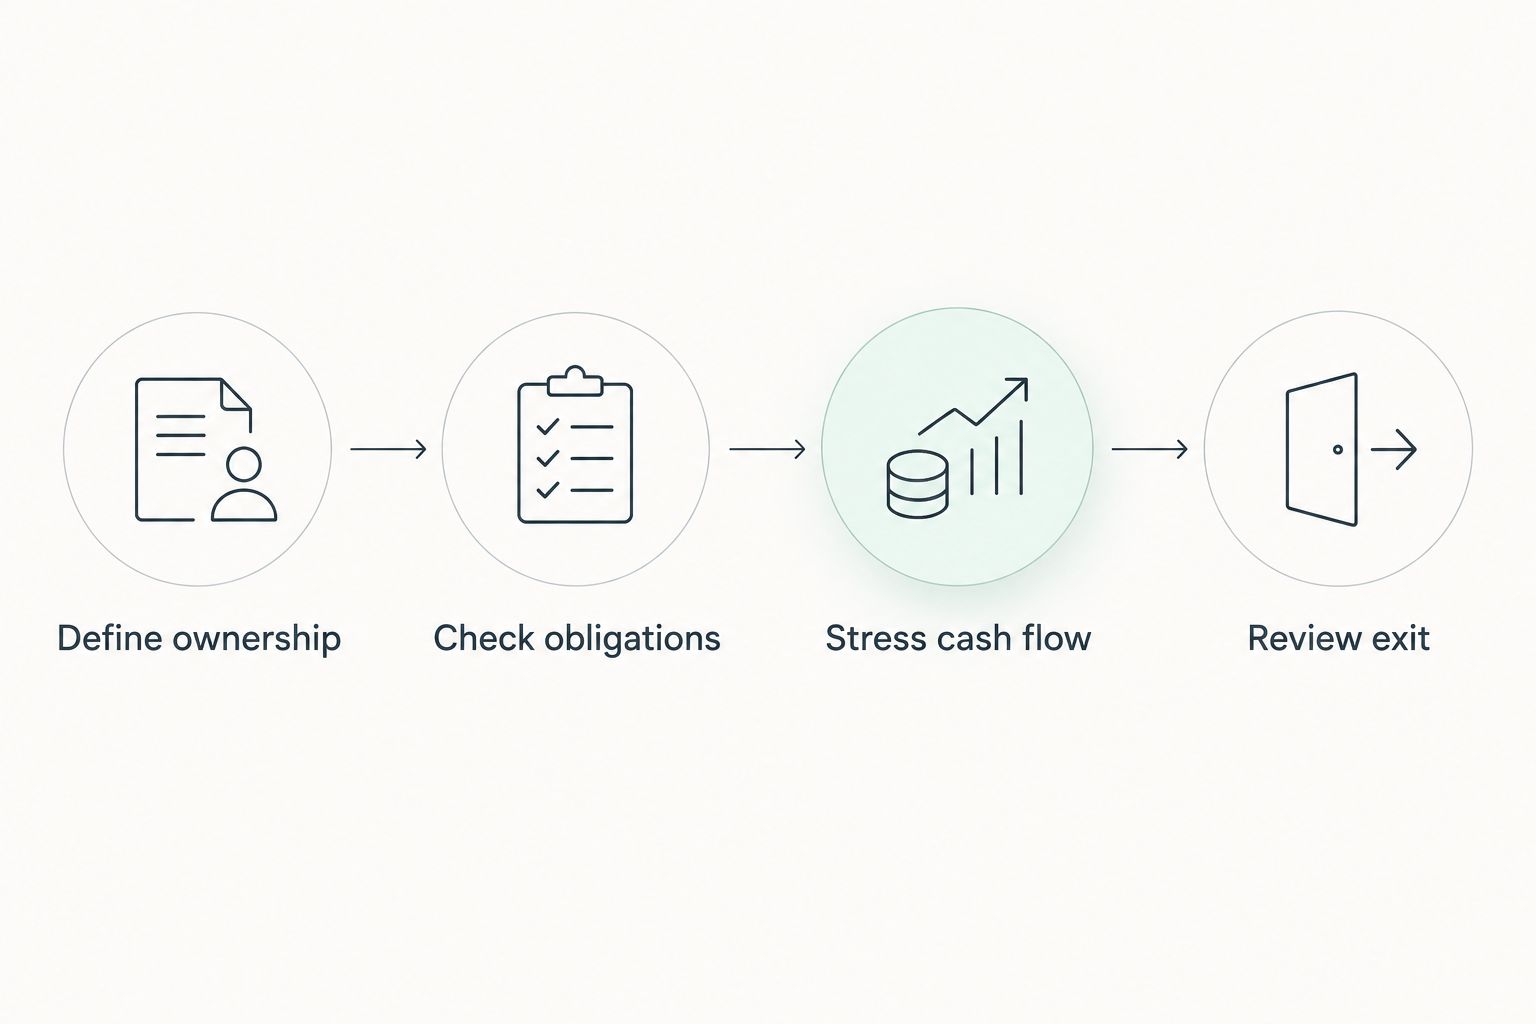
Follow this sequence before signing:

  • Define ownership: State whether you need to own the asset or use it for a defined period.
  • Check obligations: Include scheduled payments, required fees and end-of-term commitments.
  • Stress cash flow: Test repayment alongside payroll, suppliers, maintenance and insurance.
  • Review exit: Read the conditions for repayment, termination, sale or return.

The weaker-revenue scenario should show whether your business can meet obligations without relying on the equipment operating continuously. The interruption scenario should include the operational consequence of downtime as well as the financing payment.

Four checks covering ownership, obligations, cash flow and exit terms

Check repayment capacity and exit terms before accepting the financing agreement.

Keep assumptions consistent across offers. Comparing one arrangement using strong sales and another using cautious sales tells you nothing useful about the financing itself.

Which equipment financing option should you choose?

Choose an equipment loan first when you want to own equipment for continuing use. Compare a lease when replacement is planned, and consider a line of credit only when equipment borrowing leaves sufficient operating capacity.

For equipment financing in Canada in 2026, use the 2M7 guide to choose the structure before comparing providers. Then compare written offers for the same equipment, funding need and intended use period.

If none of the offers survives your cash-flow checks, wait. Financing does not fix a purchase that your business cannot support.

FAQ

What’s the best equipment financing option in Canada?

An equipment loan is the default option for businesses seeking long-term ownership and scheduled repayment. A lease fits planned replacement better when its end-of-term conditions match the business’s needs.

Is an equipment loan better than a lease?

An equipment loan is better aligned with ownership; a lease is better aligned with use over an agreed term. Compare security, repayment obligations and exit conditions before choosing.

Can I buy equipment with a business line of credit?

You can use a business line of credit for equipment when the facility permits that use. Set a repayment plan and preserve enough capacity for operating expenses.

Does an equipment lease include maintenance?

An equipment lease includes maintenance only when the agreement explicitly provides it. Review responsibility for repairs, servicing, insurance and equipment downtime separately.

Is vendor financing a loan or a lease?

Vendor-arranged financing can involve a loan or lease, depending on the underlying agreement. Identify the actual financing provider and contract type before comparing the offer.

How much does equipment financing cost in Canada?

Equipment financing costs depend on the written offer, including financing charges, fees and required final obligations. Compare complete schedules for the same equipment and funding need rather than payments alone.

What should I check before signing an equipment financing agreement?

Check ownership, payment obligations, security, guarantees and exit conditions before signing. Test the agreement against expected trading, weaker revenue and an equipment interruption.

One last thing

The end of the agreement belongs in the beginning of your decision. Before accepting equipment financing in 2026, write down exactly what you must do to own, return, sell or replace the asset.

If you cannot explain that outcome in plain language, pause and get the relevant contract clause clarified. The final obligation matters as much as the first payment.

Read more
October 16, 2026
October 16, 2026

Best merchant cash advance options for small businesses 2026

Best for a direct-funder relationship: 2M7. Best for card-sales-linked payments: a merchant cash advance with that structure explicitly written into the agreement. Best for an intermediary-led search: a broker-arranged advance. This 2026 guide compares those routes and explains when a business line of credit is the better alternative.

TL;DR

  • For merchant cash advance options Canada businesses can compare, 2M7 fits owners seeking a direct funder.
  • Card-sales-linked payments suit daily card-processing businesses; confirm exactly how payments respond to sales.
  • A broker arranges funding rather than providing it directly; identify the actual funder before signing.
  • A business line of credit is an alternative for recurring borrowing, not a merchant cash advance.

Why this matters

A merchant cash advance provides business funding against future sales, with collection terms set out in an agreement. It differs from a conventional business loan. Your decision should centre on the amount your business receives, the total contractual obligation and how collections affect operating cash flow.

The options below are not interchangeable products. Direct funding describes who provides the capital. Card-linked payments describe how collections work. A broker describes an intermediary. One agreement can combine these features.

Choose the payment structure your business can sustain, then choose the funding relationship. A familiar label does not tell you whether the agreement fits your payroll, supplier bills or sales cycle.

What makes the best merchant cash advance option?

Use these criteria to compare merchant cash advance options in Canada in 2026:

  • Funding relationship: Establish whether you are dealing with the funder or an intermediary. Know who approves the application and manages the account.
  • Eligibility fit: Check operating history, monthly revenue and any payment-processing requirements before applying.
  • Collection structure: Identify whether payments follow card sales or use another collection arrangement. Read the actual formula.
  • Total obligation: Compare the amount received with the complete amount payable. Ask for every contractual charge in writing.
  • Cash-flow fit: Test the collections against a slower sales period, not just your strongest month.
  • Contract clarity: Review early-payment conditions, security requirements and what happens when payments are missed.

Do not rank an offer by approval speed alone. Funding that arrives quickly still needs to leave enough operating cash for the work it is meant to support.

Merchant cash advance options at a glance

This 2026 comparison ranks decision routes, not competing branded products. The line of credit appears as a clearly marked alternative because recurring access to funds is a different need from a single advance.

2M7 direct-funded merchant cash advance

  • Best for: Owners seeking a direct funding relationship
  • Standout feature: Direct funder rather than a broker
  • Key limitation: Minimum operating-history and revenue requirements apply

Card-sales-linked merchant cash advance

  • Best for: Businesses processing daily card payments
  • Standout feature: Collections tied to card sales where the agreement specifies it
  • Key limitation: Not a fit for businesses without qualifying card processing

Broker-arranged merchant cash advance

  • Best for: Owners wanting an intermediary to approach funders
  • Standout feature: A separate party manages the funding search
  • Key limitation: The broker is not the source of capital

Business line of credit

  • Best for: Businesses needing recurring draws and repayments
  • Standout feature: Reusable borrowing access, subject to the agreement
  • Key limitation: A loan alternative to an advance, with its own underwriting requirements

1. 2M7: best merchant cash advance for direct-funder access

This Canadian direct funder provides merchant cash advances and working capital to small and mid-sized businesses. You deal with the funding provider rather than a broker. Funding uses include payroll, inventory, equipment and cash-flow gaps.

The stated eligibility baseline is at least 3 months in business and $15,000 in monthly revenue. Businesses with less-than-perfect credit are within its stated audience, but eligibility is not an approval decision.

Best for: An operating Canadian business that meets those thresholds and wants a direct relationship with its funder.

2M7 pros

  • Direct funding means there is no broker between your business and the capital provider.
  • The stated audience includes businesses with less-than-perfect credit.
  • One fixed cost of capital is shown before signing and does not change based on how long repayment takes.
  • Existing clients can text or call their funding representative directly.

2M7 cons

  • Businesses below the operating-history or monthly-revenue thresholds do not meet the stated baseline.
  • Flex payments are only for businesses that process daily card payments.
  • Meeting the baseline does not establish that the proposed collections fit your cash flow.

The published approval rate is 75%, not an individual promise. Assess the written offer on its own terms, including the collection arrangement and the cash your business retains after payments.

Verdict: Buy only after confirming that the written obligation and collection schedule fit your operating budget.

2. Card-sales-linked advances: best for daily card-processing businesses

A card-sales-linked merchant cash advance uses card receipts as the basis for collections where the agreement specifies that arrangement. This structure is relevant when your business processes daily card payments and wants collections connected to those receipts.

Do not assume every merchant cash advance works this way. The label alone does not establish the collection percentage, payment frequency or treatment of sales outside the card channel.

Best for: A business with daily card transactions that can verify the relationship between card sales and collections.

Card-sales-linked advance pros

  • The agreement can connect collections to the payment channel your business uses daily.
  • A clearly stated collection formula lets you model the effect of different card-sales levels.
  • Reviewing card receipts alongside collections helps you assess the operating cash left for other bills.

Card-sales-linked advance cons

  • Businesses without qualifying daily card processing need a different structure.
  • Card receipts alone do not show your full cash position, including supplier payments and payroll.
  • Sales-linked collections do not remove the contractual obligation or make the funding cost disappear.

Ask the funder to explain how refunds, chargebacks and processing changes affect collections. Get the answers in writing rather than relying on a general description of flexibility.

Verdict: Buy only when the agreement explicitly links collections to card sales and your cash-flow forecast supports it.

3. Broker-arranged advances: best for an intermediary-led search

A merchant cash advance broker helps arrange funding from another provider. The broker is an intermediary, not the business supplying the capital. That distinction matters when you need to understand who makes decisions and who handles the account after funding.

The value of this route depends on the actual search process. Ask which funders the broker approaches, how information is shared and how compensation works before submitting documents.

Best for: An owner who wants an intermediary to manage a funding search and is prepared to check the underlying funder independently.

Broker-arranged advance pros

  • An intermediary can coordinate the application process with the funders it works with.
  • The broker can help explain the offers it presents.
  • You can assess its proposed search process before authorising submissions.

Broker-arranged advance cons

  • A broker's presence does not establish that every relevant funding option has been considered.
  • You must distinguish the broker's responsibilities from the funder's contractual obligations.
  • Compensation and information-sharing arrangements need separate scrutiny.

Compare written agreements, not just the broker's summary. Identify the legal funding counterparty, the party collecting payments and the contact responsible for account questions.

Verdict: Hold until you understand the funder, the broker's role and every disclosed charge.

4. Business lines of credit: best alternative for recurring draws

A business line of credit is borrowing access that lets you draw funds up to an approved limit, subject to the agreement. Repayments can restore available borrowing capacity under its terms. It is not a merchant cash advance.

Include this alternative when your real need is repeated access to working capital rather than one defined funding amount. Compare the lender's underwriting, interest, charges and account conditions with the advance being considered.

Best for: A business that needs recurring draws and can satisfy the lender's requirements.

Business line of credit pros

  • You can draw funds as needed within the approved facility's terms.
  • Repayment can restore borrowing capacity rather than requiring a separate advance.
  • The structure supports a recurring funding need when the facility remains in place.

Business line of credit cons

  • Approval and account terms depend on the lender's underwriting requirements.
  • Interest, charges and security requirements need careful comparison.
  • Access remains subject to the agreement rather than being an unconditional reserve.

A line of credit is not automatically the right answer. Match its draw rules and repayment requirements to your actual collection cycle, especially when customer payments arrive after supplier bills fall due.

Verdict: Buy if recurring access is the need and the facility's terms fit; skip it as a substitute for fixing persistent operating losses.

How to compare written offers before signing

In 2026, use the same business forecast for every offer. Otherwise, you risk comparing one proposal against an optimistic month and another against a conservative month.

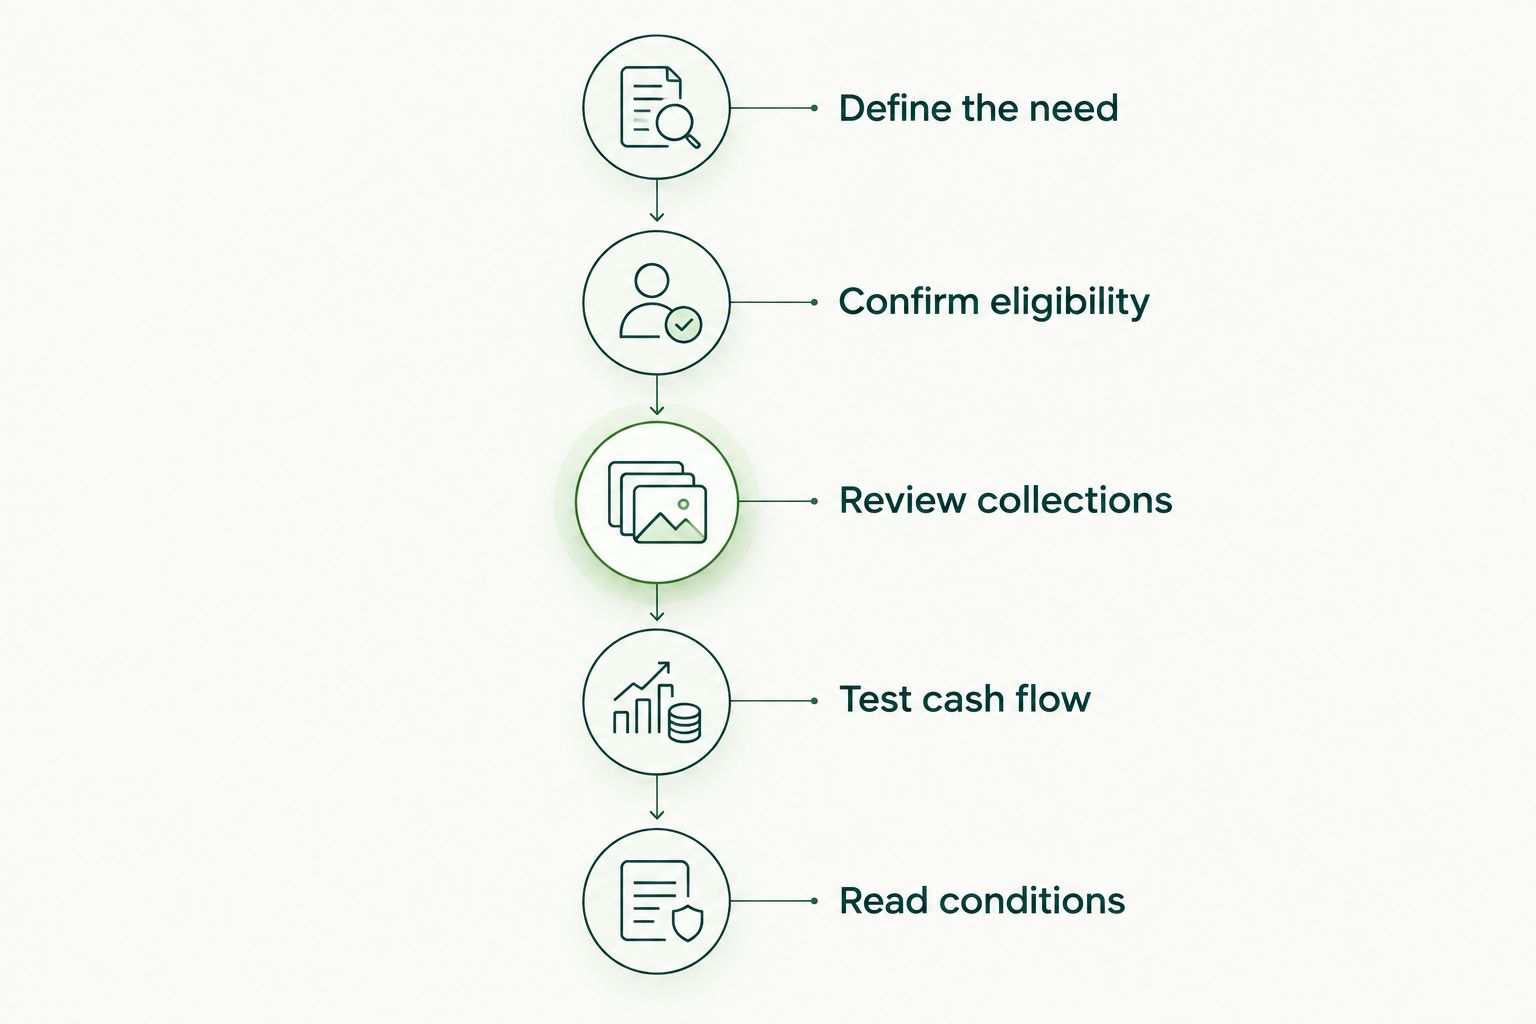
Define the need

Name the expense and the business outcome it supports. Payroll, inventory replenishment and equipment purchases have different cash-flow patterns. Separate the amount needed for that purpose from any additional amount offered.

Confirm eligibility

Check the stated revenue, operating-history and processing requirements. Explain your revenue sources accurately. A business paid mainly by invoices should not evaluate a daily-card-processing requirement as though those payment channels were identical.

Review collections

Write down when collections occur and what determines their size. Identify the business account or payment channel involved. Ask what the agreement requires if sales fall or a scheduled payment cannot be completed.

Test cash flow

Place the proposed collections beside payroll, rent, supplier commitments and existing obligations. Use your own slower-period records rather than an invented industry average. The useful result is the cash left to operate, not simply whether the collection can clear.

Read conditions

Review early payment, additional funding, missed payments, security and any personal obligations. Ask for unclear terms to be explained before signing. Keep the signed agreement and disclosures together for reference.

Five steps for checking a business funding offer before signing

Check operating cash flow before accepting the agreement.

The final comparison should make the trade-off visible: how much operating cash the funding adds now, what your business must pay under the agreement and what remains available for ordinary expenses.

How this ranking works

The 2026 ranking prioritises a clear funding relationship, eligibility fit, collection transparency and a distinct use case. It does not treat direct funding, broker involvement and card-linked collections as mutually exclusive products.

The first recommendation answers who you deal with. The second addresses payment structure. The third addresses how you search. The fourth tests whether a different borrowing structure better matches recurring needs.

Which merchant cash advance option should you choose?

2M7 is best for Canadian business owners seeking a direct-funded merchant cash advance without a broker. Start there if that relationship is your priority and you meet the stated operating-history and revenue thresholds.

If daily card receipts drive your cash flow, scrutinise the collection formula next. If you prefer an intermediary-led search, check the broker's role and the underlying funder separately. If you need repeated draws, compare a business line of credit before committing to an advance.

For a 2026 decision, choose the agreement your business can support during a slower period, not the largest amount offered. Discuss your funding options with a funding specialist and ask for the complete terms before deciding.

FAQ

What's the best merchant cash advance option in Canada?

The best option is the one whose eligibility requirements, collection structure and contractual obligation fit your business. Choose a direct funder for a direct funding relationship, and assess card-linked collections separately from who supplies the capital.

Is a merchant cash advance a business loan?

A merchant cash advance is not a conventional business loan. It provides business funding against future sales under an agreement, so compare its actual terms rather than treating it as interchangeable with a line of credit.

Does every merchant cash advance adjust payments when sales fall?

No, the merchant cash advance label does not establish how collections change with sales. Check the written formula and ask the funder to explain what happens during a slower period.

Is a direct funder better than a broker?

A direct funder suits owners who want to deal with the capital provider rather than an intermediary. A broker suits owners who want help arranging a funding search, but the underlying funder's agreement still needs independent review.

Can a business with less-than-perfect credit apply?

Less-than-perfect credit does not rule out every merchant cash advance option. Check each provider's stated eligibility requirements, and distinguish permission to apply from an actual approval decision.

What should I compare besides the funding amount?

Compare the complete contractual obligation, collection frequency, collection formula and early-payment conditions. Test those terms against payroll, suppliers and other existing commitments using your own cash-flow records.

When is a business line of credit a better alternative?

A business line of credit fits a recurring need for draws and repayments when your business meets the lender's requirements. It is a different borrowing structure, so compare underwriting, interest, charges and account conditions rather than assuming it works like an advance.

One last thing

A payment that changes with sales and a cost that changes over time are different features. Do not confuse them. Ask two separate questions: what determines each collection, and what determines the total contractual obligation?

That distinction makes a funding conversation more useful. You can evaluate flexibility without assuming it changes what the agreement requires your business to pay.

Related guides

Read more
June 1, 2026
July 27, 2026

Why a Merchant Cash Advance is Better than a Business Loan

When the Tool Has to Fit the Business, Not the Other Way Around

At some point, almost every small business owner in Canada has looked at a business loan and felt the gap between what the bank wants and what their business actually looks like. Too short a history. Too small an ask. Too little collateral. Too much paperwork for too slow a process. The loan was designed for a different kind of business, and you were left to figure out something else.

That something else, for a growing number of Canadian business owners, is a merchant cash advance.

This is not about settling for a second option. In a lot of situations, a merchant cash advance is simply the better tool. Understanding why starts with understanding what most business loans are actually built for.

Business Loans Were Not Designed With You in Mind

Traditional business loans are structured around large capital needs, extended approval timelines, and borrowers who can prove years of consistent financial history. Many institutional lenders will not begin a conversation below a certain loan threshold, often $100,000 or more. If you need $30,000 to cover a cash flow gap between two contracts, or $50,000 to lock in a supplier discount before it expires, it helps to understand what alternatives to a business loan actually exist before assuming a traditional loan is your only path. 

The qualification requirements compound the problem. Banks want detailed business plans, multiple years of financial statements, personal guarantees, and often collateral. For a business that is six months old and generating solid monthly revenue, that history simply does not exist yet. The bank sees risk where the business owner sees momentum.

A merchant cash advance evaluates different signals entirely. Providers look at your actual sales volume, typically your credit and debit card transaction history, and use that to determine what you can reasonably receive and repay. The business you have built is the application. You are not being asked to prove what you might eventually become.

Repayment That Moves With Your Business

One of the most significant differences between a business loan and a merchant cash advance is how repayment works. A loan comes with a fixed monthly obligation. It does not matter whether November was your quietest month in three years or whether a large receivable is still outstanding. The payment is due, and it is the same number it was last month.

A merchant cash advance repays as a percentage of your daily sales. When business is strong, more gets remitted and the advance gets paid down faster. When business slows, the remittance drops accordingly. Your obligations shrink with your revenue and recover when revenue does.

For businesses that operate with any kind of seasonal pattern, this distinction is not a minor detail. A retailer carrying inventory into the holiday season, a contractor waiting on a draw schedule, a restaurant navigating the stretch between summer and fall: all of these businesses face months where a fixed loan payment creates real strain. The flexible structure of a merchant cash advance removes that strain, replacing it with a repayment rhythm that reflects how the business is actually performing.

‍

Accessible When You Are Just Getting Started

The businesses that most need capital are often the ones traditional lenders are least willing to fund. A business that has only been operating for a few months does not yet have the credit history or financial documentation that banks require. That does not mean the business is not viable. It means the track record has not accumulated yet.

Merchant cash advances are accessible to Canadian businesses that have been operating for as little as three months and are generating consistent monthly revenue. The bar is set around what you are doing now, not what you were doing two years ago. For newer businesses already gaining traction, that is a meaningful difference.

It also means that an MCA can be used proactively, before a cash gap turns into a crisis. Business owners who understand their financing options ahead of time are the ones who can move quickly when a real opportunity appears: hire before the busy season, lock in inventory pricing, or cover a short-term gap without pulling from personal funds or slowing operations down.

No Hidden Fees, No Runaround

One of the quieter frustrations with traditional lending is that the real cost of a loan often does not become clear until you are already committed to it. Fees buried in fine print, penalties for early repayment, and compounding interest structures make it difficult to know upfront what you are actually agreeing to.

2M7's approach is different, and that commitment is not just marketing. You see what you will pay before you sign, and that is all you pay. No prepayment penalties, no hidden fees, no financial gibberish. For a business owner trying to make a clear-eyed decision about capital, that transparency matters.

The Right Tool for the Right Moment

A business loan has its place. For large, long-horizon capital investments where extended repayment timelines make sense, it can be the right answer. But for the specific pressures most small businesses in Canada actually face, tight cash flow windows, seasonal cycles, growth that is moving faster than receivables, a merchant cash advance is built closer to the shape of the problem.

If you want to understand what an advance might look like for your situation, 2M7 is ready to walk through it with you.

‍

Read more