ClickCease

How To Get A Business Loan With a Bad Credit Score?

How To Get A Business Loan With a Bad Credit Score?

Bad Credit? Get Business Funding in Canada
28
Apr 2026
30
Sep 2026

As a small business owner, when you go to a bank for a business loan, instead of looking at the performance of your business, the bank will check your personal credit score first. This means, even if your business is performing well and profitably, a fair credit score of 600-650 could prevent you from getting a small business loan. A credit score of under 600 portrays you as a high-risk borrower and will make it nearly impossible to borrow even a small loan. A low credit score stops business loans being disbursed to profitable and stable businesses. Bad credit history will follow you and your business for years. For example, you may have owned a successful business for a few years and now you are looking for funds to expand into another city or purchase more equipment, but when you visit the bank, the loan officer turns you away. Why? The answer is easy – his decision is based on your poor personal credit history.

Credit scores

There is no standard scale that defines your credit score. That evaluation varies from a credit agency to a credit agency as they set their own criteria. A credit report from Equifax may give a person one number, while a credit report from another institution will very likely suggest a higher or lower credit score for the same person. Credit scores in Canada are officially assessed by two entities: Equifax and TransUnion.

  • The higher the credit score, the safer it is to lend to you
  • Credit scores typically range from 300 to 900

Credit score brackets:

  1. 800-900 – Highest bracket; excellent credit history
  2. 700-799 – Very good credit history; lowest interest rates available
  3. 650-699 – the Lowest score that can receive standard loans
  4. 600-649 – Fair score; higher interest rates applicable
  5. 300-599 – Low scores; less likely to receive business loans

Therefore, if you have a credit score of 649 or lower, it will dramatically reduce the chance of your business loan being approved. Since major banks first look to the business owner’s personal credit score, even exceptional business performance may not make you eligible for loans, or high-interest rates may apply to you.

What happens if you have a low credit score?

If the borrower has a bad credit score, other than a higher likelihood of being refused a loan by the major financial institutions, there are a few other ramifications:

  • Higher interest rates on loans and lines of credit
  • Difficulty finding business premises
  • Security deposits required by utility companies
  • Higher insurance premiums for business assets

Private lenders help small businesses with bad credit history get loans

Fortunately, there are ways of getting business loans for your company even if you - the borrower - have bad credit. To get small business loans with bad credit history, private lenders are one of the best options. These are more local lenders, better tuned to market conditions, who offer more flexible loan options. There are many private lenders that can provide small business loans. Bad credit history or credit score will make little or no difference to the loan, depending on the type of loan you opt for. Moreover, the application process is much easier and repayments are more flexible. It is possible that a private lender will ask you to open a business bank account with them before they provide you with funding.

‍

‍

How to get a business loan with a bad credit score?

Merchant cash advance (MCA) lenders provide cash advances, customize private terms and business equity line of credit to small business owners. This would be the best way to get a business loan with no credit assessment, and beneficial repayment terms if you happen to have a bad credit history. Instead of checking your personal credit score, a merchant cash advance provider assesses your business’ performance and monthly credit card sales.The MCA lender will give you an upfront sum of cash in exchange for a percentage of the business’s daily credit card income.  The MCA lender will tie into the credit card processor directly to settle credit card payments so the business owner does not have to worry about missing the payments or dealing with administrative processes. There are many pros and cons of having MCA but regardless of that, it is still considered as the best way to get business fundings.A private term loan gives you the same perks as a small business loan from a major lending institution. However, the private lender does not give the same weight to your bad credit when deciding on the small business loan. Instead, the lender mitigates the risk with fixed daily repayment terms.A business equity line of credit is much less reliant on the credit history of the business owner. Therefore, if you have a bad credit history and require financing for your business, you can use your equity in the business as collateral. A business equity line of credit helps businesses resolve their cash flow issues, though it does require putting up a part of your ownership as collateral.

If the funding is for equipment specifically, our guide to bad credit equipment financing in Canada compares leasing, vendor financing, government-backed programs and merchant cash advances, including how their costs differ.

Start-up bad credit business loans

For entrepreneurs with bad credit seeking business loans for their start-up, private lenders and alternative lending are the best options. Where small business loan applications at major institutions have a less than 25% chance of approval, merchant cash advance (MCA) approvals stand at over 75%! This is because MCAs do not evaluate the business owner’s personal credit score, and only take into account business performance. Besides that, MCAs can be approved within 4-6 hours.Government loans and grants are also great options. Both have flexible repayment terms and offer additional business support to small entities. However, some of the government loans may require a good credit history and may have strict eligibility criteria.

Using business loans to rebuild your credit

Apart from using funds to expand their business, business loans can help borrowers improve their personal credit scores. Once you opt for an equity line of credit or a private term loan, make sure to pay on time and your credit score will improve over time. As a result, the better your credit score is, the lower your interest rates will be and you will have a greater chance to access financial lending markets.Borrowing is an inherent part of any business regardless of its size and the industry it operates in. Major financial institutions and private lenders usually lend to businesses with exceptional credit histories opposed to those with a bad one. Don’t let your bad credit history stop your business from getting the financing it needs. Options such as a merchant cash advance (MCA) will provide you with the required funding, as well as improve your credit card history in general. If you think it might be a good solution for you, do not hesitate to get in touch with us.

Related articles

October 6, 2026
October 15, 2026

Restaurant Equipment Financing in Canada: Your Options, What Providers Look At, and What Each Costs

Restaurant equipment financing lets a restaurant pay for ovens, refrigeration, hoods, dishwashers and POS systems over time instead of in one payment. Canadian restaurants have six main routes: leasing, vendor financing, bank or specialist equipment financing, BDC, the Canada Small Business Financing Program, and a merchant cash advance.

The right one depends on four things: how long the restaurant has been operating, its credit history, how quickly the equipment is needed, and whether the equipment is new or used. A planned kitchen upgrade gives you time to compare offers. An emergency replacement does not.

Restaurant margins leave little room for the wrong choice. Statistics Canada reports that food services and drinking places earned a 4.1% operating profit margin in 2024. Cost of goods sold took 35.9% of expenses, and salaries, wages and benefits took another 33.6%. A walk-in cooler that fails in July has to be paid for out of what is left.

This guide explains how each option works, what each provider looks at, what each costs, and where each one fits.

Your restaurant equipment financing options compared

These routes overlap. A dealer may arrange its financing through a bank or a specialist, and BDC is itself an equipment financing provider. The table separates the routes you will meet when you shop.

‍

Option How it works Best for Main limitation
Equipment leasing You pay to use the equipment for a set term, often with an option to buy it at the end Equipment you expect to replace or upgrade You do not own the equipment during the term
Vendor or dealer financing The dealer or manufacturer finances the purchase, directly or through a partner Speed and a low upfront cost Shorter terms and less flexibility than a term loan
Bank or specialist equipment financing A bank or financing company funds the purchase and usually secures it against the equipment Established restaurants buying long-life equipment Requires financial statements and forecasts
BDC Equipment Loan Covers up to 125% of the purchase price, repaid over up to 12 years Restaurants with at least 12 months of revenue and a good credit record Not open to restaurants with under 12 months of revenue
Canada Small Business Financing Program A government-backed term loan, applied for through a financial institution Start-ups and existing restaurants that can qualify with a bank or credit union A 2% registration fee, and the institution makes the lending decision
Merchant cash advance An advance on future sales, repaid from revenue Urgent replacements, repairs, or cases where credit rules out other options Typically costs more than bank financing

Need to replace equipment and keep your operating cash intact? See 2M7's restaurant equipment and operations funding, including who qualifies and how payments work.

How much does restaurant equipment financing cost?

There is no single rate for restaurant equipment financing in Canada. Your quote depends on the provider, your restaurant's finances, the equipment, the amount and the length of the agreement.

To compare offers fairly, ask every provider the same six questions about the same purchase:

  1. How much cash do I pay up front, including any deposit or down payment?
  2. What is each payment, and how often is it collected?
  3. What is the total I will pay, including all financing charges and fees?
  4. Is there a final payment or a buyout before I own the equipment?
  5. What happens if I pay the balance early?
  6. Do the payments change if my sales fall?

A longer term lowers each payment and raises the total you pay. A low lease payment can also leave out the buyout you need to take ownership.

Route How the cost is expressed What to compare
Leasing Lease payments, fees and any buyout The full cost to use the equipment, and the full cost to own it if that is your goal
Vendor or dealer financing Interest or other financing charges set by the seller or its partner The financing offer against the dealer's cash price and one other quote
Bank, specialist or BDC financing Interest and fees Total interest, fees, your upfront contribution and the payment schedule
CSBFP term loan Fixed or floating interest, plus a 2% registration fee The rate you are quoted against the program's ceiling
Merchant cash advance A fixed cost of capital, set before you sign The amount you receive, the total you repay, and how often payments are collected

The CSBFP is the one route with a published ceiling. The maximum floating rate is the lender's prime rate plus 3%, and the maximum fixed rate is the lender's single-family residential mortgage rate plus 3%. The registration fee is 2% of the loan. These are limits, and your own quote may be lower.

A merchant cash advance carries no interest rate, but it does carry a cost. Ask for the dollar amount you will receive and the dollar amount you will repay, in writing, before you decide.

Restaurant equipment leasing

Restaurant equipment leasing lets you use equipment for a fixed term in exchange for regular payments, without buying it at the start. Many leases include an option to purchase the equipment when the term ends.

BDC's guidance is that leasing suits equipment with a shorter lifespan or equipment that needs frequent updating, while buying suits equipment that will last. In a restaurant, that points to leasing for POS hardware and other technology, and to buying for ranges, hoods and walk-in coolers that stay in service for years.

Before you sign a lease, ask four questions. Who pays for maintenance? Can you swap the equipment during the term? What does the end-of-term buyout cost? What happens if the restaurant moves or closes?

Leasing also changes how the cost is treated at tax time. The Canada Revenue Agency lets a business deduct the lease payments incurred in the year for property used in the business. If the leased property has a total fair market value above $25,000, you and the lessor can jointly elect to treat the lease as a purchase. You would then deduct the interest portion and claim capital cost allowance on the equipment. Ask your accountant which treatment fits your restaurant.

What a lessor looks at: the equipment itself, the length of the term, and your restaurant's ability to make the payments.

Vendor and dealer financing

Vendor financing means the company selling the equipment also arranges the financing. BDC describes it as financing provided through a manufacturer's financing division or a partner financial institution.

The appeal is convenience. You choose the equipment and arrange payment in the same conversation, and BDC notes that vendor financing is fast and carries lower upfront costs.

The trade-off is flexibility. BDC describes vendor financing as shorter term and less flexible than a traditional term loan. Before you sign, compare the total you will pay against at least one other option on this page.

Ask for the equipment's cash price separately from the financing offer, so you can see what the financing itself costs. Choose the equipment first, on the model, warranty and servicing your kitchen needs. A supplier's financing offer should not decide what you buy.

What a vendor looks at: this varies by dealer and by the financing partner behind it. Ask who the actual financing provider is and what happens if you want to pay the balance early.

Bank and specialist equipment financing

Banks and specialist equipment financing companies fund the purchase of business equipment and assess both the business and the asset. According to BDC, the equipment is used as collateral most of the time, and the repayment period is matched to the equipment's lifespan.

This route suits an established restaurant buying equipment that will last. The paperwork is heavier than with a vendor. BDC lists what equipment financing providers commonly ask for:

  • Financial statements for the past two years
  • A monthly cash flow forecast for the rest of the current year and the following 12 months
  • Background on the company, its operations and its management
  • An explanation of how the equipment will increase sales, profitability or efficiency

Requirements vary with the provider and the size of the request. Ask whether the offer covers delivery and installation. Financing that covers only the equipment can leave a cash gap before the kitchen can use it.

What a bank or specialist looks at: the restaurant's financial history, its forecast, and the resale value of the equipment.

BDC equipment financing

The Business Development Bank of Canada offers an Equipment Loan for new or used equipment. Its terms are among the longest available to a Canadian restaurant:

  • Financing of up to 125% of the purchase price, which leaves room for shipping and installation
  • Repayment over up to 12 years
  • The option to postpone capital payments for up to 24 months at the start

Eligibility is the constraint. BDC requires the business to be based in Canada, to have generated revenue for at least 12 months, and to have a good credit track record.

Postponing capital payments delays the principal. It does not remove the cost of financing, so check what the payment becomes once principal repayment starts.

What BDC looks at: revenue history of 12 months or more, and credit record. A restaurant that opened this year, or one with damaged credit, will need a different route.

Canada Small Business Financing Program

The Canada Small Business Financing Program (CSBFP) is a federal program that shares the risk of a loan with the financial institution that makes it. You apply through a bank or credit union, and that institution alone decides whether to approve the loan. Most start-ups and existing small businesses with gross revenues of $10 million or less can apply.

The program allows a business to borrow up to $1.15 million: a maximum of $1 million in term loans and $150,000 in lines of credit. Term loans can pay for new or used equipment.

The full $1 million is not available for kitchen equipment alone. The program sets a lower limit for equipment and leasehold improvements, so confirm the current figure with your financial institution before you plan a purchase around it.

The program also caps the cost. The maximum floating rate is the lender's prime rate plus 3%, and there is a registration fee of 2% of the loan.

Restaurants use this program more than any other sector. In 2024-25, accommodation and food services received $900.9 million, or 47.8% of the total value of CSBFP loans. Equipment loans made up 18.6% of the total.

What the financial institution looks at: the same things it would for any business loan, including financial statements, forecasts and credit history. The program reduces the institution's risk. It does not remove its approval process, so allow time for it.

Financing used restaurant equipment

Used restaurant equipment can be financed. BDC's Equipment Loan and CSBFP term loans both cover new or used equipment, and other providers set their own rules.

A used range or dishwasher costs less up front, which shrinks the amount you need to finance. It also gives a financing provider less security, because older equipment is worth less if it has to be resold.

Before you pay a deposit on a used purchase, ask each provider four questions:

  1. Is there a limit on the age or condition of the equipment you will finance?
  2. Do you need an appraisal, an inspection report or proof of ownership?
  3. Will you finance a purchase from a private seller or an auction, or only from a dealer?
  4. Are delivery, installation and any repairs included?

Compare the installed cost of the used unit against a new one, including warranty and servicing. A lower price helps less if the unit breaks down soon after it goes in.

If the answers rule out conventional financing, a merchant cash advance is one way to fund a used purchase, because the funding is based on your sales and not on the equipment.

Restaurant equipment financing with bad credit

Bad credit narrows your options without closing all of them. BDC notes that there is no specific credit score needed to get a business loan, and that financing can still be obtained with a suboptimal score when other factors, such as projections and collateral, are strong.

In practice, a weak credit history makes bank-delivered options harder to secure and pushes restaurants toward providers that weigh revenue more heavily. 2M7 bases approval on recent sales activity, and credit score is one factor among several.

For a full comparison of what each provider checks and what each option costs, read Bad Credit Equipment Financing in Canada.

Financing equipment for a new restaurant

A restaurant that has not opened yet, or has just opened, has fewer options because it has no revenue history to show.

Stage What is realistic
Before opening Leasing, vendor financing, or a CSBFP loan through a financial institution
Open less than 3 months The same three options
Open 3 to 12 months The options above, plus a merchant cash advance from 2M7 if monthly revenue is at least $15,000
Open 12 months or more All six options, including the BDC Equipment Loan

Without revenue history, a provider relies on your business plan, your forecast and your personal credit. Have all three ready before you approach a lessor, a vendor or a bank.

When a merchant cash advance makes sense for restaurant equipment, and when it does not

A merchant cash advance is an advance on your restaurant's future sales. You receive a lump sum and repay it from revenue, with the total cost set before you sign. It is not secured against the equipment.

It has no interest rate, but it has a cost: a fixed amount set at the start. Compare that cost against the sales you lose each day the kitchen is down.

It makes sense when:

  • The equipment has failed and the kitchen cannot run without it. A dead walk-in cooler or range costs you sales every day it is out, and a bank process measured in weeks does not help.
  • The cost is a repair, an installation or a compliance fix. Conventional equipment financing is built around buying an asset, and these costs do not always qualify.
  • You are buying used equipment from a private seller or an auction that an equipment financing provider will not fund.
  • Your credit history or time in business rules out BDC and bank options, but your sales are steady.

It does not make sense when:

  • The purchase is large, planned and long-lived. If you qualify for a BDC Equipment Loan or a CSBFP loan and can wait for approval, a term of up to 12 years will usually cost less than a merchant cash advance.
  • Sales are too thin to carry the repayments. Funding tied to revenue only works if the revenue is there.
  • The restaurant has been open less than 3 months or brings in under $15,000 a month. It will not qualify with 2M7.

The practical test is whether your restaurant can carry the repayments and still cover food, wages and rent. Run the numbers against a slow month, not your busiest one.

How to prepare before applying

Having the right documents ready shortens every one of these processes. What you need depends on the route.

For leasing, vendor financing, specialist financing, BDC or the CSBFP:

  • A written quote or purchase agreement for the equipment
  • Financial statements for the past two years
  • A monthly cash flow forecast
  • A short explanation of what the equipment will do for the restaurant: more covers, lower energy bills, fewer breakdowns
  • Your premises lease, since a provider may want to know how long you can stay at the location

For a merchant cash advance from 2M7:

  • Three months of business bank statements
  • Photo ID
  • A void cheque

Get two quotes for the equipment before you apply anywhere. A lower purchase price reduces the amount you finance under every option.

Then budget for the whole project: the equipment, delivery, installation and removal of the old unit.

How 2M7 funding works for restaurant equipment

2M7 Financial Solutions is a direct funder that provides merchant cash advances of $5,000 to $300,000 to Canadian businesses. Restaurants use the funding for ranges, walk-in coolers, POS systems, dining room furniture and compliance repairs.

To qualify, your restaurant needs to:

  • Be located in Canada
  • Have been operating for at least 3 months
  • Bring in at least $15,000 a month in revenue
  • Have no open bankruptcies

Meeting these minimums does not guarantee approval. 2M7 reviews each application.

Approval takes one business day, and funds arrive in your account within 24 hours of approval. No collateral is required.

You see the total cost before you sign. There is no interest, and there is no penalty for paying early. You choose between two repayment structures. Flex payments move with your daily card sales. Fixed payments stay the same unless you call 2M7 to request a lower amount when revenue drops.

2M7 has funded more than 5,000 small businesses and issued more than $650 million since 2008.

See how this applies to your kitchen on the restaurant equipment and operations funding page, or check if you qualify.

‍

‍

Frequently asked questions

What is restaurant equipment financing?

Restaurant equipment financing is any arrangement that lets a restaurant pay for kitchen, bar or front-of-house equipment over time. In Canada the main forms are leasing, vendor financing, bank or specialist equipment financing, a BDC Equipment Loan, a CSBFP loan and a merchant cash advance.

How much does restaurant equipment financing cost?

There is no single rate. Ask each provider for the upfront cash, the payment amount, the total you will repay and any buyout. Under the CSBFP, the floating rate cannot exceed the lender's prime rate plus 3%, and there is a 2% registration fee.

Is it better to lease or buy restaurant equipment?

Lease equipment you expect to replace or upgrade, such as POS hardware. Buy equipment that will stay in service for years, such as ranges and walk-in coolers. Check who pays for maintenance and what the buyout costs before you sign a lease.

Can I finance used restaurant equipment in Canada?

Yes. BDC's Equipment Loan and CSBFP term loans both cover new or used equipment. Other providers set their own limits on age, condition and seller, so ask before you pay a deposit.

Can I get restaurant equipment financing with bad credit?

Yes, though the options narrow. BDC notes that no specific credit score is required for a business loan. Providers that base approval on revenue, including 2M7, can fund restaurants that a bank would decline.

Can a new restaurant get equipment financing?

A restaurant with no revenue history can apply for leasing, vendor financing or a CSBFP loan, which is open to most start-ups. BDC's Equipment Loan requires 12 months of revenue. 2M7 requires 3 months in operation and $15,000 in monthly revenue.

Does the CSBFP provide $1 million for kitchen equipment?

No. The program allows up to $1 million in term loans, but a lower limit applies to equipment and leasehold improvements. Your financial institution decides the amount it will approve.

How long can I take to repay a BDC Equipment Loan?

Up to 12 years. BDC also allows capital payments to be postponed for up to 24 months at the start of the loan.

Are restaurant equipment lease payments tax deductible?

The Canada Revenue Agency lets a business deduct lease payments incurred in the year for property used in the business. Confirm how this applies to your restaurant with your accountant.

How fast can I get funding to replace broken kitchen equipment?

It depends on the route. 2M7 approves applications within one business day and deposits funds within 24 hours of approval. Bank-delivered options take longer because they require financial statements and forecasts.

Does a merchant cash advance have a cost?

Yes. It carries a fixed cost of capital in place of an interest rate. Compare the amount you receive, the total you repay and how often payments are collected before you accept an offer.

What documents do I need to apply?

For most equipment financing: an equipment quote, financial statements and a cash flow forecast. For a merchant cash advance from 2M7: three months of bank statements, photo ID and a void cheque.

Choosing the right option

Start with how much time you have. If the purchase is planned and your restaurant has at least 12 months of revenue and sound credit, begin with BDC or a CSBFP loan through your bank. The terms are the longest available.

If you are buying from a dealer and want one conversation, ask for the vendor's financing terms and compare the total cost against a second option.

If the equipment has already failed, your credit is damaged, or your restaurant is too new for BDC, look at funding that is based on your sales. Check if your restaurant qualifies with 2M7.

‍

Read more
October 16, 2026
October 16, 2026

Best business loans for bad credit in Canada 2026

Best for qualifying businesses seeking working capital: 2M7, a direct funder offering merchant cash advances, not loans. Best for unpaid business invoices: invoice factoring; best for a specific equipment purchase: equipment financing. This 2026 guide compares those options with secured business loans and business lines of credit so you can match funding to your cash flow, not just your credit score.

TL;DR

  • Searching business loans for bad credit Canada? Compare eligibility, payment structure and total repayment before choosing.
  • 2M7 suits established revenue-generating businesses seeking a merchant cash advance, not a traditional business loan.
  • Invoice factoring suits eligible unpaid business invoices; equipment financing suits a specific asset purchase.
  • Poor credit does not establish eligibility. Revenue, operating history, collateral and provider requirements also matter.

Why this matters

The best funding option fits both your business and its ability to repay. A product that accepts your application still needs to leave enough cash for payroll, rent, suppliers and taxes.

For Canadian business owners comparing options in 2026, the first distinction is between a loan and a merchant cash advance. They are different funding structures. Compare the agreement, payment obligations and total repayment rather than treating every source of working capital as interchangeable.

You also need to separate eligibility from suitability. Being eligible answers whether a provider will consider your business; being suitable answers whether the funding helps without creating a larger cash flow gap.

What makes the best bad-credit business funding?

Use these criteria to assess your 2026 shortlist before applying:

  • Eligibility fit: Check minimum operating history, revenue requirements and how the provider assesses credit.
  • Purpose fit: Match general working capital, unpaid invoices or an equipment purchase to the appropriate structure.
  • Payment fit: Confirm the payment amount or calculation, frequency and collection method.
  • Cost clarity: Request the total repayment obligation and every applicable fee in writing.
  • Security exposure: Identify collateral, personal guarantees and the consequences of default.
  • Provider accountability: Establish whether you are dealing with the funder directly or an intermediary.

Do not rank offers solely by the amount approved. A smaller commitment that fits your cash flow is more useful than funding you cannot comfortably service.

Bad-credit business funding at a glance

The order below follows the funding need, not a promise of approval. Each option has a distinct best-fit use case.

1. Merchant cash advance

  • Best for: Qualifying businesses seeking general working capital
  • Standout feature: An alternative to a traditional business loan
  • Key limitation: Payment obligations still need to fit operating cash flow

2. Invoice factoring

  • Best for: Businesses with eligible unpaid customer invoices
  • Standout feature: Converts eligible receivables into working capital
  • Key limitation: Depends on invoice and customer eligibility

3. Equipment financing

  • Best for: Businesses purchasing a specific asset
  • Standout feature: Ties financing to equipment rather than general spending
  • Key limitation: Does not solve unrelated operating shortfalls

4. Secured business loan

  • Best for: Businesses prepared to pledge acceptable collateral
  • Standout feature: Uses an asset as security
  • Key limitation: The pledged asset is exposed if obligations are not met

5. Business line of credit

  • Best for: Businesses with recurring, temporary funding gaps
  • Standout feature: Provides access to revolving credit under agreed terms
  • Key limitation: Access depends on approval and the continuing agreement

1. 2M7: best for qualifying working capital needs

A merchant cash advance provides business funding through a structure different from a traditional loan. The direct-funder model means you deal with the funding provider rather than a broker.

2M7 is best for Canadian businesses with at least 3 months of operating history and $15,000 in monthly revenue seeking merchant cash advance working capital. Businesses with less-than-perfect credit are among those it serves. Funding uses include payroll, inventory, equipment and cash flow gaps.

Merchant cash advance pros:

  • Supports several operating needs rather than a single asset purchase.
  • Provides an option for businesses with less-than-perfect credit.
  • Gives you direct access to the funder rather than a broker.

Merchant cash advance cons:

  • Minimum revenue and operating-history requirements exclude some businesses.
  • Approval is not certain; the published approval rate is 75%.
  • Funding commitments must fit the business's ongoing cash flow.

Best for: An operating business that meets the stated revenue and trading-history requirements and needs general working capital.

Before signing, request the payment schedule, total repayment obligation and default terms. Flex payments are available only to businesses that process daily card payments; do not assume that feature applies to every business.

Verdict: Buy only when the written terms fit your cash flow.

2. Invoice factoring: best for unpaid business invoices

Invoice factoring involves selling eligible accounts receivable to a factoring provider. It connects funding to invoices you have already issued rather than to a future equipment purchase or an unrestricted credit facility.

This structure fits a business waiting for customers to pay. Ask which invoices qualify, whether customers receive payment instructions from the factor, and who bears the risk if an invoice remains unpaid.

Invoice factoring pros:

  • Connects funding to existing receivables.
  • Addresses a gap between issuing invoices and collecting payment.
  • Gives invoice-based businesses a distinct alternative to borrowing.

Invoice factoring cons:

  • Does not fit a business without eligible receivables.
  • Customer creditworthiness and invoice disputes affect suitability.
  • Customer notification and collection arrangements need careful review.

Best for: A business with eligible unpaid commercial invoices and a clear collection process.

Compare recourse and non-recourse terms rather than relying on those labels alone. The agreement must explain exactly when the business remains responsible for an unpaid invoice.

Verdict: Buy for a receivables gap; skip if you have no eligible invoices.

3. Equipment financing: best for a specific asset purchase

Equipment financing funds an identified business asset. Depending on the agreement, the structure involves financing a purchase or leasing equipment rather than providing unrestricted working capital.

Use this route when the equipment itself is the reason you need funding. Review ownership, security, insurance requirements and end-of-term obligations before comparing it with a general-purpose alternative.

Equipment financing pros:

  • Matches financing to a defined business purchase.
  • Separates an asset decision from everyday operating spending.
  • Lets you assess the equipment's usefulness alongside its payment obligations.

Equipment financing cons:

  • Does not cover unrelated payroll or supplier gaps.
  • Approval still depends on provider requirements.
  • Ownership and end-of-term conditions differ between agreements.

Best for: A business purchasing equipment with a clear operational purpose and a repayment plan supported by business cash flow.

Do not assume the equipment will immediately generate enough revenue to cover its payments. Check delivery, installation and the point at which the asset becomes usable.

Verdict: Buy for a defined asset need; skip for a general operating shortfall.

4. Secured business loan: best for collateral-backed borrowing

A secured business loan uses an asset as security for repayment. The lender assesses both the application and the proposed collateral; owning an asset does not establish approval.

This option belongs on your shortlist when you are prepared to pledge acceptable property or business assets. Understand what is pledged, how it is valued and whether a personal guarantee creates additional exposure.

Secured business loan pros:

  • Gives a lender collateral to consider alongside the business application.
  • Provides a structure for borrowing against acceptable assets.
  • Supports a defined financing purpose under the lender's terms.

Secured business loan cons:

  • Pledged assets are exposed if repayment obligations are not met.
  • Asset valuation and legal requirements add steps.
  • Collateral does not remove credit or affordability checks.

Best for: A business owner who understands the security agreement and accepts the asset exposure.

Ask what happens if the business misses payments and how security is released after repayment. Obtain independent advice when the agreement puts significant business or personal assets at stake.

Verdict: Hold until you understand and accept the collateral obligations.

5. Business line of credit: best for recurring short-term gaps

A business line of credit provides revolving borrowing within an agreed limit. You draw funds as needed and repay according to the agreement rather than receiving only a single advance.

This structure fits recurring timing differences between business expenses and customer receipts. Poor credit remains an application issue, so confirm the lender's requirements before treating a line of credit as an available solution.

Business line of credit pros:

  • Supports repeated draws within the agreed facility.
  • Matches recurring short-term cash flow gaps.
  • Separates the approved limit from the amount actually drawn.

Business line of credit cons:

  • Access depends on credit approval and continuing terms.
  • Security or a personal guarantee can be required.
  • Repeated borrowing can conceal an unresolved operating deficit.

Best for: A business with recurring temporary gaps and a clear source of repayment.

Review renewal conditions, repayment demands and restrictions on use. Do not build essential spending around access you have not secured in writing.

Verdict: Buy for repeatable timing gaps; skip as a substitute for sustainable revenue.

How the options are ranked

This 2026 ranking prioritises purpose fit, stated eligibility, payment fit, cost clarity and security exposure. It is not a ranking of approval odds or a claim that one provider accepts every credit profile.

The merchant cash advance comes first for qualifying general working capital needs. The remaining options address different situations: unpaid invoices, an equipment purchase, collateral-backed borrowing and recurring cash flow gaps.

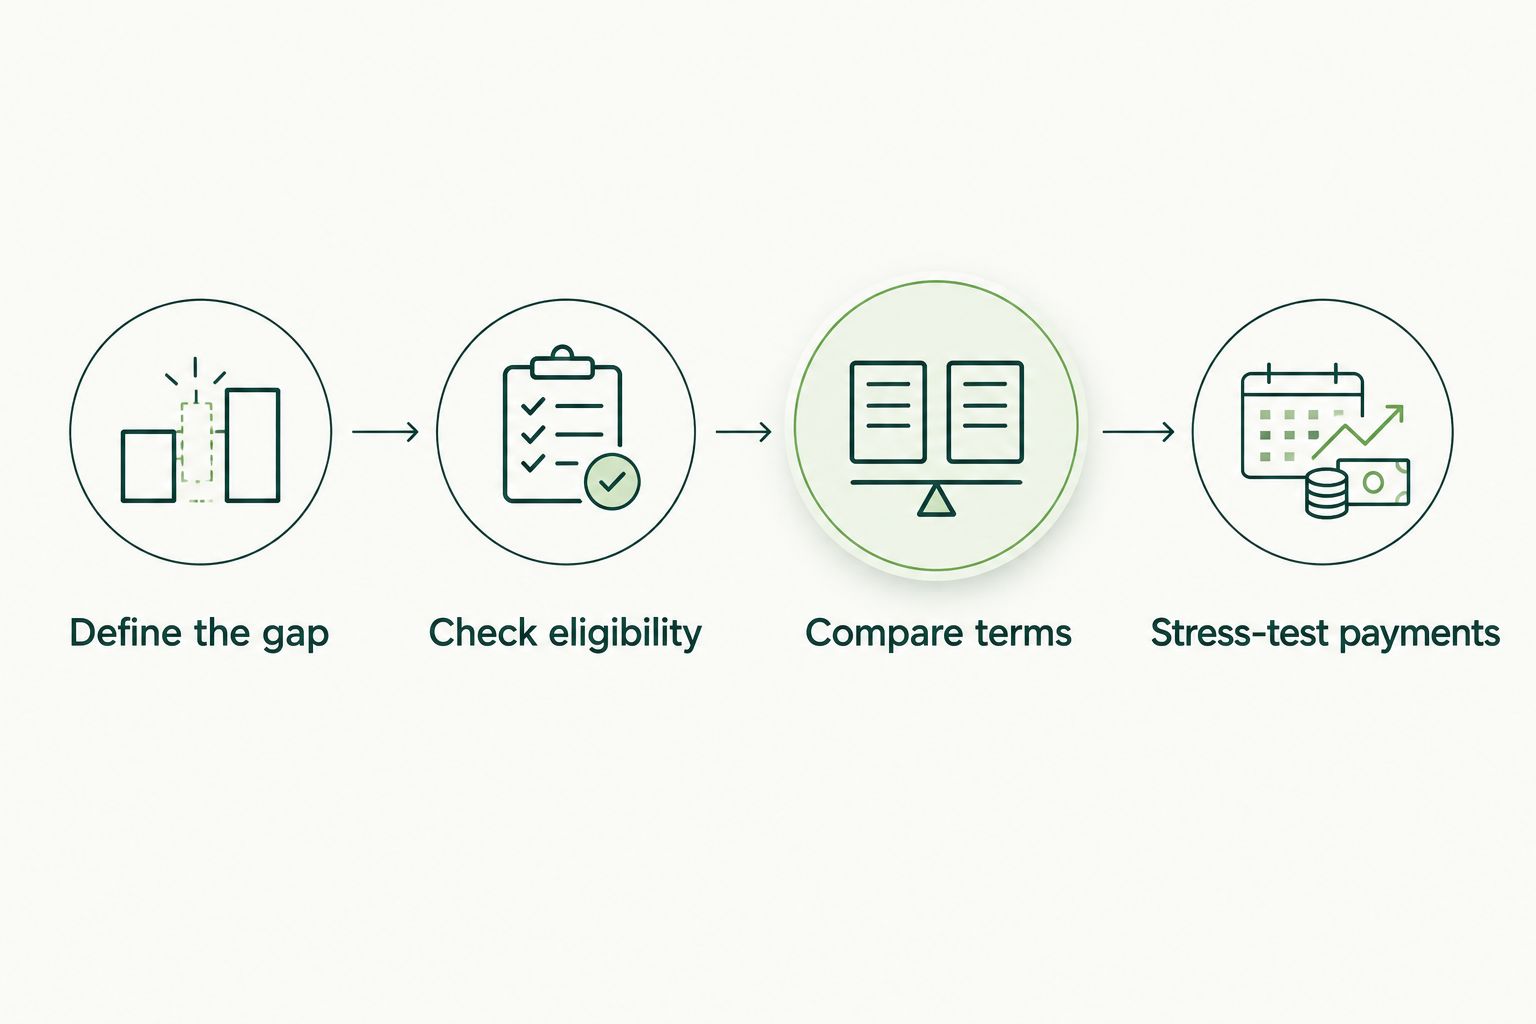
How to compare offers before signing

Define the gap

Name the expense and the source of repayment. Funding inventory before a known sales period is a different decision from covering a recurring loss with no identified improvement.

Check eligibility

Confirm operating history, monthly revenue, credit assessment and any collateral requirements. Ask whether the provider reviews personal credit, business credit or both, and whether an application involves a credit inquiry.

Compare terms

Request the total repayment obligation, payment frequency, collection method, guarantees and default provisions. Compare written offers on the same basis; a payment amount alone does not explain the commitment.

Stress-test payments

Put the proposed payments into your cash flow forecast alongside payroll, rent, tax obligations and supplier bills. Repeat the exercise using a slower sales period, not just your strongest month.

These steps separate an attractive offer from a workable one. Complete them before accepting funding, even when you already meet the provider's eligibility requirements.

Four steps for checking whether a business funding offer fits your needs

Check repayment fit before accepting an offer, not after funds arrive.

A useful comparison ends with a written decision: what the funding will accomplish, how the business will meet its obligations and which risks you accept. If those answers remain unclear, hold the application rather than choosing by approval alone.

Discuss your funding options

Speak with a funding specialist about your business needs and merchant cash advance eligibility.

Discuss funding options

Which business funding should you choose?

Choose 2M7 for merchant cash advance working capital when your Canadian business meets the stated eligibility requirements and the agreement fits your cash flow. Choose invoice factoring for eligible unpaid invoices or equipment financing for a specific asset.

For your 2026 decision, leave secured borrowing on hold until you understand the asset exposure. Consider a business line of credit when the need recurs and the lender's requirements fit your circumstances.

The default is not to apply everywhere. Start with the structure that matches the expense, then compare providers within that structure.

FAQ

What's the best business funding option if I have bad credit in Canada?

The best option depends on your revenue, operating history, funding purpose and ability to meet payments. Compare merchant cash advances for general working capital, factoring for eligible invoices and equipment financing for a specific asset.

Does 2M7 offer business loans for bad credit?

2M7 offers merchant cash advances and working capital, not business loans. It serves Canadian businesses with less-than-perfect credit that meet its requirements, including at least 3 months in operation and $15,000 in monthly revenue.

Can a new business qualify for a merchant cash advance?

A new business must meet the provider's operating-history and revenue requirements. Check those thresholds before applying; a business without established revenue should not assume eligibility.

Is a merchant cash advance the same as a business loan?

No, a merchant cash advance is a different funding structure from a traditional business loan. Review the agreement's payment mechanism, total repayment obligation and default terms rather than comparing labels alone.

Will applying for business funding affect my credit score?

The effect depends on the provider's credit-check process. Ask whether it performs a hard or soft inquiry, whose credit it checks and when consent is required.

Is secured funding automatically approved if I own equipment?

No, owning equipment does not establish approval for secured funding. The lender still assesses the application, the asset's acceptability and the proposed repayment arrangement.

What should I compare besides the payment amount?

Compare the total repayment obligation, payment frequency, fees, security, guarantees and default provisions. Also check early-payment terms and whether the agreement allows changes to payment obligations.

One last thing

A smaller payment is not automatically a smaller commitment. Payment frequency and repayment duration change what a payment figure means, so request the full schedule and total repayment obligation together.

Before signing in 2026, identify the slowest normal sales period in your business records. Check whether the proposed obligation still leaves enough cash for essential expenses during that period.

Related guides

Read more
June 26, 2026
July 27, 2026

What’s the Difference between MCA and Business Loan?

Merchant Cash Advance vs. Business Loan: Which One Is Right for Your Business?

Most Canadian small business owners will need outside capital at some point. The question is rarely whether to get it, but which type actually makes sense for where the business is right now.

The Traditional Route: Business Loans 

A business loan gives you a fixed amount of capital repaid in monthly installments over an agreed term. The schedule is set from day one and you always know exactly what you owe, which makes it a solid fit for longer-term investments with predictable returns.

Canada also has a government-backed option worth knowing about. Canada's Small Business Financing Program, administered by ISED, partners with banks and credit unions to make loans available to businesses that might not otherwise qualify for conventional financing. In 2024-25, the program supported over 6,400 loans totalling close to $1.9 billion.

The tradeoff is access. Banks want clean financials, strong credit, and often collateral. For many small business owners, those requirements are the whole problem.

How a Merchant Cash Advance Is Different

A merchant cash advance advances you a lump sum against your future revenue. Repayment comes as a fixed percentage of your daily or weekly sales, drawn automatically until the balance is paid off. Slow week, less comes out. Strong week, you pay it down faster.

The cost is structured through a factor rate rather than an interest rate, making an MCA a higher-cost product than a bank loan in most cases. What it offers in return is speed, flexibility, and a qualification process built around your sales history rather than your credit score. Businesses turned down by banks due to credit history or limited operating time often qualify here, and funding can land in your account within a day or two.

Picking the Right Tool

A business loan makes sense when you have the credentials to qualify, the investment is long-term, and you have time for the application process. A merchant cash advance makes sense when you need capital fast, your revenue is the stronger part of your financial picture, or you need repayment that moves with your business. This holds true across industries whether you are in retail, restaurants, construction and trades, or trucking. The right product depends less on what you do and more on what you need the money for and how fast you need it.

If you want a straight conversation about which option fits your situation, feel free to reach out to us.

‍

Read more