ClickCease

2M7 Announces 2022 “Forward Thinkers Scholarship” for Business and Finance Students in Canada

2M7 Announces 2022 “Forward Thinkers Scholarship” for Business and Finance Students in Canada

2M7 Announces 2022 “Forward Thinkers Scholarship” for Business and Finance Students in Canada
25
May 2022
27
Jul 2026

2M7 Financial Solutions is proud to announce its annual Forward Thinkers Scholarship to support Canadian post-secondary students in Business, Finance, or equivalent programs who are forward-thinking individuals dedicated to making a difference in their fields. The selected recipient will have demonstrated excellence in their studies and will receive $2,500.00 CAD towards their continued success.“

Students are the future of our industry and we welcome the new perspectives and fresh ideas they bring to the table,” said Avi Bernstein, CEO of 2M7 Financial Solutions. “We’re proud to support passionate and talented individuals in the pursuit of their education, and we welcome all Business and Finance majors to apply for an opportunity to receive the Forward Thinkers Scholarship in 2022.”

As one of Canada’s leading merchant cash advance providers, 2M7 Financial Solutions helps Canadian small and medium businesses secure the funding they need to accelerate their growth. As a client-centric company, 2M7 values the entrepreneurs who are the backbone of the Canadian SME economy and believes in empowering business owners and enabling them to achieve their full potential. Similarly, 2M7 believes it’s important to give students the opportunity to excel in their fields and bring cutting-edge ideas that will help drive the industry forward.

The selected recipient will encompass 2M7’s values of innovation and demonstrate a genuine desire to make innovative strides within their respective field.

To learn more about the scholarship or to start the application, please visit the Forward Thinkers Scholarship page here.

Applications will be accepted beginning June 1st, 2022, and the deadline to apply is 11:59 PM on August 31, 2022. Winners will be announced in the Fall of 2022.

About the “forward thinkers scholarship” by 2M7

The ”Forward Thinkers Scholarship” by 2M7 is an annual scholarship program, established in 2022 by 2M7 Financial Solutions. It recognizes outstanding students who are pursuing or entering full-time studies in Business, Finance, or an equivalent program. For those interested in applying for the 2022 scholarship, please make sure to follow 2M7 on Facebook for further announcements.

Related articles

October 16, 2026
October 16, 2026

Best merchant cash advance options for small businesses 2026

Best for a direct-funder relationship: 2M7. Best for card-sales-linked payments: a merchant cash advance with that structure explicitly written into the agreement. Best for an intermediary-led search: a broker-arranged advance. This 2026 guide compares those routes and explains when a business line of credit is the better alternative.

TL;DR

  • For merchant cash advance options Canada businesses can compare, 2M7 fits owners seeking a direct funder.
  • Card-sales-linked payments suit daily card-processing businesses; confirm exactly how payments respond to sales.
  • A broker arranges funding rather than providing it directly; identify the actual funder before signing.
  • A business line of credit is an alternative for recurring borrowing, not a merchant cash advance.

Why this matters

A merchant cash advance provides business funding against future sales, with collection terms set out in an agreement. It differs from a conventional business loan. Your decision should centre on the amount your business receives, the total contractual obligation and how collections affect operating cash flow.

The options below are not interchangeable products. Direct funding describes who provides the capital. Card-linked payments describe how collections work. A broker describes an intermediary. One agreement can combine these features.

Choose the payment structure your business can sustain, then choose the funding relationship. A familiar label does not tell you whether the agreement fits your payroll, supplier bills or sales cycle.

What makes the best merchant cash advance option?

Use these criteria to compare merchant cash advance options in Canada in 2026:

  • Funding relationship: Establish whether you are dealing with the funder or an intermediary. Know who approves the application and manages the account.
  • Eligibility fit: Check operating history, monthly revenue and any payment-processing requirements before applying.
  • Collection structure: Identify whether payments follow card sales or use another collection arrangement. Read the actual formula.
  • Total obligation: Compare the amount received with the complete amount payable. Ask for every contractual charge in writing.
  • Cash-flow fit: Test the collections against a slower sales period, not just your strongest month.
  • Contract clarity: Review early-payment conditions, security requirements and what happens when payments are missed.

Do not rank an offer by approval speed alone. Funding that arrives quickly still needs to leave enough operating cash for the work it is meant to support.

Merchant cash advance options at a glance

This 2026 comparison ranks decision routes, not competing branded products. The line of credit appears as a clearly marked alternative because recurring access to funds is a different need from a single advance.

2M7 direct-funded merchant cash advance

  • Best for: Owners seeking a direct funding relationship
  • Standout feature: Direct funder rather than a broker
  • Key limitation: Minimum operating-history and revenue requirements apply

Card-sales-linked merchant cash advance

  • Best for: Businesses processing daily card payments
  • Standout feature: Collections tied to card sales where the agreement specifies it
  • Key limitation: Not a fit for businesses without qualifying card processing

Broker-arranged merchant cash advance

  • Best for: Owners wanting an intermediary to approach funders
  • Standout feature: A separate party manages the funding search
  • Key limitation: The broker is not the source of capital

Business line of credit

  • Best for: Businesses needing recurring draws and repayments
  • Standout feature: Reusable borrowing access, subject to the agreement
  • Key limitation: A loan alternative to an advance, with its own underwriting requirements

1. 2M7: best merchant cash advance for direct-funder access

This Canadian direct funder provides merchant cash advances and working capital to small and mid-sized businesses. You deal with the funding provider rather than a broker. Funding uses include payroll, inventory, equipment and cash-flow gaps.

The stated eligibility baseline is at least 3 months in business and $15,000 in monthly revenue. Businesses with less-than-perfect credit are within its stated audience, but eligibility is not an approval decision.

Best for: An operating Canadian business that meets those thresholds and wants a direct relationship with its funder.

2M7 pros

  • Direct funding means there is no broker between your business and the capital provider.
  • The stated audience includes businesses with less-than-perfect credit.
  • One fixed cost of capital is shown before signing and does not change based on how long repayment takes.
  • Existing clients can text or call their funding representative directly.

2M7 cons

  • Businesses below the operating-history or monthly-revenue thresholds do not meet the stated baseline.
  • Flex payments are only for businesses that process daily card payments.
  • Meeting the baseline does not establish that the proposed collections fit your cash flow.

The published approval rate is 75%, not an individual promise. Assess the written offer on its own terms, including the collection arrangement and the cash your business retains after payments.

Verdict: Buy only after confirming that the written obligation and collection schedule fit your operating budget.

2. Card-sales-linked advances: best for daily card-processing businesses

A card-sales-linked merchant cash advance uses card receipts as the basis for collections where the agreement specifies that arrangement. This structure is relevant when your business processes daily card payments and wants collections connected to those receipts.

Do not assume every merchant cash advance works this way. The label alone does not establish the collection percentage, payment frequency or treatment of sales outside the card channel.

Best for: A business with daily card transactions that can verify the relationship between card sales and collections.

Card-sales-linked advance pros

  • The agreement can connect collections to the payment channel your business uses daily.
  • A clearly stated collection formula lets you model the effect of different card-sales levels.
  • Reviewing card receipts alongside collections helps you assess the operating cash left for other bills.

Card-sales-linked advance cons

  • Businesses without qualifying daily card processing need a different structure.
  • Card receipts alone do not show your full cash position, including supplier payments and payroll.
  • Sales-linked collections do not remove the contractual obligation or make the funding cost disappear.

Ask the funder to explain how refunds, chargebacks and processing changes affect collections. Get the answers in writing rather than relying on a general description of flexibility.

Verdict: Buy only when the agreement explicitly links collections to card sales and your cash-flow forecast supports it.

3. Broker-arranged advances: best for an intermediary-led search

A merchant cash advance broker helps arrange funding from another provider. The broker is an intermediary, not the business supplying the capital. That distinction matters when you need to understand who makes decisions and who handles the account after funding.

The value of this route depends on the actual search process. Ask which funders the broker approaches, how information is shared and how compensation works before submitting documents.

Best for: An owner who wants an intermediary to manage a funding search and is prepared to check the underlying funder independently.

Broker-arranged advance pros

  • An intermediary can coordinate the application process with the funders it works with.
  • The broker can help explain the offers it presents.
  • You can assess its proposed search process before authorising submissions.

Broker-arranged advance cons

  • A broker's presence does not establish that every relevant funding option has been considered.
  • You must distinguish the broker's responsibilities from the funder's contractual obligations.
  • Compensation and information-sharing arrangements need separate scrutiny.

Compare written agreements, not just the broker's summary. Identify the legal funding counterparty, the party collecting payments and the contact responsible for account questions.

Verdict: Hold until you understand the funder, the broker's role and every disclosed charge.

4. Business lines of credit: best alternative for recurring draws

A business line of credit is borrowing access that lets you draw funds up to an approved limit, subject to the agreement. Repayments can restore available borrowing capacity under its terms. It is not a merchant cash advance.

Include this alternative when your real need is repeated access to working capital rather than one defined funding amount. Compare the lender's underwriting, interest, charges and account conditions with the advance being considered.

Best for: A business that needs recurring draws and can satisfy the lender's requirements.

Business line of credit pros

  • You can draw funds as needed within the approved facility's terms.
  • Repayment can restore borrowing capacity rather than requiring a separate advance.
  • The structure supports a recurring funding need when the facility remains in place.

Business line of credit cons

  • Approval and account terms depend on the lender's underwriting requirements.
  • Interest, charges and security requirements need careful comparison.
  • Access remains subject to the agreement rather than being an unconditional reserve.

A line of credit is not automatically the right answer. Match its draw rules and repayment requirements to your actual collection cycle, especially when customer payments arrive after supplier bills fall due.

Verdict: Buy if recurring access is the need and the facility's terms fit; skip it as a substitute for fixing persistent operating losses.

How to compare written offers before signing

In 2026, use the same business forecast for every offer. Otherwise, you risk comparing one proposal against an optimistic month and another against a conservative month.

Define the need

Name the expense and the business outcome it supports. Payroll, inventory replenishment and equipment purchases have different cash-flow patterns. Separate the amount needed for that purpose from any additional amount offered.

Confirm eligibility

Check the stated revenue, operating-history and processing requirements. Explain your revenue sources accurately. A business paid mainly by invoices should not evaluate a daily-card-processing requirement as though those payment channels were identical.

Review collections

Write down when collections occur and what determines their size. Identify the business account or payment channel involved. Ask what the agreement requires if sales fall or a scheduled payment cannot be completed.

Test cash flow

Place the proposed collections beside payroll, rent, supplier commitments and existing obligations. Use your own slower-period records rather than an invented industry average. The useful result is the cash left to operate, not simply whether the collection can clear.

Read conditions

Review early payment, additional funding, missed payments, security and any personal obligations. Ask for unclear terms to be explained before signing. Keep the signed agreement and disclosures together for reference.
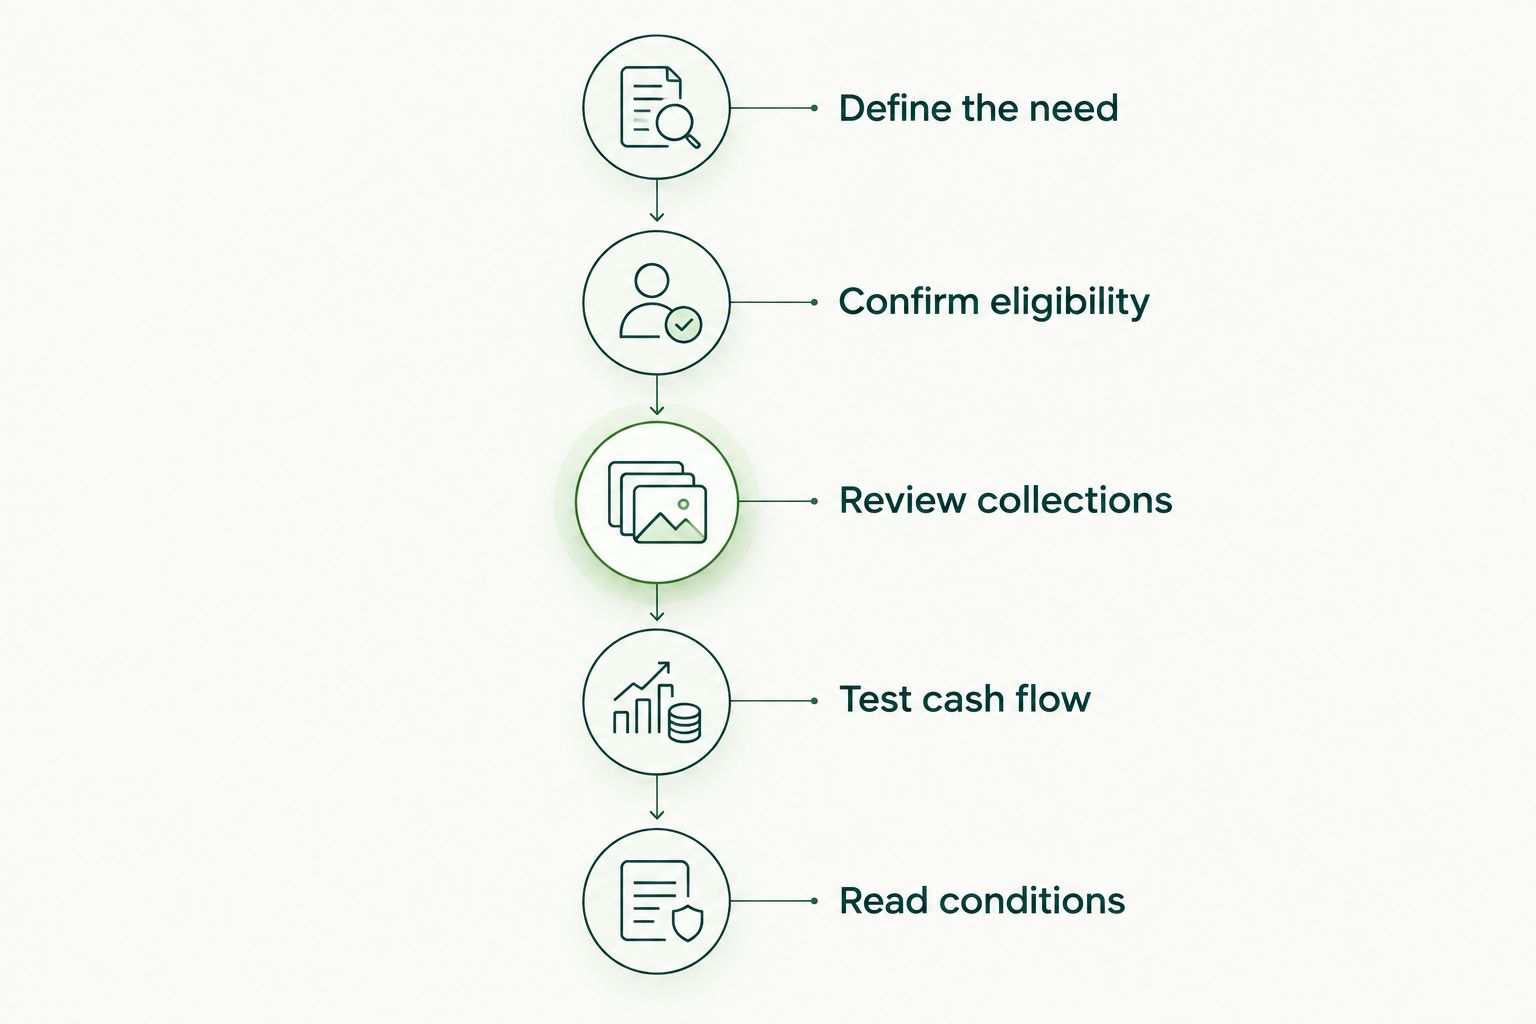
Five steps for checking a business funding offer before signing

Check operating cash flow before accepting the agreement.

The final comparison should make the trade-off visible: how much operating cash the funding adds now, what your business must pay under the agreement and what remains available for ordinary expenses.

How this ranking works

The 2026 ranking prioritises a clear funding relationship, eligibility fit, collection transparency and a distinct use case. It does not treat direct funding, broker involvement and card-linked collections as mutually exclusive products.

The first recommendation answers who you deal with. The second addresses payment structure. The third addresses how you search. The fourth tests whether a different borrowing structure better matches recurring needs.

Which merchant cash advance option should you choose?

2M7 is best for Canadian business owners seeking a direct-funded merchant cash advance without a broker. Start there if that relationship is your priority and you meet the stated operating-history and revenue thresholds.

If daily card receipts drive your cash flow, scrutinise the collection formula next. If you prefer an intermediary-led search, check the broker's role and the underlying funder separately. If you need repeated draws, compare a business line of credit before committing to an advance.

For a 2026 decision, choose the agreement your business can support during a slower period, not the largest amount offered. Discuss your funding options with a funding specialist and ask for the complete terms before deciding.

FAQ

What's the best merchant cash advance option in Canada?

The best option is the one whose eligibility requirements, collection structure and contractual obligation fit your business. Choose a direct funder for a direct funding relationship, and assess card-linked collections separately from who supplies the capital.

Is a merchant cash advance a business loan?

A merchant cash advance is not a conventional business loan. It provides business funding against future sales under an agreement, so compare its actual terms rather than treating it as interchangeable with a line of credit.

Does every merchant cash advance adjust payments when sales fall?

No, the merchant cash advance label does not establish how collections change with sales. Check the written formula and ask the funder to explain what happens during a slower period.

Is a direct funder better than a broker?

A direct funder suits owners who want to deal with the capital provider rather than an intermediary. A broker suits owners who want help arranging a funding search, but the underlying funder's agreement still needs independent review.

Can a business with less-than-perfect credit apply?

Less-than-perfect credit does not rule out every merchant cash advance option. Check each provider's stated eligibility requirements, and distinguish permission to apply from an actual approval decision.

What should I compare besides the funding amount?

Compare the complete contractual obligation, collection frequency, collection formula and early-payment conditions. Test those terms against payroll, suppliers and other existing commitments using your own cash-flow records.

When is a business line of credit a better alternative?

A business line of credit fits a recurring need for draws and repayments when your business meets the lender's requirements. It is a different borrowing structure, so compare underwriting, interest, charges and account conditions rather than assuming it works like an advance.

One last thing

A payment that changes with sales and a cost that changes over time are different features. Do not confuse them. Ask two separate questions: what determines each collection, and what determines the total contractual obligation?

That distinction makes a funding conversation more useful. You can evaluate flexibility without assuming it changes what the agreement requires your business to pay.

Related guides

Read more
September 7, 2026
October 12, 2026

Four Small-Business Trends Canadian Owners Should Act On

Business trends are useful when they lead to better decisions. For Canadian small-business owners, four shifts now affect everyday operations: cyber risk is becoming more sophisticated, artificial intelligence is moving into normal workflows, customers are validating businesses across more channels, and persistent cost pressure is making cash-flow planning more important.

These trends apply differently across industries. A restaurant, contractor, retailer, and trucking company will not use the same technology or financing structure. The practical goal is to identify the changes that matter to your operation, test improvements on a manageable scale, and measure the result.

‍

1. Cyber resilience is now an operating requirement

Cybersecurity has moved well beyond antivirus software and an occasional password change. Phishing, ransomware, compromised credentials, payment fraud, and AI-assisted impersonation can disrupt sales, expose customer information, and stop a small team from operating.

CIRA’s 2025 Cybersecurity Survey collected responses from 500 cybersecurity decision-makers across Canada. Among the organizations surveyed, 43% reported being targeted in a cyberattack during the previous 12 months, while 42% reported a breach involving customer or employee data. CIRA also found that 70% were concerned about threats associated with generative AI. The Canadian Centre for Cyber Security similarly describes the national threat environment as increasingly complex and sophisticated.

The practical response is to build a small set of repeatable controls. Use multi-factor authentication for email, banking, payroll, cloud storage, and administrative accounts. Keep software and devices updated, restrict access to the information each employee actually needs, maintain tested backups, and train staff to verify unusual payment or account-change requests through a second channel.

An incident-response plan matters as much as prevention. The plan should identify who will secure accounts, contact financial institutions or technology vendors, communicate with customers, and restore critical systems. CIRA reported that 66% of surveyed organizations had used their incident-response plan in the prior year, reinforcing the value of deciding these responsibilities before an incident occurs.

‍

2. AI and digital tools need a clear business purpose

Artificial intelligence is becoming more common in Canadian businesses, but adoption alone does not guarantee a productivity improvement. Statistics Canada reports that 12.2% of Canadian firms used AI to produce goods or deliver services in 2025, double the previous year’s share, while another 14.5% planned to adopt it within the following 12 months.

The same Statistics Canada analysis offers an important caution. Firms using AI initially appeared more productive, but the direct relationship was no longer statistically significant after accounting for prior productivity and complementary capabilities such as cloud computing, data analytics, research and development, and employee technology training. The evidence suggests that AI delivers more value when it is part of a broader operating system rather than an isolated software purchase.

A sensible starting point is one repetitive, measurable workflow. A business might use a digital tool to summarize service requests, organize inventory data, draft routine customer communications, or flag overdue invoices. The owner should define the expected result, protect sensitive information, keep a person responsible for review, and compare time, error rates, or conversion outcomes before expanding the tool.

CFIB’s 2025 digital-transformation report drew on a survey of 1,683 Canadian business owners and found that firms with deeper digital adoption consistently reported stronger productivity outcomes than firms with lower adoption. The broader lesson is to connect technology spending to a process, a responsible employee, and a performance measure.

‍

3. Customers verify a business across multiple channels

A prospective customer may encounter a company through a search result, review platform, social post, industry directory, referral, or AI-generated answer. They often continue checking before they make contact. That makes consistency across the company’s website, business listings, reviews, and third-party profiles an important trust signal.

BrightLocal’s 2026 Local Consumer Review Survey used a representative panel of 1,002 U.S. adults. It found that 97% read reviews for local businesses and that respondents used an average of six review sites while evaluating businesses. After reading positive reviews, 54% said they were likely to visit the company’s website. These are U.S. consumer findings rather than Canadian population estimates, but they illustrate how reviews frequently lead to additional verification rather than an immediate purchase.

For a small business, the practical work is straightforward. Keep the business name, phone number, address, service area, hours, and product descriptions consistent wherever the company appears. Request genuine reviews as part of a normal follow-up process, respond specifically to both positive and negative feedback, and never buy or incentivize misleading reviews. Publish detailed case studies or testimonials only with appropriate customer permission.

The company website must support what people find elsewhere. Clear service explanations, real leadership information, transparent contact details, and consistent business facts help visitors evaluate credibility. They also give search engines and AI systems better source material when answering questions about the business. Owners evaluating any financing company should review its reputation, verify its claims, and use a structured set of questions before choosing a business funder.

‍

4. Cash-flow flexibility remains a competitive capability

Revenue and profit do not always arrive on the same schedule as payroll, inventory purchases, repairs, tax obligations, or supplier payments. Persistent cost pressure makes that timing gap harder to absorb.

Statistics Canada reported that 62.2% of businesses expected cost-related obstacles in the third quarter of 2025. Inflation was the most frequently cited cost obstacle, and accommodation and food services and retail trade were among the sectors most likely to identify it. The practical implication is that owners need a current cash-flow forecast rather than relying only on an annual budget or income statement.

A useful forecast maps expected cash receipts and required payments by week, highlights possible shortfalls, and defines what action the business will take if sales, collections, or costs move away from plan. Owners can also review supplier terms, deposit policies, invoicing speed, inventory levels, recurring expenses, and the minimum reserve needed to cover critical obligations.

External financing may be part of that plan, but the product should match the purpose. Innovation, Science and Economic Development Canada reports that 97% of small-business debt-financing applications were approved in 2025 and that the average interest rate declined to 5.8%. However, 75% of small businesses obtaining debt financing were required to pledge collateral, up from 66% in 2024. Availability therefore does not tell an owner whether a product is appropriate for a particular need.

Before choosing funding, compare the total repayment amount, annualized cost where available, collateral or guarantee requirements, time to funding, payment frequency, flexibility during slower periods, early-payment terms, and permitted use of proceeds. A conventional loan or line of credit may suit a planned, longer-term investment. A merchant cash advance may be considered for a shorter-term working-capital need when speed and revenue-linked remittances are important, but its total cost should be reviewed carefully. Businesses with imperfect credit can also compare the broader range of business-funding options available in Canada.

‍

Turn trends into operating decisions

The most useful response to these trends is a short operating plan. Strengthen one cyber control, test one digital workflow, correct inconsistent public information, and update a 13-week cash-flow forecast. Each action should have an owner, a deadline, and a simple measure of success.

If a working-capital need remains after reviewing expenses, collections, reserves, and conventional financing, compare the available structures carefully. 2M7 can explain how its funding works and provide the total repayment and remittance terms for review. Readers can also consult the small-business finance glossary before requesting a quote or starting an application.

‍

Sources

  1. 2025 CIRA Cybersecurity Survey
  2. National Cyber Threat Assessment 2025–2026 — Canadian Centre for Cyber Security
  3. Artificial intelligence adoption and productivity in Canadian firms — Statistics Canada
  4. Digital Transformation: How small businesses in Canada are leveraging AI and technology — CFIB
  5. Local Consumer Review Survey 2026 — BrightLocal
  6. Canadian Survey on Business Conditions, third quarter 2025 — Statistics Canada
  7. Small Business Credit Condition Trends, 2015–2025 — Innovation, Science and Economic Development Canada

‍

Read more
August 19, 2026
September 30, 2026

Preparing Your Business for the Holiday Rush

The fourth quarter makes or breaks a lot of small businesses in Canada. Retailers and restaurants that get their staffing and inventory right in October and November tend to walk into January with healthy cash reserves. Those that wait until the first week of December to figure out their game plan usually spend the season scrambling, and scrambling costs money.

If you own a retail shop, a restaurant, or any business that lives and dies by foot traffic during the holidays, now is the time to lock in your plan. Here's how to think about staffing, stock, and cash flow so the next ten weeks work in your favour instead of against you.

‍

Start With Your Sales History, Not Your Gut

Too many owners plan the holiday season based on how busy last December felt rather than what the numbers actually showed. Pull your point-of-sale reports from the last two or three holiday seasons and look for patterns. Which products sold out early? Which days of the week saw the heaviest traffic? What time of day did your restaurant get slammed?

Analyzing past sales data to spot seasonal patterns is one of the most effective ways to avoid overstocking or running out of popular items. This isn't complicated analysis. Even a basic spreadsheet showing week-over-week sales from last November and December will tell you more than a gut feeling ever will.

For retailers specifically, this is also the moment to think seriously about how much inventory you actually need on hand versus how much cash you're willing to tie up in stock that might not move. If you've been turning down orders because you can't front the cost of holiday inventory, you might want to consider your options before you're forced to choose between restocking and making payroll.

‍

Staffing: The Problem Nobody Talks About Early Enough

Here's a fact that should change how you're thinking about hiring right now. The National Retail Federation recently predicted that holiday seasonal hiring would hit its lowest level in over 15 years, making early recruitment more critical than ever. That forecast is for the American market, but Canadian retailers and restaurants are competing for the same shrinking pool of available seasonal workers, and the labour crunch tends to move north with a short delay.

Practically, this means posting your seasonal job openings now, not in mid-November. It means offering shift flexibility and being upfront about pay. It also means having a real contingency plan if you can't fill every shift you need.

For restaurants, the stakes are a bit different but no less serious. Using past data to anticipate peak times helps restaurants build optimized schedules without over- or under-staffing. A kitchen that's short-staffed on a Friday night in December doesn't just lose sales, it loses customers who won't come back after a bad experience. If your restaurant's equipment is also aging and slowing down your kitchen's throughput during peak hours, that's a separate problem worth solving before the rush hits.

What Canadian Shoppers Are Actually Doing Differently

It's not enough to staff up and stock up the way you did last year. Consumer behaviour is shifting, and ignoring that shift means missing opportunities your competitors will catch. According to Retail Council of Canada's holiday shopping research, Canadian consumers are shopping earlier and comparing prices more carefully than in past years.

That earlier-shopping trend matters because it means your marketing and inventory need to be ready well before Black Friday, not scrambling to catch up to it. If your customers are comparison shopping more aggressively, your pricing, promotions, and in-store or online experience need to justify why they should buy from you instead of clicking over to a competitor's site.

Refreshing your online listings and promoting gift cards are easy, high-impact ways to prepare for the holiday shopping rush. Simple, low-cost moves like updating your Google Business listing, refreshing your website's holiday hours, and pushing gift card sales through email and social media can generate real revenue with almost no upfront cost.

‍

Give Shoppers a Reason to Walk Through Your Door

If customers are comparing prices and shopping online, your store has to earn the trip. Start with the basics: a slow checkout is one of the fastest ways to lose a holiday sale, so add a second register during peak hours and make sure your POS is ready for the volume. Then give people a reason to come in. A coupon, a limited-time discount, or a buy-one-get-one deal can do it. Costco has held its hot dog and soda combo at $1.50 since the mid-1980s because it draws people in, and they usually leave having bought a lot more than lunch.

Finally, walk your shop the way a customer would. A clean storefront, fresh signage, and a seasonal display cost far less than the sales they protect.

‍

Where Fast Funding Fits Into the Picture

Every piece of holiday prep costs money before it generates a dollar back. Inventory has to be purchased before it's sold. Staff have to be hired and trained before they're productive. Equipment repairs have to happen before the kitchen can handle a full house on a Saturday night.

This is where a lot of small business owners hit a wall, particularly if a bank has already turned them down or they don't have the time to wait six weeks for a traditional loan decision. A Merchant Cash Advance is built for exactly this kind of short-term, high-stakes timing problem. Rather than waiting on a lengthy approval process, you're leveraging future sales to access capital now, when you actually need it, not after the holiday window has already closed.

If your credit history isn't perfect, that shouldn't be the reason you miss the busiest quarter of your year. Many alternative lenders look past your credit score and focus on your recent revenue instead of your past setbacks. Fast business funding and small business loans through alternative lenders exist precisely because traditional banks move too slowly and too conservatively for the realities of running a seasonal business. 

Contractors and trades businesses often assume holiday funding conversations don't apply to them, but late Q4 and early Q1 are when many trades see a surge in emergency repair calls and pre-holiday renovation rushes. Having working capital on hand means you can staff up and stock materials without cash flow becoming the bottleneck.

‍

Get Ahead of It Now

Waiting until December to figure out staffing, inventory, and cash flow puts you behind before the season even starts. The businesses that come out of Q4 stronger are the ones making these decisions in October and November, while there's still time to act on them.

If you need capital to hire, stock up, or fix equipment before the rush hits, reach out to 2M7. We move fast, we understand Canadian small business realities, and we can get you funded well before you would have finished filling out bank paperwork.

Read more