Best overall for collateral-backed borrowing: a secured business line of credit. Best without pledged business assets: an unsecured line. Best alternative for eligible businesses comparing merchant cash advances: 2M7, a direct funder, not a line-of-credit provider. This 2026 guide ranks funding structures by business need rather than naming a bank winner without comparable offers.
TL;DR
- A secured business line of credit suits established businesses willing to pledge acceptable collateral.
- An unsecured business line of credit avoids specified collateral, but personal guarantees can still apply.
- Receivables-backed credit suits businesses with eligible unpaid customer invoices.
- 2M7 offers merchant cash advances, not revolving credit; compare the repayment structure before choosing.
What makes the best business line of credit?
- Reusable access: You can draw, repay and borrow again within the approved limit, subject to the agreement.
- Cash-flow fit: Required payments leave enough money for payroll, suppliers and taxes.
- Clear obligations: You understand interest, fees, guarantees and collateral requirements.
- Usable capacity: The amount actually available matches your operating needs.
- Acceptable conditions: Reporting, renewal and cancellation terms fit how your business operates.
Business credit options at a glance
1. Secured business line of credit
- Best for: Established businesses with acceptable collateral
- Standout feature: Revolving access supported by pledged assets
- Key limitation: Collateral is exposed if you default
2. Unsecured business line of credit
- Best for: Businesses seeking credit without specified pledged assets
- Standout feature: Revolving access without designated collateral
- Key limitation: A personal guarantee can still apply
3. Receivables-backed line of credit
- Best for: Businesses selling to customers on payment terms
- Standout feature: Borrowing availability tied to eligible invoices
- Key limitation: Availability changes with receivables eligibility
4. 2M7 merchant cash advance
- Best for: Eligible businesses considering an alternative to revolving credit
- Standout feature: Direct funding for working-capital needs
- Key limitation: Not a reusable credit facility
Why this matters
A business line of credit addresses a timing problem: expenses arrive before customer payments, and you need access to funds between the two. A revolving facility lets you borrow again after repayment, subject to its terms. A merchant cash advance works differently and should not be treated as an interchangeable product.
For your 2026 comparison, start with the problem you need to solve. Recurring supplier payments, outstanding invoices and a defined equipment purchase call for different conversations. The best option is the one whose repayment obligations fit your cash flow, not simply the one offering the largest limit.
1. Secured credit: best for businesses with collateral
A secured business line of credit gives you revolving access to funds against collateral the lender accepts. That security can include business assets, depending on the agreement. You draw what you need within the available limit and restore borrowing capacity through repayment, subject to the facility's conditions.
Best for: Established businesses that need recurring working capital and are comfortable pledging assets.
Secured credit pros
- Reusable borrowing suits repeated cash-flow gaps rather than a single purchase.
- An approved facility provides access without a separate application for every draw, subject to its terms.
- Collateral gives the lender a defined source of security when assessing the application.
Secured credit cons
- Pledged assets are exposed if the business defaults.
- Security requirements can complicate future financing involving the same assets.
- Reporting obligations and lender reviews can affect continued access.
What to check: Ask exactly which assets secure the facility. A security interest covering broad business assets has different consequences from security over one identified asset. Also ask whether a personal guarantee is required; business collateral does not automatically remove personal obligations.
Do not choose secured credit just because your business owns equipment or property. First check whether pledging those assets restricts another financing arrangement you need.
Verdict: Hold until the collateral, guarantee and renewal terms are clear. Secured credit is the default comparison point for established businesses willing to provide security, not an automatic recommendation for every asset-owning business.
2. Unsecured credit: best without specified collateral
An unsecured business line of credit provides revolving access without specified pledged collateral. The lender still evaluates the business and the application. Unsecured does not mean approval without underwriting, and it does not necessarily mean the owner has no personal responsibility.
Best for: Businesses seeking reusable working capital without assigning specified assets as collateral.
Unsecured credit pros
- You avoid pledging specified business assets under the facility.
- Revolving access supports repeated borrowing and repayment.
- Keeping assets outside a specific security arrangement can preserve flexibility for other financing discussions.
Unsecured credit cons
- A personal guarantee can still create obligations for the owner.
- The approved limit and application requirements depend on the lender's assessment.
- Renewal, review and cancellation provisions still matter.
What to check: Ask the lender to explain what unsecured means in the actual agreement. Confirm whether guarantees, account conditions or other obligations apply. Do not rely on the product name alone.
For a 2026 application, compare the usable limit with your largest expected cash-flow gap. A facility that cannot cover that gap does not solve your operating problem, even if its collateral requirements are attractive.
Keep the distinction between qualification and suitability clear. Approval tells you the lender accepts the application; it does not establish that the required payments fit your business.
Verdict: Hold until you understand the personal guarantee and available limit. Choose unsecured revolving credit for its structure, not because the word unsecured sounds consequence-free.
3. Receivables-backed credit: best for unpaid invoices
A receivables-backed line of credit links borrowing availability to eligible customer invoices. The lender assesses which receivables qualify and applies the agreement's borrowing rules. This differs from receiving an unrestricted limit based only on the business's overall profile.
Best for: Businesses that invoice customers on payment terms and have receivables a lender accepts.
Receivables-backed credit pros
- The facility connects working-capital access to unpaid customer invoices.
- Revolving borrowing can support the gap between delivering work and collecting payment.
- Availability can reflect changes in qualifying receivables, subject to the agreement.
Receivables-backed credit cons
- Overdue, disputed or otherwise ineligible invoices can reduce borrowing availability.
- Reporting and invoice administration create ongoing work.
- Customer concentration rules can limit how much of the receivables balance qualifies.
What to check: Ask how the lender treats overdue invoices, customer disputes and sales concentrated with one customer. Then calculate borrowing availability using those rules, rather than assuming every dollar invoiced creates an equal amount of credit.
A growing invoice balance does not automatically mean more usable funding. If the additional invoices fail the eligibility rules, the facility will not expand in the way you expect.
Also distinguish a receivables-backed line from factoring. A credit facility and an arrangement involving the sale of invoices have different contractual structures. Ask who collects customer payments and what happens when a customer does not pay.
Verdict: Hold until an invoice-level review confirms usable borrowing capacity. This option fits an invoicing business only when its receivables qualify.
4. 2M7: best for comparing a merchant cash advance alternative
A merchant cash advance is an alternative funding structure, not a business line of credit. It does not give you a revolving limit that automatically replenishes after repayment. Treat it as a separate decision when your business needs working capital.
2M7 merchant cash advances suit eligible Canadian businesses comparing direct funding with revolving credit. The company is a direct funder, not a broker, serving businesses operating for at least 3 months with $15,000 or more in monthly revenue. Its stated uses include payroll, inventory, equipment and cash-flow gaps.
Best for: Eligible small and mid-sized Canadian businesses considering working capital outside a revolving credit facility, including businesses with less-than-perfect credit.
Merchant cash advance pros
- You discuss funding with a direct funder rather than a broker.
- The stated eligibility includes businesses with at least 3 months of operating history.
- Working-capital uses include payroll, inventory and equipment.
- The fixed cost of capital is disclosed before signing and does not change based on repayment duration.
Merchant cash advance cons
- Repayment does not automatically restore a reusable credit limit.
- Eligibility requirements still apply; meeting initial thresholds is not an approval promise.
- Flex payments apply only to businesses processing daily card payments.
What to check: Confirm the total repayment obligation, collection method and effect on operating cash flow. If flexible payments matter to your decision, establish whether your business meets the daily card-payment condition before comparing that feature with other offers.
Verdict: Skip if you specifically need revolving credit. Consider this structure when you need defined working capital and the repayment obligations fit your business.
How to compare written offers in 2026
A useful funding comparison follows the money through your business. Check these elements in order before deciding which offer fits.
- Funding purpose: Identify the expense and whether it recurs. Separate an ongoing operating gap from a single purchase.
- Available funds: Confirm what you can actually draw, including restrictions tied to collateral or eligible invoices.
- Repayment obligations: Map required payments against expected customer receipts and essential operating expenses.
- Owner obligations: Identify guarantees, pledged assets and reporting duties before signing.
- Exit terms: Read renewal, cancellation and early-repayment provisions, including any conditions attached to them.
Do not compare a revolving credit limit directly with the amount of an advance. One describes access that can be reused under an agreement; the other describes funding that does not automatically replenish.
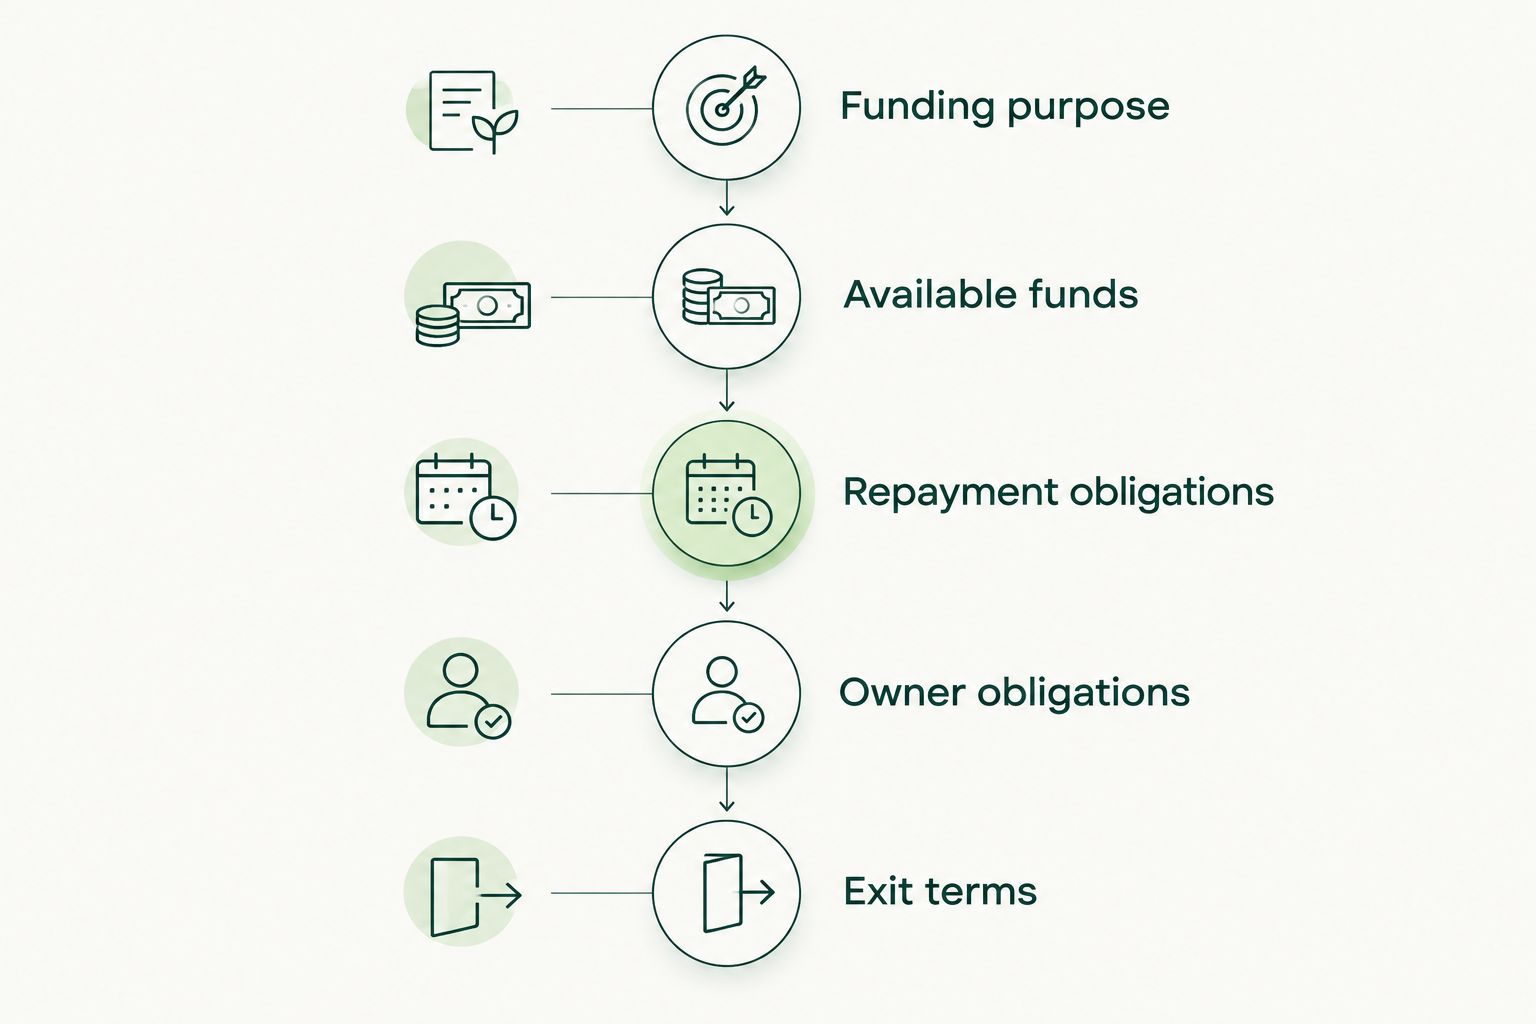
Compare obligations and usable access, not just the headline funding amount.
Build your comparison from written terms rather than a headline claim. If an important condition is unclear, ask the provider to explain it before you commit. Keep the explanation with the agreement so your operating decisions reflect the same terms.
How these options are ranked
This 2026 ranking prioritises revolving access, cash-flow fit, clear obligations, usable capacity and acceptable conditions. Secured credit comes first for established businesses willing to pledge collateral; unsecured credit serves a different need, while receivables-backed credit depends on qualifying invoices.
The merchant cash advance sits separately because it is not a line of credit. This is a structure-based buying guide, not a claim that one lender offers the best terms to every Canadian applicant. Your written offer determines the final comparison.
Which business line of credit should you choose?
Start with a secured business line of credit if your established business needs reusable funding and can accept the collateral obligations. Compare unsecured credit when you want to avoid specified pledged assets. Investigate receivables-backed credit when unpaid customer invoices drive the funding gap.
If you do not need reusable access, compare a merchant cash advance separately. Ask a funding specialist to explain the repayment structure in plain language. Do not choose a non-revolving product expecting it to behave like a credit line.
Discuss your funding options
Speak with a funding specialist about working capital and whether a merchant cash advance fits your business.
Discuss funding options
FAQ
What's the best business line of credit for a small business in Canada?
The best fit depends on collateral, cash flow and the need for reusable access. Start with secured credit if you can accept asset security, unsecured credit if you want to avoid specified collateral, or receivables-backed credit if eligible invoices support the facility.
Is an unsecured business line of credit free of personal obligations?
No. An unsecured business line of credit can still require a personal guarantee. Read the guarantee and other obligations rather than treating unsecured as a promise of no personal responsibility.
Does repaying a business line of credit let me borrow again?
A revolving business line of credit generally restores borrowing availability as you repay, subject to the agreement. Limits, lender reviews and other conditions still govern what you can draw.
Is a merchant cash advance the same as a business line of credit?
No. A merchant cash advance does not provide a revolving limit that automatically replenishes after repayment. Compare its repayment obligations separately from a reusable credit facility.
Can a newer Canadian business consider 2M7 funding?
2M7 serves businesses operating for at least 3 months with $15,000 or more in monthly revenue. Those are initial eligibility criteria, not an approval promise, and its product is a merchant cash advance rather than a business line of credit.
What should I ask before signing a business credit agreement in 2026?
Ask about usable borrowing availability, repayment obligations, guarantees, collateral, reporting, renewal and cancellation. Request clarification of anything that could restrict access or affect your operating cash flow.
Is receivables-backed credit the same as invoice factoring?
No. A receivables-backed credit facility and an arrangement involving the sale of invoices have different contractual structures. Confirm invoice ownership, collection responsibilities and what happens if a customer does not pay.
One last thing
A credit limit is not the same as money you can safely spend. Before accepting any 2026 offer, place its required payments alongside payroll, tax obligations and supplier commitments. If the funding solves one payment gap but creates another, change the amount or structure before signing.
Related guides


