Best overall for long-term ownership: an equipment loan. Best for planned replacement: an equipment lease. Best for flexible purchases: a business line of credit. This 2M7 guide compares equipment financing options in Canada for 2026 by ownership, cash flow and contract restrictions—not by advertised payments alone.
TL;DR
- 2M7’s equipment financing Canada guide ranks equipment loans first for businesses seeking long-term ownership.
- Equipment leases suit planned replacement, but return conditions and purchase options need close review.
- Business lines of credit suit flexible purchases when repayment does not crowd out operating cash.
- Compare vendor-arranged financing with direct financing using the same equipment quote and repayment assumptions.
Why this matters
Equipment financing affects more than your payment schedule. It determines whether you own the asset, what security the financier takes and what happens when you replace or sell the equipment.
A payment that fits today does not settle the decision. Your business also needs enough cash for maintenance, insurance, payroll and periods when the equipment produces less revenue.
For 2026, start with the asset’s job in your business. A machine you intend to keep needs a different financing assessment from equipment you expect to replace as your work changes.
What makes the best equipment financing option?
Use these criteria before comparing offers. The strongest option fits the equipment’s working life and your repayment capacity without creating an unwanted exit obligation.
- Ownership: Decide whether you need title to the equipment or only the right to use it.
- Payment fit: Match scheduled obligations to cash your business can reliably generate, not its busiest period.
- Total obligation: Compare the full payment schedule, fees and any required final payment or purchase amount.
- Security: Identify the assets pledged and whether a personal guarantee is required.
- Exit terms: Check early repayment, early termination, sale restrictions and end-of-term responsibilities.
- Asset fit: Confirm that the proposed arrangement accepts the specific equipment, condition and intended use.
Ask for written terms. A verbal explanation of ownership or an end-of-term purchase option is not a substitute for the contract.
Equipment financing options at a glance
These 5 financing routes serve different needs. Vendor-arranged financing describes how you obtain the offer; the underlying contract can still be a loan or lease.
Equipment loan
- Best for: Long-term ownership
- Standout feature: Finances an equipment purchase with scheduled repayment
- Key limitation: Security and repayment obligations remain until discharged
Equipment lease
- Best for: Planned replacement
- Standout feature: Provides equipment use under an agreed lease term
- Key limitation: Ownership and exit depend on the contract
Business line of credit
- Best for: Flexible purchases
- Standout feature: Allows borrowing and repayment within an approved facility
- Key limitation: Equipment debt can consume working-capital capacity
Vendor-arranged financing
- Best for: Purchase coordination
- Standout feature: Connects the equipment purchase with a financing application
- Key limitation: Convenience does not establish the best financing terms
Secured business loan
- Best for: Equipment within a broader project
- Standout feature: Can fund an eligible project containing equipment and other expenses
- Key limitation: Security can extend beyond the purchased equipment
The table ranks financing structures, not lenders. Approval criteria, documentation and contract terms differ between providers, so the same structure can produce very different obligations.
1. Equipment loan: best equipment financing for long-term ownership
An equipment loan finances the purchase of equipment and requires repayment under an agreed schedule. The business purchases the asset, while the lender can take security over it or other agreed assets.
An equipment loan is the default choice when ownership is the goal and scheduled repayments fit the business. That does not make every equipment loan suitable: the security agreement, repayment terms and asset restrictions still decide whether the offer works.
Equipment loan pros
- Supports purchasing equipment you intend to keep.
- Provides a defined repayment schedule under the agreement.
- Separates the purchase from a lease-return decision.
- Lets you assess financing alongside the equipment’s expected working life.
Equipment loan cons
- Repayments continue even when the equipment is idle.
- Security requirements can restrict disposal of the asset.
- Early repayment conditions require review before signing.
Best for: Businesses buying equipment for continuing use rather than routine replacement.
Before accepting a 2026 equipment loan, ask what happens if the asset needs replacement before repayment ends. You need to know whether sale proceeds can discharge the financing, whether lender consent is required and whether any remaining balance survives the sale.
Verdict — Buy: Choose an equipment loan when you want ownership and can support the repayment schedule through quieter trading periods.
2. Equipment lease: best equipment financing for planned replacement
An equipment lease gives your business the right to use equipment under an agreement with the lessor. The contract determines the payment schedule, permitted use, maintenance responsibilities and end-of-term choices.
A lease is not automatically a path to ownership. If ownership matters, identify the purchase option and its conditions before comparing the lease with a loan.
Equipment lease pros
- Suits businesses focused on equipment use rather than immediate ownership.
- Establishes a defined term for the equipment arrangement.
- Allows a planned end-of-term decision where the contract provides suitable choices.
- Can align with a replacement plan when the lease conditions support it.
Equipment lease cons
- Early termination can create contractual obligations.
- Return conditions can add work and expense at the end.
- A purchase option is not the same as an unconditional transfer of ownership.
Best for: Businesses with a defined replacement plan and equipment needs that fit the lease term.
For a 2026 lease comparison, request the return requirements alongside the payment schedule. Equipment condition, transport responsibilities and notice deadlines belong in the decision, not in a separate file you read later.
Also distinguish financing from service. Maintenance, repairs and replacement equipment are included only when the agreement explicitly says so.
Verdict — Buy: Choose an equipment lease when the use period and end-of-term obligations match your replacement plan; skip it when ownership terms are unclear.
3. Business line of credit: best equipment financing for flexible purchases
A business line of credit allows borrowing within an approved limit under the facility’s terms. It can fund equipment purchases where the agreement permits that use, without a separate equipment-financing contract for each purchase.
Flexibility is its main advantage. The trade-off is that the equipment purchase uses capacity your business might otherwise need for operating expenses.
Business line of credit pros
- Supports purchases at different times within the approved facility.
- Allows repayment and further borrowing under the agreement.
- Avoids matching every purchase to a separate equipment contract.
- Provides flexibility when the final purchasing schedule is uncertain.
Business line of credit cons
- Equipment borrowing reduces remaining credit capacity.
- Variable-rate terms expose borrowing costs to rate changes.
- An accessible facility still needs a deliberate repayment plan.
Best for: Businesses making flexible purchases while preserving enough unused capacity for operations.
Do not treat the available limit as an equipment budget. First reserve the capacity needed for supplier payments, payroll and revenue interruptions, then assess what remains.
Compare a line of credit with a dedicated equipment loan when the purchase will stay financed for a long period. Flexible borrowing is useful only if the repayment plan fits the asset and does not leave operating cash permanently constrained.
Verdict — Hold: Use a business line of credit for equipment only after setting a repayment plan and protecting working-capital capacity.
4. Vendor-arranged financing: best equipment financing for purchase coordination
Vendor-arranged financing connects an equipment purchase with a financing offer or application through the seller. The seller might introduce a financing provider or present an arrangement available for that purchase.
This is a purchasing channel, not a distinct financial contract. Determine whether the actual offer is a loan, lease or another agreement before assessing its suitability.
Vendor-arranged financing pros
- Coordinates the equipment quote with the financing application.
- Keeps the proposed asset clearly identified during the process.
- Gives you an offer to compare with independently obtained financing.
Vendor-arranged financing cons
- The presented offer does not represent every financing option.
- Purchase convenience can distract from security and exit terms.
- The financing provider and equipment seller can be separate parties.
Best for: Buyers who want coordinated purchasing but will still compare the written financing agreement.
Request the equipment quote separately from the financing schedule. This makes it easier to compare the same asset across offers without confusing equipment charges with financing obligations.
For a 2026 purchase, ask who handles an equipment dispute and who collects payments. Do not assume a dispute with the seller automatically pauses obligations to a separate financier.
Verdict — Hold: Consider vendor-arranged financing after comparing its underlying contract with a direct financing offer for the same equipment.
5. Secured business loan: best equipment financing for a broader project
A secured business loan can fund eligible business purposes under the lender’s agreement. Equipment can form part of a wider project that also includes installation, premises work or other approved expenses.
This route deserves consideration when the equipment purchase is only one part of the funding need. Its central limitation is the security package: assets beyond the equipment can be pledged.
Secured business loan pros
- Can address an eligible project rather than an isolated asset purchase.
- Allows equipment and related approved expenses to be assessed together.
- Provides a repayment structure for the agreed borrowing.
Secured business loan cons
- Security can extend beyond the financed equipment.
- Broader funding needs require careful documentation of eligible uses.
- Project delays do not automatically change repayment obligations.
Best for: Businesses funding equipment within a defined expansion or installation project.
Separate the equipment budget from the rest of the project before applying. You need to understand which expenses the proposed facility covers and which must come from existing cash.
Compare this route against a dedicated equipment loan plus separately funded project expenses. The choice depends on repayment fit and security exposure, not simply whether one agreement feels easier to administer.
Verdict — Hold: Choose a secured business loan when the wider project justifies it and the pledged assets are acceptable.
How the options are ranked
This 2M7 equipment financing guide ranks each route by its clearest use case: ownership, planned replacement, purchasing flexibility, purchase coordination or broader project funding.
Equipment loans take the default position because they directly address an equipment purchase with ownership as the objective. Leases take the replacement slot; lines of credit take the flexibility slot. Vendor arrangements and broader secured loans require an additional check because the channel or project scope does not itself establish suitable financing terms.
No ranking substitutes for reviewing the actual contract. An unsuitable equipment loan loses to a lease that genuinely fits your business.
Check cash flow before choosing
Build a 12-month cash-flow forecast that includes the proposed financing obligations and equipment operating expenses. Use 3 cash-flow scenarios: expected trading, weaker revenue and an equipment interruption.
Follow this sequence before signing:
- Define ownership: State whether you need to own the asset or use it for a defined period.
- Check obligations: Include scheduled payments, required fees and end-of-term commitments.
- Stress cash flow: Test repayment alongside payroll, suppliers, maintenance and insurance.
- Review exit: Read the conditions for repayment, termination, sale or return.
The weaker-revenue scenario should show whether your business can meet obligations without relying on the equipment operating continuously. The interruption scenario should include the operational consequence of downtime as well as the financing payment.
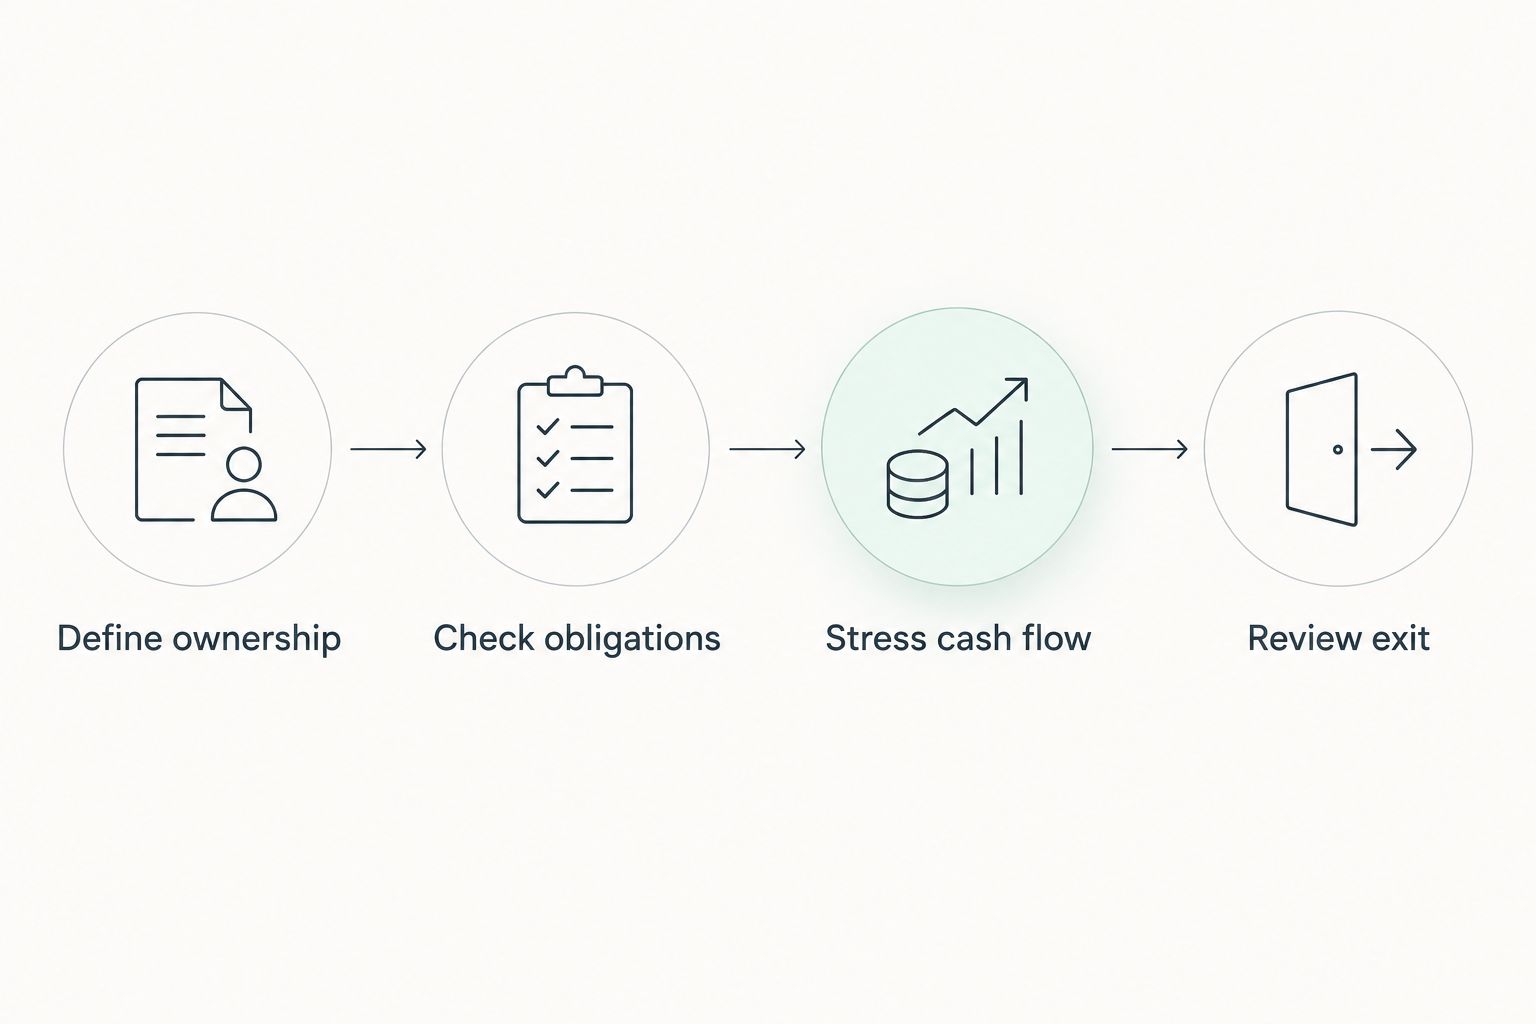
Check repayment capacity and exit terms before accepting the financing agreement.
Keep assumptions consistent across offers. Comparing one arrangement using strong sales and another using cautious sales tells you nothing useful about the financing itself.
Which equipment financing option should you choose?
Choose an equipment loan first when you want to own equipment for continuing use. Compare a lease when replacement is planned, and consider a line of credit only when equipment borrowing leaves sufficient operating capacity.
For equipment financing in Canada in 2026, use the 2M7 guide to choose the structure before comparing providers. Then compare written offers for the same equipment, funding need and intended use period.
If none of the offers survives your cash-flow checks, wait. Financing does not fix a purchase that your business cannot support.
FAQ
What’s the best equipment financing option in Canada?
An equipment loan is the default option for businesses seeking long-term ownership and scheduled repayment. A lease fits planned replacement better when its end-of-term conditions match the business’s needs.
Is an equipment loan better than a lease?
An equipment loan is better aligned with ownership; a lease is better aligned with use over an agreed term. Compare security, repayment obligations and exit conditions before choosing.
Can I buy equipment with a business line of credit?
You can use a business line of credit for equipment when the facility permits that use. Set a repayment plan and preserve enough capacity for operating expenses.
Does an equipment lease include maintenance?
An equipment lease includes maintenance only when the agreement explicitly provides it. Review responsibility for repairs, servicing, insurance and equipment downtime separately.
Is vendor financing a loan or a lease?
Vendor-arranged financing can involve a loan or lease, depending on the underlying agreement. Identify the actual financing provider and contract type before comparing the offer.
How much does equipment financing cost in Canada?
Equipment financing costs depend on the written offer, including financing charges, fees and required final obligations. Compare complete schedules for the same equipment and funding need rather than payments alone.
What should I check before signing an equipment financing agreement?
Check ownership, payment obligations, security, guarantees and exit conditions before signing. Test the agreement against expected trading, weaker revenue and an equipment interruption.
One last thing
The end of the agreement belongs in the beginning of your decision. Before accepting equipment financing in 2026, write down exactly what you must do to own, return, sell or replace the asset.
If you cannot explain that outcome in plain language, pause and get the relevant contract clause clarified. The final obligation matters as much as the first payment.


